National Private Money Lenders
Both are business-purpose loans, which changes how they’re reviewed, priced, and documented compared to an owner-occupied mortgage.

 Lendmire Research
Both are business-purpose loans, which changes how they’re reviewed, priced, and documented compared to an owner-occupied mortgage.
Investment-property HELOCs exist, but they carry lower leverage, higher credit floors, and far fewer available lenders than a HELOC on a primary home.
Big banks, credit unions, and community banks typically sit in the first camp, capped by how many financed properties a borrower can carry.
Most sponsors who pool money from more than a few people rely on a Regulation D exemption, usually Rule 506(b) or 506(c).
– The lenders most likely to say yes are credit unions, portfolio lenders, and non-QM wholesale shops.
Using Home Equity To Invest — Homeowners tap built-up equity through a home equity line of credit, a home equity loan, or a cash-out
– “First-lien” or “first-position” describes where the loan sits on title — it isn’t a named program you shop by brand.
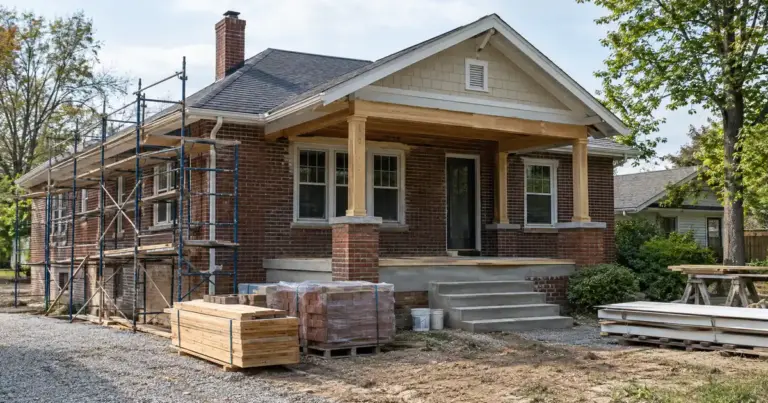
The lender sizes it on the deal (purchase price, rehab budget, and finished value), not on your paycheck.
None of this is “no documentation.” It’s a different documentation path, built around cash flow and assets instead of a tax return.
When Should You Cash Out Refinance: what borrowers need to know about cash-out refinancing — eligibility, documentation, and loan structure, from Lendmire.
Neither phrase is a legal term or a regulator-defined category; they’re industry shorthand for two ends of the same spectrum.
Using Home Equity For Investment Property — Home equity converts into investment-property capital through three structurally different
Statements confirm your identity, verify reserves and source of funds, and on some programs calculate income directly.
LLC-titled rentals face a separate, sharper restriction that most retail lenders can’t work around at all.