
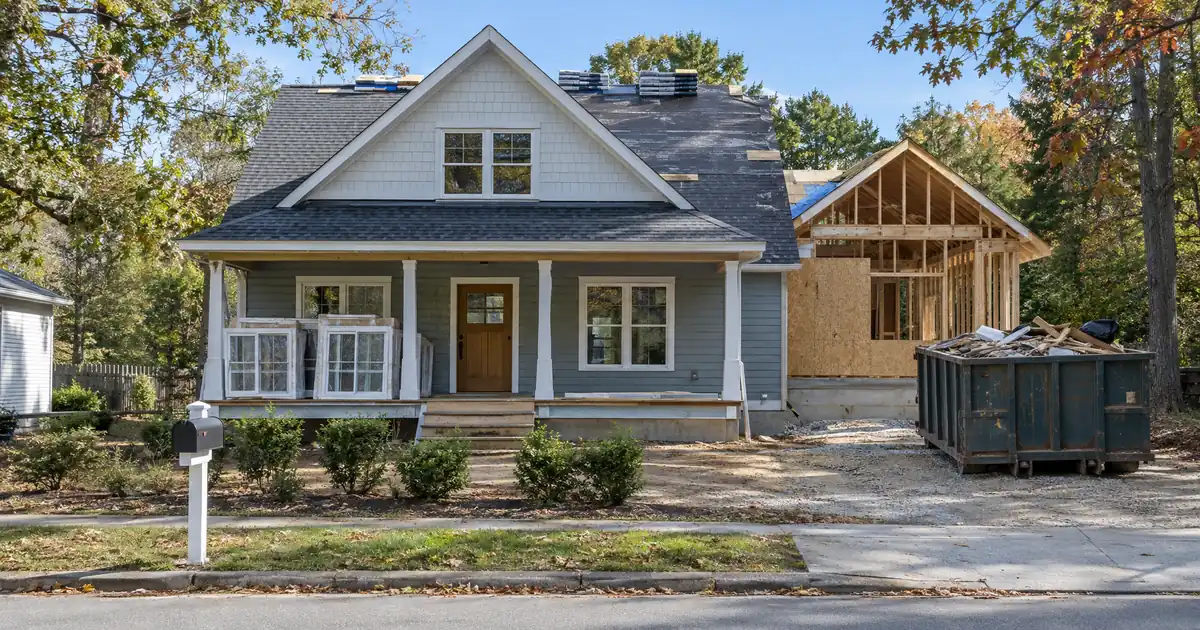
The Quick Read: A bank loan is built to lend against a finished property and a borrower’s long-term income. A flip is a short project that depends on the value the property will have after repairs. Those two designs collide on valuation, timing, rehab funding, and loan term, and the problem is the product, not your credit.
- Banks value the house as it sits today, while a flip depends on its after-repair value (ARV).
- Conventional loans fund one lump sum, with no built-in rehab money.
- Bank files carry layers of personal documentation, and carry costs build every day the file is open.
- A bank loan is shaped around long amortization, while a flip needs a short, interest-only runway.
- Narrow exceptions exist, mostly light cosmetic flips with a patient seller.
Is It Your Credit or the Product?
Usually it is the product. Many first-time flippers hear a bank decline and assume they failed a personal test. In most cases the loan simply was not designed for the deal.
What this loan actually costs to carry.
Hard money is sized against the project and priced by time. Enter the deal and see how much the program will lend, the cash required at closing, the carry while you hold it, and what is left at the exit.
Leverage tiers on the current program: 85% with fewer than 2, 90% with 2 or more, 93% with 5 or more completed projects — every tier capped at 75% of after-repair value. Loan amounts up to $5,000,000, larger by exception; terms of 6 to 18 months, interest-only, no prepayment penalty. The rehab portion funds in draws against completed work, not at closing.
Program parameters shown update from Lendmire’s centralized guideline source. Rate, points, and months are editable assumptions, not quoted terms.
Cost cap sets the loan · positive spread
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Rate, points, and months are editable assumptions. Hard money is business-purpose financing for real estate investors, not a consumer mortgage. Leverage on the current program tops out at 93% of project cost for investors with a documented track record, capped at 75% of after-repair value, with rehab funding up to 100% of the documented budget released in draws; actual terms vary by lender, borrower experience, property, and exit. Lendmire is a mortgage broker, not a lender.
A bank looks at you first. It reviews your credit, income, debts, and reserves, then checks whether the property supports the loan today. A flip lender looks at the deal first: purchase price, scope of work, ARV, and how you plan to exit. Your profile still matters, but it ranks behind the asset and the plan.
That split explains why a borrower with strong traditional employment income can still stall on a gutted house. The bank is asking whether you can carry a long-term mortgage. The flipper needs to know whether the project can be bought, renovated, and sold on schedule.
How a Bank File Actually Moves, Step by Step
Following a bank file from application to funding shows where a flip breaks it. Each step is reasonable for a long-term mortgage. Several are costly for a short project.
1. Application and documentation. The bank collects income records, asset statements, and debt details.
2. Appraisal. The appraiser values the property in its current condition. A distressed house appraises at distressed value, which may not support the loan the deal needs.
3. Underwriting. The deal works through multi-layer review. Every condition or request for more paperwork adds time while the seller waits.
4. Funding. The bank sends one lump sum at closing. Nothing is set aside for the renovation.
5. Repayment. The bank expects a long amortization schedule. A flip investor expects to sell or refinance within months.
Steps two and four do the most damage. The appraisal tests the wrong number, and the lump-sum funding leaves the rehab unpaid. You can finish step five perfectly and still own a house you cannot afford to repair.
What Decides Whether a Bank Can Fund the Deal
Four variables decide the outcome. The first is the property’s condition at appraisal. The second is the seller’s closing window. The third is how much of the budget is rehab rather than purchase. The fourth is the exit plan.
When the budget is mostly rehab, the bank’s as-is appraisal is furthest from the number that matters. When the seller has other offers, a long file loses the contract. When the exit is a resale in a few months, a long-term loan structure brings little benefit.
Notice what is missing from that list. Your W-2 profile has far less weight with flip lenders than with banks.
What a Flip-Focused Structure Looks Like
A hard money loan is short-term, asset-based financing for business-purpose real estate. The lender cares most about the property, the plan, and the exit. Lendmire arranges these loans as a broker through select lenders in its wholesale network, across 41 markets including Washington, D.C.
The figures below are typical ranges. They vary by lender, property, and experience, and nothing here is a commitment to lend.
- Leverage on a flip: about 85% of project cost with fewer than two completed projects, 90% of project cost at two or more, and 93% of project cost at five or more. Every tier is capped at 75% of ARV.
- Rehab money: up to 100% of the rehab budget funds in draws released against completed work. That is a rehab-budget figure, not a purchase LTV.
- Purchase without rehab: up to 80% of purchase price on a bridge loan.
- Term: 6 to 18 months, interest-only, with no prepayment penalty.
- Credit: a 620 minimum score, with added conditions below 660. First-time investors qualify at the lower leverage tiers.
- Size and property type: loans up to $5,000,000, larger by exception, on non-owner-occupied residential property of one to four units.
Underwriting stays asset-based. The lender reviews the property, the rehab plan, and the exit rather than only your personal income profile.
| Factor | Bank Loan | Flip-Focused Loan |
|---|---|---|
| Underwriting focus | Borrower income and credit | Property, plan, and exit |
| Valuation basis | Current condition | Current value plus ARV cap |
| Rehab funds | None built in | Released in draws |
| Loan term | Long amortization | Short, interest-only |
| Documentation | Heavy personal records | Centered on the deal |
| Best fit | Finished, rentable property | Renovate-and-resell project |
Why Banks Are Built This Way
Banks are not being unfair. They hold loans for years, so they price and underwrite for long-term interest income. A six-month loan on a gutted house does not match that model.
The regulatory frame points the same direction. Credit extended primarily for a business or commercial purpose is exempt from consumer-credit rules under CFPB Regulation Z, and the creditor decides in each case whether a loan is primarily for an exempt purpose. In its 2013 ability-to-repay rulemaking, the Bureau said investment-purpose loans are business-purpose loans. A flip therefore sits outside the consumer-mortgage mold that bank products are designed around. Business purpose does not mean compliance-free, but the main friction here is product design, timing, and collateral rather than a legal ban.
When a Bank Loan Can Still Work
A bank loan can fit a flip, but only in a narrow set of cases. Honest advice names them.
A light cosmetic flip. If the house passes a standard appraisal, needs only paint, flooring, and fixtures, and the seller has a flexible closing window, a bank loan can work. You may also save closing costs compared with rolling out of a short-term loan.
A cash purchase followed by a refinance. Some investors buy with cash and refinance later into rental financing. That avoids loan costs up front, but it ties up capital and is hard to scale past a deal or two.
An existing bank relationship. An experienced borrower with a bank that knows the plan can sometimes get a bridge arrangement. That is a relationship exception, not a general product.
The flip point is the rehab share of the budget. When the repairs are a small slice of the total, the bank’s as-is appraisal is close to the right number. When the repairs are most of the budget, it is not.
Run the Cost of Delay on Your Own Deal
Most investors compare loan costs and ignore delay costs. Do both.
Delay costs have two parts. The first is the carry you pay while the file is open: daily taxes, insurance, utilities, and any interest on the purchase. The second is the chance of losing the contract. Cost of delay equals the daily carry multiplied by the days of extra processing, plus the profit you lose if the seller takes another offer.
Consider a scenario where an investor buys a house that needs heavy work. The plan uses 90% of project cost, capped at 75% of ARV, on a short interest-only term. The numbers support a margin at resale. Now route the same deal through a bank. The as-is appraisal comes in low, the rehab has no funding source, and the seller moves to a buyer who can close sooner. The bank’s lower borrowing cost never gets a chance to matter, because the deal is gone.
Treat your ARV as a planning number, not an appraisal. Build a cushion for repair overruns and a longer resale window. Short terms leave less room for surprises than a long mortgage does.
Where DSCR Fits (After the Flip, Not During It)
A DSCR loan is not a flip loan. It needs a finished, rentable property, and it compares rent to the full monthly obligation (principal, interest, taxes, insurance). The complete DSCR loans guide covers the mechanics.
Many investors use a short-term loan first and refinance into long-term DSCR investor loans once the property is stabilized. At that point the refinance appraisal sets the value, not your ARV, and the loan is limited by the lower of the value cap and the rent-coverage cap. A DSCR ratio at or above 1.00 is where select programs begin. It is not the same as positive cash flow, because repairs, vacancy, management, and capital expenses sit outside the calculation.
Five Questions to Decide
1. Does the property need enough work that a standard appraisal would come in low?
2. Is the seller’s closing window shorter than a bank process can reliably meet?
3. Is rehab a large share of the total budget?
4. Do you need rehab money released in draws rather than one lump sum?
5. Is your exit a resale or refinance on a short timeline?
Answering yes to two or more points toward a flip-focused structure. If every answer is no, a bank loan deserves a real look.
Key Terms Defined
After-repair value (ARV): the estimated market value of a property once renovations are finished.
As-is value: what a property is worth in its current condition, before any work.
Draw: a release of rehab funds to the borrower after the lender confirms that a stage of work is complete.
Loan-to-cost: the loan amount as a share of the total project cost, which includes purchase price and rehab budget.
Interest-only term: a loan period in which the borrower pays interest and repays principal at payoff.
DSCR: the ratio of a property’s rent to its monthly debt obligation, used to qualify rental loans.
Frequently Asked Questions
Do banks give fix-and-flip loans?
Sometimes, but not often and not for most flips. A bank may lend on a flip that needs only light cosmetic work and has a patient seller. For heavy rehabs or tight seller timelines, the product rarely fits.
Can a bank loan fund the rehab?
Typically not. Conventional loans fund one lump sum at closing, and nothing is set aside for repairs. A flip-focused structure can fund up to 100% of the rehab budget in draws against completed work, varying by lender, property, and experience.
Why does the appraisal matter so much?
The bank sizes the loan to what the house is worth now. A distressed property appraises at distressed value, and that figure may not support the loan the project needs. Flip lenders look at current value alongside the ARV, with leverage capped at 75% of ARV.
What is the difference between hard money and a bank loan?
Hard money is a short-term, asset-based loan from a nonbank lender. Terms usually run 6 to 18 months, interest-only, and the lender focuses on the property and the exit. A bank loan focuses on your income and credit and is shaped around a long repayment schedule.
Is a DSCR loan a way to fund a flip?
No. DSCR financing is an exit for a finished, rentable property. Investors commonly refinance into it after the rehab is complete and the property is stabilized.
Next Step
If you are buying, rehabbing, or refinancing an investment property on a short timeline and want to see how the numbers work, Lendmire can help you compare hard money options based on the project, the exit plan, leverage, and your goals. Reach the team at 828-256-2183 or request a quote.
Tax treatment varies by situation; consult a qualified tax professional about how flip profits are taxed.
Whatever the loan, the deal that survives is the one where the financing was matched to the project before the offer went in.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, a fit for self-employed investors and LLC-owned portfolios. Lendmire was recognized as a Scotsman Guide Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Federal Register, Ability-to-Repay and Qualified Mortgage Standards Final Rule
This article is part of Lendmire’s hard money loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Should You Choose a 24-Month Bank Statement Loan or a Bridge Loan? · Can You Get a Hard Money Loan to Fix and Flip a Triplex? · Can You Buy a Flip in an LLC With a Hard Money Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.