
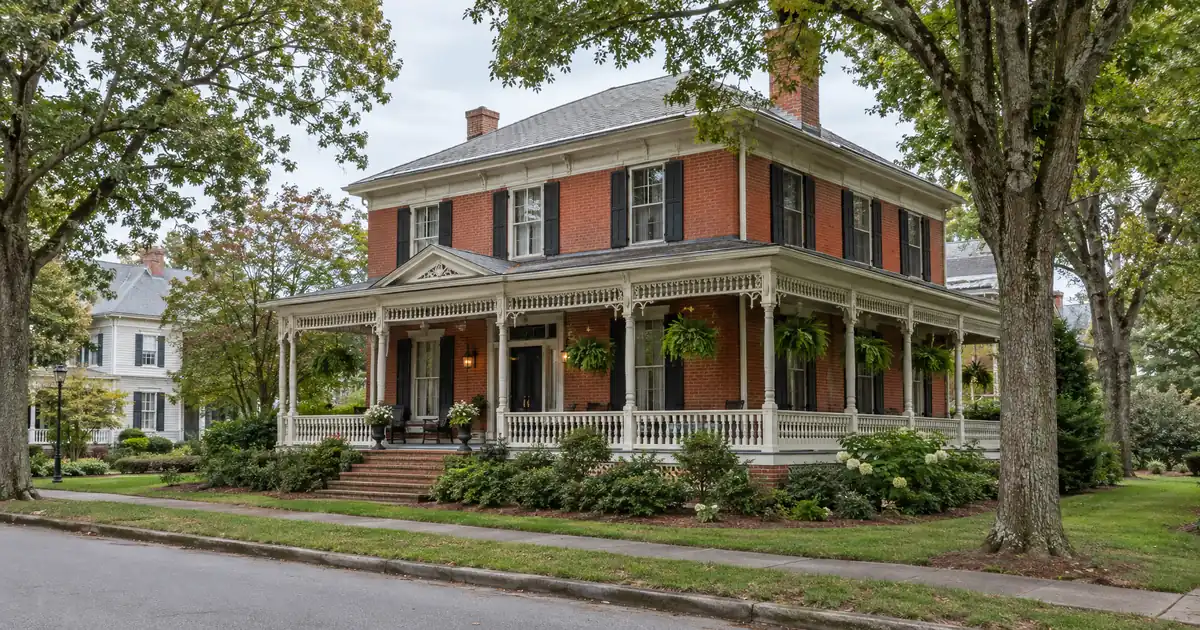
Riverside sits between the medical center and the downtown grid, and its older bungalows are the most natural cash-out candidates in Columbia. Local listings show single-family homes there alongside a renovated quadruplex on Riverside Drive, per NashvillesMLS. These are owners with paid-down balances and modest cost bases, which is the profile cash-out lenders want to see. But Columbia’s price growth is nearly flat, so the equity in these houses came from the purchase, the rehab, and the paydown, not from the market.
TL;DR: A cash-out refinance on a Columbia, Tennessee investment property is a loan against equity you already own, reviewed primarily on the rent the property produces measured against its full monthly obligation, with proceeds funding your next acquisition.
DSCR Cash-Out Calculator
Run the cash-out numbers in Columbia, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow puts the average Columbia home value at $374,557, up just 1.0% year over year.
- Cash-out LTV tops out at 75%, with about six months of title seasoning typical.
- Single-family rents near $1,888 for a 3BR pencil thin on a purchase-level basis.
- Duplexes and small multifamily carry the strongest coverage but are thin on supply.
- Maury County layoffs at the GM and Ultium plants are the main tenant-demand risk.
Columbia Market Snapshot
A quick read on the Columbia investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | 60% of rentals $1,001–$1,500 (RentCafe, Columbia TN) |
| University enrollment | 5,712 total (Data USA, Columbia State) |
| Employment | 710 employees (Fox17 (WZTV), Ultium layoffs) |
Why Flat Appreciation Changes the Equity Math
Equity in Columbia is built through basis, improvements, and amortization. It is not delivered by market lift. Zillow shows an average home value of $374,557, up 1.0% over the past year, with homes going pending in about 33 days. That is a stabilizing market, not a boom. Other sources disagree on level, because average value indexes, median sale prices, and median list prices measure different things, but they agree on direction: soft, with longer days on market.
The practical consequence is that an investor who bought several years ago at a discount, or who renovated an older house, holds real equity. An investor who bought recently at full price probably does not. Appraisers will lean on recent sold comps, and Columbia’s comp pool is mixed. CommunityScale reports that permits since 2020 represent 21.0% of the housing stock. That is a heavy new-build share, and builder pricing and incentives can pull down values on comparable resale homes. Assume a conservative appraisal, then work backward.
The program guardrails are straightforward. Lendmire, a DSCR-focused mortgage broker, arranges cash-out refinances through wholesale lending channels, and on most files the ceiling is 75% of appraised value. Lenders typically look for about six months of ownership measured from title recording, roughly six months of PITIA in reserves, and a credit floor around 620, with better tiers at 660, 680, and 700. Standard programs run up to $3,000,000. All of it is subject to lender guidelines, credit approval, and property review, and no cash figure is guaranteed until the appraisal and the coverage number are in.
Where the Coverage Math Holds in Columbia
Coverage in Columbia works on lower cost bases and stacked units. On a typical single-family house at the citywide average value, it does not clear 1.00 on a 75% cash-out. The reason is the rent-to-price ratio. Rentometer puts average rent at $1,316 for a 1BR, $1,408 for a 2BR, $1,888 for a 3BR, and $2,303 for a 4+BR. Against Zillow’s $374,557 value, the 3BR figure works out to roughly 0.50% of value per month. That is approximate gross, mixing two sources, and well under the classic 1% benchmark. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Run the numbers on two modeled cases. These are assumptions for illustration, not sourced market figures. Coverage below is rent divided by full PITIA, meaning principal, interest, taxes, and insurance.
- Modeled 3BR house at a hypothetical average-value basis, 75% LTV, assumed rent near the modeled level: coverage lands below 1.00 once taxes and insurance are included, so rent does not fully cover the payment.
- Modeled 3BR house on a $300,000 basis, 75% LTV, same assumed rent: coverage rounds to about 1.05 including taxes and insurance, which is barely over the line.
- Modeled duplex on a $340,000 basis, 75% LTV, two 2BR units at an assumed rent each: coverage rounds down to about 1.4 including taxes and insurance. These are illustrative assumptions, not sourced market figures, and final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The second case is the one to underline. It clears the 1.00 baseline, but a small change in insurance or a softer rent takes it back under. A 1.00x benchmark is common because rent covers the payment at that level, though exact eligibility depends on the lender, credit profile, reserves, and property review.
When a Columbia house lands under 1.00, the paths a lender may review include a sub-1.00 program, an interest-only structure, a lower LTV, or additional reserves. Each carries its own pricing and leverage terms, and none is assured. The stronger play for many owners is a smaller cash-out on the house, keeping coverage above the line.
Honestly, this one’s a toss-up for single-family owners: pull equity now at a thin ratio, or wait for the rent to catch up. Rents have not been cooperating. Zumper shows average rent at $1,500, down 14% over the year, with houses at $1,795 and apartments at $1,245. Apartment List reports a median of $1,076, down 2.1%, and calls Columbia the most affordable city in the Nashville metro. The gap between sources is largely methodology, since Apartment List uses a same-unit median. Underwrite from actual leases, not a data feed. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
DSCR files in markets like this one typically look the same. Single-family files arrive with coverage near the line, and the outcome turns on the appraisal and the insurance quote. Small-multifamily files clear more comfortably but hinge on the appraiser finding rent-supported comps. The cleaner files usually have the lease in hand, a fresh insurance quote, and an honest read on how much equity the appraisal will actually support.
Riverside, Downtown, and the Arts District
The older core is where multi-unit cash-out files come from. Downtown Columbia is anchored by the Maury County Courthouse and Main Street, and Rentometer notes historic neighborhoods such as St. Francis. Per Homes.com listings, the Arts District includes a 6-unit property within walking distance of The Mule House and the Columbia Arts Building. NashvillesMLS lists a 5-unit building, a duplex, and the Riverside Drive quadruplex, and a local builder’s page says converted Victorians are among the most common multi-unit types. No source gives neighborhood-level rents, so none appear here.
Supply is the constraint. Redfin’s multi-family page showed 8 multi-family units for sale in a month against 86 townhouses, and a Homes.com snapshot listed 12 multi-family homes priced from $224,500 to $1,400,000. That listing page is dated, so treat it as directional. Thin inventory cuts two ways. It makes new 2-4 unit purchases hard to find, which pushes owners of existing small multifamily toward refinancing instead. It also means few sold comps, so any multi-unit cash-out should get a rent-based appraisal and a comp check early.
A local brokerage page claims multifamily yields of 6-8%, but it gives no method or date. Skip that number. Lease-level rent is the only figure that belongs in a coverage calculation.
The Hampshire Pike Workforce Pocket
Near Columbia State Community College, demand is steady but modest. Columbia State sits on Hampshire Pike, and Data USA reports 5,712 students, 2,680 full-time and 3,032 part-time, across a nine-county service area. There is no four-year university in town, and the college hosts bachelor’s programs from other institutions, so this is staff and workforce housing more than a student play. Treat it as a rent-steady, low-ceiling submarket.
The retail corridor along Bear Creek Pike and Nashville Highway, near Columbia Mall, adds newer apartments and townhomes, and newer subdivisions like Oak Lake Estates and Sagewood Estates serve commuter households. Newer stock is the weakest cash-out fit. A builder-priced home rents like a house but appraises against new-construction comps, and coverage runs thin at higher list prices. Habersham is the upscale end and is more of an appreciation holding than a cash-flow one.
Hospital Jobs Versus the Plant Cycle
Tenant demand in Columbia rests on two employers with very different risk profiles. Hospital and insurance jobs are steadier than auto manufacturing, so rentals near Maury Regional Health and downtown carry the more defensive demand. The flagship Maury Regional Medical Center has 255 beds and more than 500 providers across 60+ specialties, and the system is one of the county’s largest employers. Tennessee Farm Bureau’s insurance headquarters in Columbia adds a white-collar base.
The plants are the swing factor. NewsChannel 5 reported that GM employs more than 5,000 people in the Spring Hill area, which a company executive called its largest US complex. That headcount is from a dated report, so treat it as scale, not a current count. Then came the layoffs. Fox17 reported a temporary layoff of 710 Ultium Cells employees, and Main Street Media of Tennessee reported that Maury County’s April unemployment of 6.1% was the highest in Tennessee. A local economic-development leader pointed to 4.5% the following month as evidence that the spike was temporary. Both figures come from local leaders’ comments, so check them against state labor data.
The risk is event-driven, not structural, but it shows up in lease renewals and tenant credit, and it plausibly explains part of the rent softness above. A cash-out lender may weigh single-employer concentration in the appraisal and the file. Before pulling equity, confirm that the plants have actually resumed production.
Sizing the Draw
Take the cash-out conservatively, because Columbia’s data does not support squeezing the last dollar. Picture an investor holding a duplex near downtown with a paid-down balance. At 75% LTV the coverage clears the line, but a 65% LTV leaves cushion if the appraisal comes in low or the insurance renews higher. The proceeds still fund the next down payment, and the file stays clean. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Contrast that with a single-family owner sitting near 1.0. That investor might consider the smaller draw, or a two-step plan: refinance the stronger asset and hold the thinner one. The equity-extraction mechanics apply the same way in any Tennessee city, and the investor refinance options cover rate-and-term paths for owners who want a lower carry instead of cash. For a side-by-side with bank underwriting, see the guide “Where DSCR and Conventional Diverge”. New to the structure? Start with Lendmire’s DSCR guide, and browse DSCR loans in Tennessee for statewide context.
Verify current local rental rules, taxes, and insurance with qualified local professionals before committing to any refinance.
Frequently Asked Questions
Does Columbia’s flat appreciation hurt a cash-out refinance?
It limits how much equity the market adds, but it does not block a refinance. Owners who bought at a discount, renovated, or paid down principal still hold equity that an appraisal can recognize. The draw is capped at 75% of appraised value, and slow appreciation makes the appraisal the number to test first.
Will a single-family rental in Columbia clear 1.00 coverage on a cash-out?
Often not at the citywide average value. Once full PITIA is counted, a 3BR rental at a value near $374,557 and a rent near $1,888, financed at 75% LTV, tends to land in a coverage band of roughly 0.84x to 0.91x. That band reflects a range of interest-rate scenarios, Tennessee’s comparatively low property taxes, and typical insurance costs. Lower cost bases, smaller draws, or a duplex can change the outcome, and some lenders review sub-1.00 files with compensating factors.
DSCR vs. conventional financing
Two common ways to finance an investment property in Columbia, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How does the GM and Ultium layoff affect a lender’s view?
It can raise questions about tenant stability and rent durability, especially for properties dependent on plant workers. Rentals near Maury Regional and downtown lean on steadier employers. Documented leases and a current rent history help the file regardless of where the plants stand.
How long must I own a Columbia property before pulling cash out?
Typically about six months from title recording, subject to lender guidelines. Recent purchases and heavy renovations may also face valuation questions, since the appraisal has to support the value you are borrowing against.
Is there enough multifamily inventory to reinvest cash-out proceeds locally?
Only barely. Redfin’s page showed 8 multi-family units for sale in a month, so many investors will need patience or a wider search. That makes a pre-approved plan for the proceeds worth having before the refinance, not after.
Where Columbia Goes From Here
The next 6-24 months hinge on the plants. If Spring Hill production holds steady and the 4.5% unemployment reading proves durable, rents should stabilize around current levels and the 21.0% new-build share should slowly get absorbed. In that case, well-located duplexes near downtown and Maury Regional will keep their coverage edge over single-family houses, and owners with older bases will keep holding the most usable equity. If the layoffs return, expect longer days on market and softer appraisals. The prudent call is modest draws on multi-unit assets now, not maximum ones.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. Lender review centers on the property’s rental income, not the borrower’s traditional personal-income documentation, which suits self-employed operators and portfolios beyond four financed properties. The firm was recognized as a top-ranked workplace in 2026 and a top-ranked workplace in 2025 by Scotsman Guide. Investors can reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
3. Data USA, Columbia State Community College
4. Fox17 (WZTV)
5. Zillow Home Values, Columbia TN
6. CommunityScale, Columbia TN
8. Zumper Rent Research, Columbia TN
9. Apartment List Rent Report, Columbia TN
10. Redfin’s multi-family page
11. Homes.com
12. Columbia State
15. Main Street Media of Tennessee
16. Scotsman Guide — Top Workplaces 2026
17. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Columbia, Tennessee: Riverside and Downtown Equity Extraction · Cash Out Refinance Investment Property in Loves Park, Illinois: The 2026 Refi Guide to Riverside Blvd · DSCR Cash Out Refinance in Loves Park, Illinois: The 2026 DSCR Refi Guide to Riverside Blvd
Guides: Investment Property Cash-Out Refinance in Columbia, TN · Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.