
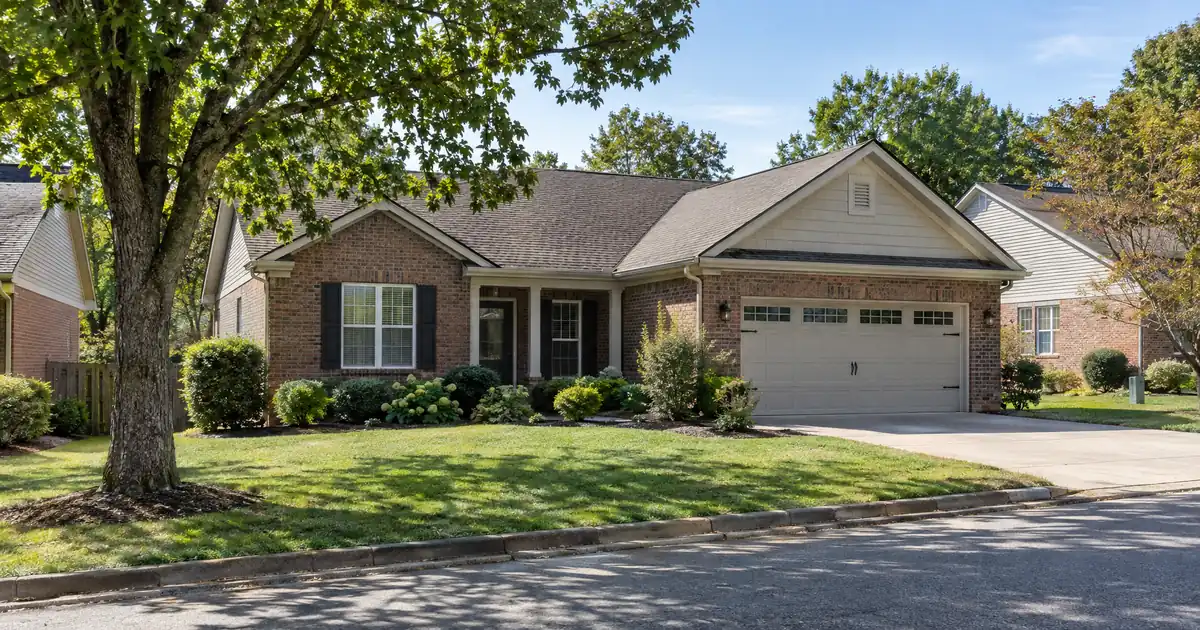
A six-unit building in Columbia’s Arts District, listed within walking distance of The Mule House, the Columbia Arts Building, and the library, shows where cash-out math works in this city. Per Homes.com’s multi-family listings, about a dozen multi-family properties were on the market, priced from $224,500 to $1,400,000. Stacked rent is the only reliable way to lift coverage in a market where single-family rents run well below 1% of price.
TL;DR: A DSCR cash-out refinance in Columbia, Tennessee is underwritten primarily on the property’s rental income measured against its full monthly obligation, with taxes and insurance included. The owner’s existing equity, not personal income, sets how much can come out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Columbia, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow puts the average Columbia home value near $374,557, up about 1.0% over the year.
- Single-family rent-to-price sits near 0.45%-0.50%, so equity extraction favors duplexes and small multifamily.
- Cash-out LTV tops out at 75%, with about 6 months of seasoning from title recording.
- Maury County’s labor market took a hit from Spring Hill plant layoffs, and appraisers may weigh it.
- Multi-family supply is thin, which makes comps the hardest part of a Columbia cash-out.
Columbia Market Snapshot
A quick read on the Columbia investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | 60% of rentals $1,001–$1,500 (RentCafe, Columbia TN) |
| University enrollment | 5,712 total (Data USA, Columbia State) |
| Employment | 710 employees (Fox17 (WZTV), Ultium layoffs) |
Where the Coverage Math Holds: Downtown, Arts District, and Riverside
The older core is the strongest cash-out submarket in Columbia. Pre-war and Victorian stock converted to multiple units can stack rent, and rent stacking is what pushes coverage above the 1.00x benchmark. Two caveats come first. No source in the research gives neighborhood-level prices or rents for Columbia, so the profiles below are qualitative. And the quality of a cash-out file here depends on actual leases, not marketing yields.
Downtown and the Arts District. Rentometer describes a historic downtown anchored by the Maury County Courthouse and Main Street, with older neighborhoods such as St. Francis nearby. Demand comes from hospital, county, and office employment within a short drive. For an owner who bought a small multi-unit property here and has held it past the seasoning window, appreciation plus rent growth is what creates refinanceable equity.
Riverside. Older bungalows and a renovated quadruplex on Riverside Drive appear in local brokerage listings. This is likely workforce housing near the medical center and downtown. It’s the more realistic pocket for single-family 3BR rentals at a lower basis, though price and rent for the submarket aren’t quantified in available data.
Hampshire Pike and the Columbia State corridor. Columbia State Community College enrolled 5,712 students per Data USA, split between 2,680 full-time and 3,032 part-time. There’s no four-year campus in the city, so student-rental demand is a minor driver. Staff and workforce tenants are the larger group.
Newer subdivisions. Skip these for cash-out purposes unless the numbers are pre-checked. Builder pricing in communities such as Reserve at Hickory Ridge and Hillcrest Village tends to set the ceiling for comparable resale homes, which squeezes both rent coverage and appraisal headroom.
The Single-Family Reality Check
Columbia single-family rentals at median pricing do not clear 1.00x at the 75% LTV cap. Rent is simply too low relative to price. Dividing Rentometer’s $1,888 three-bedroom average by Zillow’s $374,557 average value gives an approximate gross monthly yield of about 0.50%. Using Zillow Rental Manager’s $1,675 average rent, the figure drops to about 0.45%. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Run the numbers on a modeled $375,000 three-bedroom house, assuming $1,888 monthly rent and a standard 30-year loan. At 75% LTV, with taxes and insurance at Tennessee-average loads, coverage lands near 0.86x. At the Zillow rent figure, it slips into the high 0.7s. These are modeled assumptions, not quotes. Rents and prices come from the cited sources, but the debt service is the author’s illustration. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Sub-1.00 is not a dead end, but it changes the structure. Options a lender could review include a lower LTV, a sub-1.00 program, an interest-only structure, or a documented lease at a higher rent. Dialing the same house to roughly 60% LTV pushes the modeled coverage to about 1.0x including taxes and insurance. That means less cash out, not no cash out. Qualification stays subject to lender guidelines, credit approval, and property review.
Duplexes Change the Picture
Small multifamily is the best fit for equity extraction in Columbia. Take a hypothetical duplex valued at $380,000, with each side renting at the 2BR figure of $1,408 from Rentometer (assumed for modeling). Combined rent of $2,816 against full PITIA produces coverage near 1.25x at 75% LTV. Same price band as the single-family house, but the second unit covers the gap. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
DSCR files in markets like this one typically look like thin-comp deals with a mixed stock of property types. Appraisers lean on the few multi-unit sales available, lenders look hard at lease documentation, and the borrowers with the cleanest files already hold rent rolls with documented tenants. Files where an owner can show twelve months of rent deposits against a signed lease tend to move more smoothly through lender review than files built on projected rent. The owner who treats the lease file as seriously as the property tends to get a better look.
Redfin’s multi-family page showed 8 multi-family units for sale in Columbia in a recent month, against 86 townhouses. That’s directional rather than precise, but the signal is consistent: few 2-4 unit comps. The honest read is that Columbia duplex owners hold an asset that’s hard to replace, and the same scarcity makes valuation harder. Anyone planning a cash-out on a 2-4 unit property should line up rent-based appraisal comps early.
The stronger play might be a duplex over a single-family at the same price, but investors chasing appreciation could argue the other way. Single-family homes have more sold comps, which makes the appraisal cleaner. It’s a genuine toss-up, and coverage tips it toward the duplex.
The 75% Cap, Seasoning, and What Reserves Do
The cash-out ceiling is 75% LTV, and the equity available is not a guaranteed cash figure. It depends on the rent used for lender review, the full monthly obligation, reserves, and that 75% cap. Most files also require about 6 months of ownership, counted from title recording. Reserves typically run about 6 months of PITIA, rising to about 9 months on balances above $1,500,000. Credit tiers generally start at a 620 floor, and standard programs cover loan amounts up to $3,000,000 (subject to lender guidelines and the borrower’s scenario).
Consider how this plays out for an investor who bought a Downtown-area duplex and has held it past seasoning. If the property has appreciated even modestly (Zillow shows Columbia values up about 1.0% over the year), most of the available equity comes from the original purchase basis and any value-add work, not from market appreciation. A flat-to-up market means the cap, not momentum, controls the proceeds. Anyone expecting the market to do the lifting here will be disappointed.
For the full mechanics, see Lendmire’s page on the equity-extraction mechanics and the broader investor refinance options. For those new to the product, Lendmire’s DSCR guide explains how coverage is calculated.
Labor-market risk hit Columbia this year. Maury County’s unemployment hit 6.1% in April, the highest in Tennessee, driven largely by extended retooling layoffs at the GM and Ultium Cells plants in Spring Hill, per Main Street Media of Tennessee. The Maury Alliance president pointed to a 4.5% figure for May after the layoffs ended, though those numbers come from local leaders and should be checked against state labor data. The underlying event was a temporary layoff of 710 Ultium employees, per FOX 17, and GM said it expected cell production to resume by mid-2026.
That’s the risk in plain terms. Rents here have been soft: Apartment List shows a median of $1,076, down 2.1% year over year, and calls Columbia the most affordable city in the Nashville metro. Zumper shows house rents averaging $1,795. The sources disagree because they use different methods; Apartment List tracks same-unit medians. Soft rents compress coverage. An appraiser or lender may also weigh the concentration of local employment in one manufacturing cluster. The risk is event-driven rather than structural, but it’s live.
The Anchors That Steady Tenant Demand
Not all of Columbia’s demand rides on one plant. Maury Regional Health runs a 255-bed flagship hospital in Columbia with more than 500 providers across 60-plus specialties, and local economic-development sources describe it as a strong employer of over 2,000 staff. Farm Bureau Insurance of Tennessee is headquartered in Columbia as well. Healthcare and insurance-HQ jobs are less cyclical than auto manufacturing, so rentals near the medical center and downtown benefit from a steadier tenant pool.
GM remains the largest single anchor. NewsChannel 5 reported GM employed more than 5,000 people in the Spring Hill area, and a GM executive called it the company’s largest US complex. That’s 15 to 20 minutes from Columbia. It is the base of long-term rental demand and a concentration risk at once.
Per Census Bureau QuickFacts, Columbia’s population is 45,441 with a median age of 35.5. RentCafe puts the renter share at 36% of households, and 60% of rentals fall between $1,001 and $1,500 a month. Rents above that band need strong comps.
New Construction Is the Appraisal Wildcard
CommunityScale shows permits issued since 2020 account for 21.0% of Columbia’s housing stock. That’s a heavy new-build share, and it matters for cash-out. Builder pricing and incentives can pull down resale values and rents for comparable newer homes, so a cash-out appraisal may land below a purchase-price-plus-improvements expectation. Homes.com’s new-construction listings for Maury County include communities such as Bear Creek Overlook and Hillcrest Village, near Highway 31 and Pulaski Highway.
The practical response is conservative LTV and a wide comp radius. Owners of older Downtown, Arts District, and Riverside property are somewhat insulated, since new subdivisions compete on different terms. Owners of newer single-family homes are not.
Where Does the Extracted Equity Go?
The best use of proceeds in Columbia is acquiring more of what clears coverage: small multifamily at a lower basis. Single-family purchases at median prices push the next property toward sub-1.00 territory, so the cash-out only helps if the next deal’s rent-to-price ratio is better than the one it came from. That points to duplexes, older-core stock, and properties where rent can be documented.
Investors comparing paths can read how DSCR compares to conventional financing, especially for portfolios past the conventional limit. Lendmire’s page on DSCR loans in Tennessee covers the statewide picture. For a file review, reach the brokerage at 828-256-2183 or request a quote.
Verify current local rental rules, taxes, and insurance with qualified local professionals before committing to any structure.
Frequently Asked Questions
How much equity can a Columbia investor pull out of a rental?
The ceiling is 75% LTV on the property’s value, minus the existing balance. The actual figure depends on rent used for lender review, full monthly obligation, and reserves, so it is not a guaranteed cash amount. In Columbia, where single-family rents run about 0.45%-0.50% of price, lenders may land on a lower effective LTV than 75% to reach 1.00x. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Columbia, TN, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Will the GM and Ultium layoffs hurt a cash-out in Columbia?
They can matter, mostly through appraisal and lender caution rather than a hard bar. Maury County’s April unemployment spike to 6.1% traced back to Spring Hill plant retooling, and local leaders reported a rebound to 4.5% in May. Lenders may ask whether production has actually resumed, and documented, current leases carry more weight in that environment.
Can a Columbia duplex be refinanced when few comparable sales exist?
Yes, though valuation takes more care. Redfin shows only a handful of multi-family units listed in a recent month, so appraisers may widen the search radius or lean on rent-based valuation. Start the comp work before the application, and have lease agreements and rent deposit history ready.
Does a median-priced Columbia house clear 1.00x on a cash-out?
Usually not at the 75% cap. Modeled on a roughly $375,000 house at about $1,888 in rent, coverage including taxes and insurance lands below 1.00x. Lower LTV, a sub-1.00 program, interest-only structures, or stronger documented rent are the options a lender could review.
How long must an investor own a Columbia property before a cash-out?
About 6 months, measured from title recording. Owners who purchased recently and plan to renovate should plan the timeline around that seasoning window and document the improvements.
What the Next Two Years Likely Look Like
Columbia looks like a stabilizing market, not a boom. Values are roughly flat to slightly up, days on market have lengthened, and a heavy new-build pipeline is adding supply. If the Spring Hill plants hold production and the county’s unemployment stays near the May figure, rents should firm in the older core, where multi-unit stock is scarce and hospital and county employment carry demand. The most likely winners over the next 6-24 months are owners of documented Downtown, Arts District, and Riverside duplexes, while median-priced single-family rentals and newer-subdivision homes will keep running below 1.00x at the full 75% LTV cap. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s traditional personal-income documentation, is central to program review, which suits self-employed operators and portfolios beyond four financed properties. Scotsman Guide recognized Lendmire as a top-ranked workplace in 2026 and a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Homes.com, Columbia multi-family listings
2. Zillow, Columbia home values
3. RentCafe
4. Data USA
5. FOX 17
6. Rentometer, Columbia average rent
7. Columbia State Community College
8. Zillow Rental Manager, Columbia
10. Main Street Media of Tennessee, county unemployment
11. Apartment List, Columbia rent report
12. Zumper
14. NewsChannel 5
17. Homes.com’s new-construction listings
18. Scotsman Guide — Top Workplaces 2026
19. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Columbia, Tennessee: Tapping Riverside Equity · DSCR Cash Out Refinance in Loves Park, Illinois: The 2026 DSCR Refi Guide to Riverside Blvd · Cash Out Refinance Investment Property in Loves Park, Illinois: The 2026 Refi Guide to Riverside Blvd
Guides: Investment Property Cash-Out Refinance in Columbia, TN · Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.