
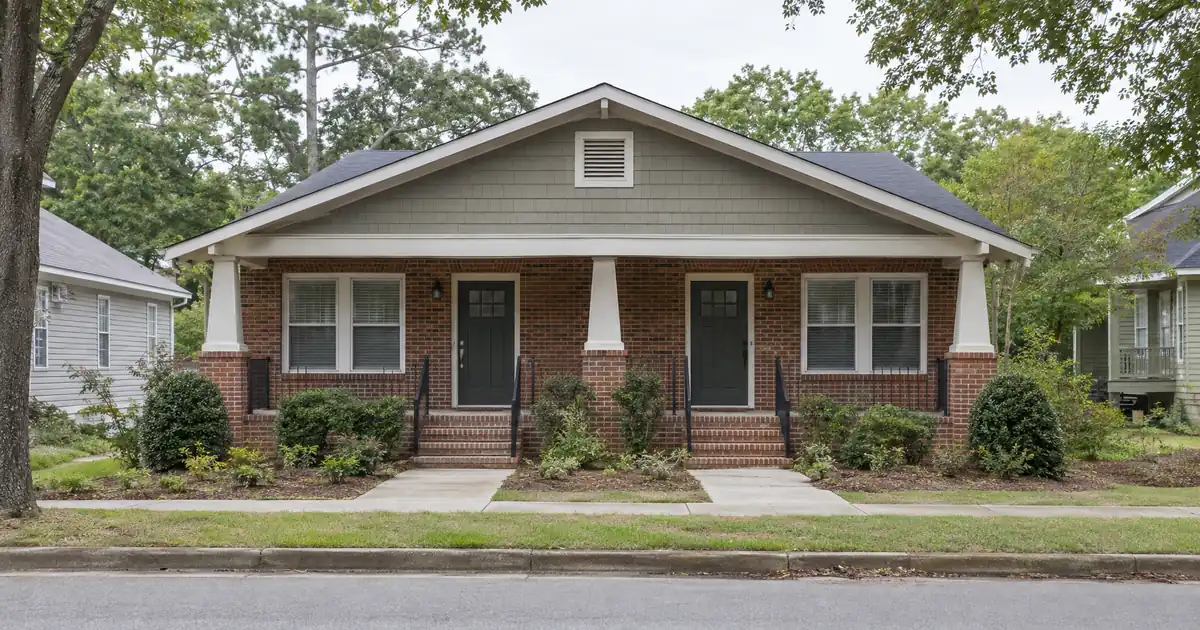
A rental in Florida Shores hits the DSCR math like this: a three-bedroom house bought near the city’s $311,000 median sale price and rented at roughly $2,050 a month, Zumper’s Florida Shores figure, then refinanced at the 75 percent cash-out ceiling. Run full PITIA with taxes and insurance included, and the coverage number lands right around 1.00. It’s a hair over at that rent and a hair under at Zillow’s $1,900 citywide average. That’s a modeled scenario, not a closed deal. It explains why equity extraction in Edgewater is a coverage story before it’s an appraisal story.
The Short Version: A DSCR cash-out refinance on an Edgewater, Florida rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds sized around a 75 percent LTV ceiling and roughly six months of ownership seasoning, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Edgewater, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family is 80.69 percent of housing units and large apartment complexes just 2.17 percent, per NeighborhoodScout.
- Redfin puts the median sale price at $311,000, down 1.2 percent year over year.
- Zillow’s average rent is $1,900, down $250 over the past year.
- Florida Shores duplexes are the cleanest route to stacked coverage.
Why Single-Family Coverage Runs Thin Here
Single-family rentals in Edgewater are the deepest pool of product and the weakest on coverage. At roughly $310,000 and $1,900 in rent, a 75 percent cash-out lands in the mid-0.9s once taxes and insurance are inside the number. Expect a sub-1.00 file, not a clean one.
Three data points frame the market. Redfin shows days on market stretching to 73 from 59 a year earlier. Zillow tags the rental market “COOL” and shows asking rents down $250 over the year. Movoto’s median list price runs higher at $349,900 with 156 days to sell. That’s a different measure from closed sales, but the direction is the same: slower.
A local agent guide pitches Edgewater gross yields of 7 to 9 percent. Treat that as one agent’s estimate, not a measured number. Gross yield also isn’t what a lender tests. The coverage ratio is rent divided by the full monthly obligation, and a house at this price band squeezes that quickly.
If the file comes in under 1.00, the options are lower leverage, stronger credit and reserves, or a lender willing to review sub-1.00 scenarios. Each has trade-offs in pricing and cash left in the deal. The guide “What Is a DSCR Loan” is worth reading before choosing which path to chase.
Florida Shores: Where Duplex Stacking Lives
Florida Shores, the large residential area west of US-1, is the best submarket in the city for income stacking, and it’s where nearly all the duplex and triplex inventory sits. Homes.com shows neighborhood listings from $234,000 to $516,000. Zumper’s neighborhood rent figure is about $2,050. Redfin counts about 12,744 residents and only 417 jobs in the area. It’s a bedroom community, so tenants commute out. That matters for demand, and it works in the investor’s favor since the commute destinations are in-county.
The product to hunt is a newer duplex, both sides three-bedroom and two-bath, around 1,358 square feet each, with garages and indoor laundry. Redfin has carried newer-build examples. An older Florida Shores duplex shows two-bedroom units under 1,000 square feet per side. Skip those for cash-out. Smaller, older units rent lower and appraise on thinner comps.
Edgewater-wide, Homes.com lists 11 multifamily properties across a wide range of asking prices. Small multifamily is scarce, which cuts both ways: low competition, but few comps for an appraiser.
Run the Numbers on a Newer Duplex
Model a duplex at $400,000, a placeholder inside that listing band rather than a sourced price. Assume each side rents at $1,600, which is Zumper’s two-bedroom average. Treat that as conservative for three-bedroom units. At 75 percent LTV with taxes and insurance in full PITIA, the coverage ratio comes out around 1.2. Run the same financing assumptions on a single $310,000 house at $1,900 and it sits in the mid-0.9s.
That gap is the article’s thesis. Two rent streams against one mortgage change the ratio far more than any appraisal bump. These are modeled assumptions for illustration, and actual figures depend on the property, the lender and the borrower.
Think about the lot-plus-build angle too. Listings advertise a multifamily lot with approved triplex plans included in the price. Those are listing claims, so confirm what’s entitled before counting on it. An investor who builds, stabilizes and then refinances is working from a very different basis than one buying a stabilized house at market.
Who Rents Here (and Why It Isn’t Tourism)
Edgewater’s tenant base is workforce, and its anchors are skilled trades and manufacturing. The City of Edgewater lists Boston Whaler, EdgeWater Power Boats, Everglades and SŌLACE Boats as based in town, and ParkTowne Industrial Center sits in one of Volusia County’s largest industrially zoned areas. Team Volusia EDC lists Boston Whaler at roughly 750 employees in Edgewater. County anchors are commutable by I-95 or US-1, including Halifax Health at about 3,197 and the AdventHealth system at about 5,510.
AdventHealth New Smyrna Beach is the nearest hospital. Northwest Lineman College runs a branch campus in town, though no enrollment figure was found. Edgewater isn’t a student market and not a resort one. Leases tied to in-county jobs aren’t exposed to tourism seasonality the way beach-town rentals are. Neighboring New Smyrna Beach leans tourism and second homes. Edgewater is the cash-flow-led side of that pair.
Census Reporter counts 23,627 residents. The city’s planned-development page cites Deering Park North at 6,600 housing units across 5,187 acres, a long-range pipeline over decades. It’s no near-term catalyst. Don’t underwrite a cash-out on it.
Skip the Riverfront for Cash-Out
Riverside Drive along the Indian River is pretty and wrong for DSCR cash-out. Homes.com puts waterfront sales between $1 million and $2 million, while Zumper’s Riverfront Estates rent figure is about $2,100. Rent barely moves from Florida Shores while price multiplies, so coverage collapses. Waterfront properties also carry flood-zone designations that can affect carrying costs. Verify current local rental rules, taxes and insurance with qualified local professionals before buying any property in the city.
Mobile homes are 12.16 percent of Edgewater’s housing units, but manufactured homes fall outside these DSCR programs entirely. If a candidate property is manufactured, that’s the end of the cash-out conversation.
Seasoning, Leverage and the Appraisal Problem
The constraint here isn’t the seasoning clock. It’s the appraisal. Redfin’s data shows fewer sales and longer marketing times, which means fewer and older comps. Redfin’s price per square foot is $202, up 2.8 percent even as the median slipped. That hints that smaller and newer product is holding value better than larger older homes. A newer Florida Shores duplex probably appraises more reliably than a 1950s waterfront cottage.
Here’s what a deal desk tends to see on files from markets structurally like this one: softening rents plus slowing sales. The cleaner files from a documentation standpoint pair a signed lease at market rent with a recent appraisal-supported value. The common friction point is an owner who underwrote the original purchase on peak asking rent and now faces lower rent used for lender review at refinance. Running both numbers before ordering the appraisal prevents surprises.
It’s a toss-up whether to refinance now or wait. The stronger play may be to refinance a duplex that already covers and hold off on single-family files until rents stabilize. Investors counting on appreciation to unlock equity could argue the other way, but with values flat to down, that’s a bet on a recovery nobody has documented. Lendmire’s Florida DSCR platform covers the state-level program picture.
Where the Proceeds Go
The point of a cash-out is the next deal, so it’s worth deciding where the capital lands before refinancing. In Edgewater the next deal is usually another stacked-unit property, and a rental-to-rental recycle only works if the new purchase covers on its own. For more on how each structure treats proceeds, an overview of investment property refinancing and the cash-out refinance options are good places to start. For a side-by-side view, compare the tradeoffs between conventional and DSCR loans. If a file is borderline, see how the DSCR math pencils or call 828-256-2183.
Frequently Asked Questions
What are the requirements for a cash-out refinance on an investment property in Edgewater, Florida?
Typically about six months of ownership from title recording, a 75 percent LTV ceiling, a credit score floor of 620 and reserves around six months of PITIA. The property also needs to cover its obligation at a 1.00 ratio or better on most programs. Manufactured homes are excluded, which matters here given their share of the local housing stock. Details vary by lender and borrower.
How do you qualify for a DSCR loan in Edgewater when single-family rents are soft?
Qualification turns on the ratio of rent to full PITIA. A single house at roughly $310,000 and $1,900 in rent sits near the mid-0.9s on modeled assumptions at 75 percent LTV, so it usually takes lower leverage or a lender that reviews sub-1.00 scenarios. A newer duplex with two rent streams may clear 1.00 more comfortably. Eligibility is subject to credit approval and property review.
Will softening values in Edgewater hurt a cash-out appraisal?
They can limit proceeds. Redfin shows the median down 1.2 percent and days on market at 73 versus 59 a year earlier, which leaves appraisers fewer fresh comps. Newer, smaller product tends to hold up better on price per square foot. Don’t underwrite a refinance on projected appreciation.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Edgewater, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How does DSCR lender review differ from a bank’s approach in Edgewater?
Lenders in the network review the property’s rental income against its monthly obligation rather than leaning on personal income documentation. That suits self-employed owners and LLC borrowers, subject to program eligibility.
Does Edgewater’s duplex supply support repeated cash-out refinancing?
Not at volume. Listings are thin, with 11 multifamily properties in the city, so plan around a single well-chosen duplex or a lot-plus-build instead of a pipeline. New-build activity and the Deering Park North pipeline may widen supply over time. Each refinance still needs to stand on its own coverage.
What to Watch Next Quarter
Three indicators decide whether Edgewater’s cash-out math improves or tightens:
- Days on market. Redfin’s 73-day figure is the one to track. If it keeps climbing past a year earlier’s 59, appraisal comps get thinner.
- Asking rents. Zillow shows $1,900 and Zumper about $2,000. A stabilizing line would help single-family coverage, and another drop would push it further under 1.00.
- New duplex listings in Florida Shores. More newer-build supply near the Homes.com price band would widen the pool of properties that cover on their own.
If rents stop sliding while duplex listings multiply, the case for equity extraction here strengthens. If days on market keep stretching, Edgewater stays a market where only the stacked-unit files pencil.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines. That works for self-employed investors, LLC operators and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Edgewater housing market
2. Zumper, Edgewater rent research
3. Zillow Rental Manager, Edgewater
4. NeighborhoodScout, Edgewater
6. coastalvolusiahomes.com — Best Neighborhoods Real Estate Investment Volusia County
7. Homes.com
8. Redfin — Florida Shores New Homes
9. Homes.com lists 11 multifamily properties
10. City of Edgewater, Discover Edgewater
11. Team Volusia EDC, Major Employers
12. AdventHealth New Smyrna Beach
13. Census Reporter — Edgewater FL
15. 2025
16. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Edgewater, Florida: How Duplex Rent Math Clears at 75% LTV · Cash Out Refinance Investment Property in Daytona Beach Shores, Florida: Can the Rent Carry the Loan Here? · DSCR Cash Out Refinance in Tamarac, Florida: Woodmont Equity and Condo Dues
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.