
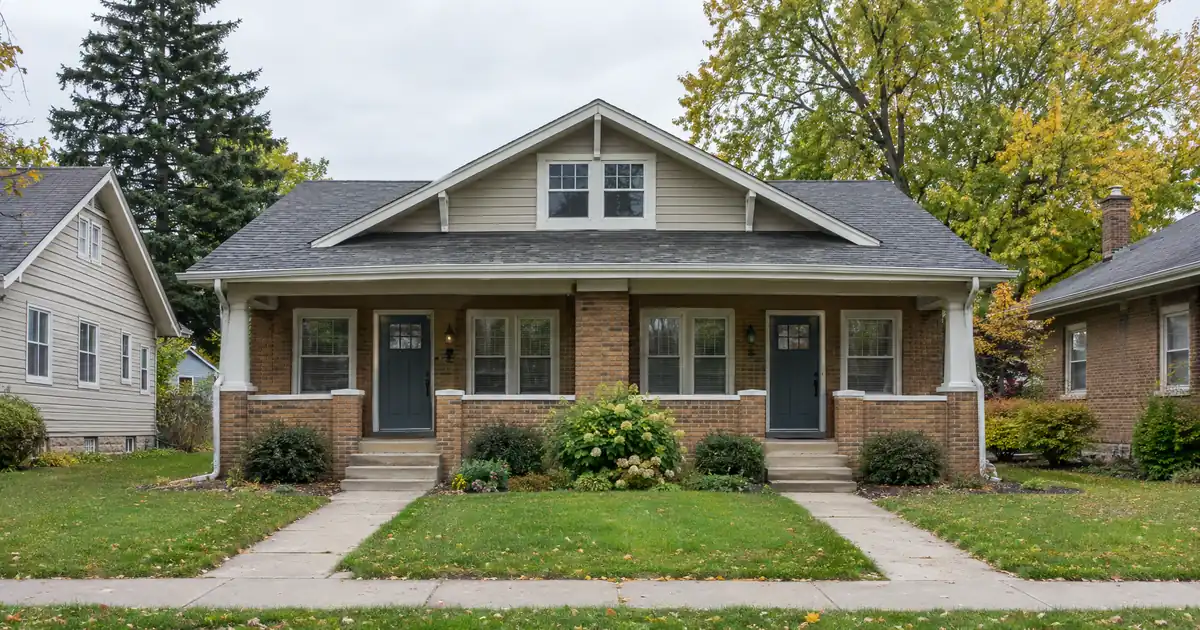
Downtown Menomonee Falls, the older core around Main Street and Appleton Avenue, is where a cash out refinance investment property plan gets interesting, and where it gets complicated. The village says downtown holds more than 140 businesses, with the river, Riverwalk, and Mill Pond within a few blocks. Older cores like this are where small multi-unit stock tends to sit, though that’s an inference, not a sourced fact. Two-to-four-unit buildings are scarce across the village, and scarcity changes how an investor should think about pulling equity out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Menomonee Falls, WI
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on a Menomonee Falls, Wisconsin rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the amount an owner can pull depends on rent coverage, reserves, and a leverage ceiling rather than on personal income alone.
- Single-family detached homes are 66.89 percent of housing units, so most cash-outs here are single-family files.
- Duplex-to-fourplex stock is only about 4 percent of units, which makes those buildings the scarce asset.
- At 75 percent LTV, rent coverage tends to limit proceeds before the leverage cap does.
- More than 500 senior and market-rate apartment units in the pipeline deserve a conservative rent assumption.
Downtown and East Main: Why Scarcity Is the Whole Story
The strongest equity-extraction candidate in this village is a small multi-unit building near the older core, if you can find one. Duplexes and converted small buildings make up roughly 4 percent of housing units per NeighborhoodScout, while large apartment complexes are 24.26 percent and row or attached homes 4.44 percent. There’s very little of the middle product.
The village backs reinvestment in older commercial districts, including Downtown and the East Main Street Corridor. For an owner already holding a small building there, that reinvestment can support appraised value. It doesn’t guarantee it.
One thing buyers confuse: a proposed ten-building duplex project on Custer Lane would add 20 units, but they’re sale-only duplex-style condos, and sewer limits capped the site at 20 or fewer. Each condo unit is individually titled. An investor who owns one gets one rentable unit, not a stacked two-unit income. The cap also shows how hard it is to add small-multifamily supply here, which supports the scarcity argument for true 2–4 unit buildings.
What the Rent Data Supports (and Doesn’t)
Rent estimates for Menomonee Falls range from roughly $1,300 to $1,800 on a blended basis, depending on the source, and the higher numbers come from apartment communities, not single-family rentals. Zumper shows an average of $1,617. RentCafe reports $1,790 on average, with $1,883 for two-bedrooms and $2,423 for three-bedrooms, but it only covers buildings with 50 or more units. At the low end, HUD’s Waukesha County fair market rent for a three-bedroom is $1,460, per Affordable Housing Hub. Treat that as a floor reference, not a forecast.
Here’s the catch. A lender’s rent schedule, not a listing portal, sets the coverage figure. Apartment asking rents flatter single-family comps. An investor who underwrites at the RentCafe three-bedroom figure and then sees an appraiser’s schedule come in lower has a different file than the one they planned.
Working DSCR brokers see a recurring pattern in suburban markets like this one: the owner models rent from apartment-community averages, the appraisal’s rent schedule lands lower for a single-family home or townhome, and the coverage ratio, not the LTV cap, ends up deciding how much equity comes out. Pulling comps for the specific property type before applying prevents most of that surprise.
Run the Numbers: Where 75 Percent Stops Being the Constraint
On a typical Menomonee Falls single-family rental, coverage runs thin at full leverage. That’s the central math of this market.
Zillow puts the typical home value at $371,794, up 1.6 percent over the past year. Redfin’s latest snapshot shows a higher median sale price of $426K, with about 42 days on market, per Redfin. That figure is dated and uses a different methodology, so the two shouldn’t be blended. This article uses the Zillow figure as its anchor.
Run the numbers on a modeled single-family rental valued near $372,000, with an assumed rent of $2,400. That rent is a modeled assumption, not a sourced market figure. At the 75 percent LTV ceiling for cash-out, and measuring rent against full PITIA (principal, interest, taxes, and insurance), coverage lands in the mid-0.9s. Move the same rent to a home near $440,000 and coverage drops to roughly 0.8x including taxes and insurance. Those are illustrative bands, not quotes.
Sub-1.00 doesn’t end the conversation, but it changes it. The standard benchmark for most programs is 1.00x, because rent covers the monthly obligation at that level. Several routes might apply to a file like this, each subject to lender guidelines, credit approval, and property review:
- Lower leverage. Taking less than the full 75 percent can bring coverage up, at the cost of less cash out.
- A sub-1.00 program. Select lenders review these, usually with stronger credit, more reserves, or both.
- Interest-only structuring. Some programs offer it, which improves coverage on paper.
The question worth asking first is whether the file should be forced at all. If the investor is stretching to hit a cash-out number on a property that sits well below 1.00x, the answer may be a smaller draw or waiting for rent growth. A sub-1.00 structure is defensible when there’s a clear appreciation story. It’s a weak choice when it’s the only way the numbers work.
| Factor | DSCR Cash-Out | Conventional Cash-Out |
|---|---|---|
| Qualifying basis | Rent vs. full PITIA | Personal income and DTI |
| Entity ownership | Often allowed, per program terms | Usually personal name |
| Financed-property count | Not typically limited | Caps apply |
| Best fit | LLC or multi-property investors | Single rental, strong W-2 |
If you hold one or two rentals personally and have strong traditional employment income, conventional may carry lower friction. As the portfolio grows or the income documentation gets messy, DSCR becomes the more practical path. The conventional-vs-DSCR tradeoffs are worth reading before choosing.
Seasoning and the Equity You Actually Have
The cash-out thesis here depends less on this year’s appreciation and more on how long the investor has owned. Zillow’s one-year gain is modest at 1.6 percent. The longer arc is different: a broker blog citing Census QuickFacts puts the median home value at $390,164, up from $291,500 earlier in the decade, about 34 percent (Walters Realty, which should be checked against the primary sources before relying on it). Three sources, three medians, because they measure different things. The pattern still holds: owners who bought several years ago are sitting on real equity.
On the program side, cash-out typically requires about 6 months of ownership, measured from title recording, and a 75 percent LTV ceiling. Typical credit tiers run from a 620 floor up through 660, 680, and 700, and reserves are generally about 6 months of PITIA (about 9 months above $1,500,000). Loan amounts go up to $3,000,000 on standard programs, with smaller balances routed through select lenders. Eligibility varies by borrower, property, and lender.
A caveat on the older housing stock: nearly half of village homes were built before 1980, per the same blog’s reading of the village plan. Older stock can carry deferred capex that weighs on appraisal condition and eats into reserves. Equity on paper and equity after repairs aren’t the same number.
The owner-occupied rate is 74 percent. The renter pool, 26 percent or 4,265 households per RentCafe, is real but bounded.
Who Rents Here? The Employment Base
Tenant demand follows paychecks, and this village has a solid base of them. The Waukesha County Center for Growth economic profile counts nine industrial and office parks covering over 1,300 acres. It lists Kohl’s Corporation and Froedtert & the Medical College of Wisconsin in the 1,000-or-more employee band. Harley-Davidson, Arandell, Leonardo DRS, Wacker Neuson, Bradley, Alto-Shaam, and Enerpac each sit in the 500–999 band. These are size bands, not exact headcounts, and the profile is dated.
Froedtert Menomonee Falls Hospital adds an academic medical center with inpatient services and 24/7 emergency care. Retail corridors along Highway Q, Appleton Avenue, and Pilgrim Road near the Highway 41/45 interchange add service-sector demand. No colleges sit in the village, so student rental isn’t part of the thesis here. This is a workforce rental market.
The village population is 40,945 by the state’s 2025 estimate, the most populous village in Wisconsin. Demand drivers here are manufacturing, corporate headquarters, and healthcare. Kohl’s has faced retail pressure, and current headquarters staffing isn’t verified here. That’s a concentration risk worth weighing.
The Supply Question: What’s Coming Online
More than 500 new apartment units are arriving, and that matters for rent comps. The village’s current projects page lists a nearly complete 224-unit senior apartment building with 32 senior townhomes on Lisbon Road. It also lists a care facility with 60 community-based residential units and 56 residential care apartments. Separately, Dickson Hollow Phase 2 adds 118 senior units, and two mixed-use buildings near Good Hope Road and Appleton Avenue add 173 market-rate apartments.
Most of that is age-restricted, so pressure on family single-family rentals is probably limited (that’s an inference). The 173 market-rate units are different. Concessions on new Class A apartments can soften asking rents for nearby townhome and condo comps. The honest approach is to underwrite on a conservative rent figure.
New for-sale construction runs the other direction. Zillow’s new-home listings in the area start around $450,000 for townhome-type product and climb well above $900,000 for single-family plans. At those prices, rents would need to be very high to cover the debt. Newer product is owner-occupant and appreciation-led. The older, lower-priced existing homes and the townhome tier are where cash flow is more likely to hold up.
Where Does the Cash Go?
The redeployment plan decides whether a cash-out makes sense. Pulling equity to buy another rental in a market where the coverage math works is a straightforward argument. Pulling equity into a market where the new property wouldn’t cover its own debt either is a different decision, worth stress-testing before committing.
For a Menomonee Falls owner, one honest option is to take a smaller draw than the maximum, using how the cash-out works to size a figure that leaves coverage near 1.00x. Another is a rate-and-term refinance, which suits the case when the goal is restructuring the debt rather than extracting cash. Which one fits depends on the portfolio. This is a genuine toss-up for owners with one property: a smaller cash-out keeps coverage healthy, but a larger one funds the next acquisition sooner. Flip the answer if the next purchase is itself thin on coverage.
Wisconsin investors can see Lendmire’s Wisconsin DSCR loan programs for the broader state picture. Anyone who wants to test a specific file can get a rental-income loan quote or call 828-256-2183. Before committing capital, verify current local rental rules, taxes, and insurance with qualified local professionals.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Menomonee Falls, WI, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What a Local Appraiser Would Tell You
Here’s the plain version. Menomonee Falls is a single-family and townhome rental market with a deep employer base, modest near-term appreciation, and rents that don’t stretch as far against $370,000-plus values as investors expect. Equity is real for owners who bought years ago, but the coverage ratio, not the 75 percent cap, usually decides how much comes out. The scarce duplexes and fourplexes near downtown are the best-positioned holds, and they’re the ones to keep.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Menomonee Falls?
Qualification centers on the property’s rent compared with its full monthly obligation, with 1.00x as the common benchmark. Lenders also review credit (typically a 620 floor), about 6 months of reserves, and roughly 6 months of ownership measured from title recording. Because Menomonee Falls rents often run thin against $370,000-plus values, the coverage ratio may limit proceeds before the 75 percent LTV ceiling does. All of this is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Menomonee Falls, Wisconsin?
Typical guidance includes a 620 minimum credit score, with pricing and leverage improving at higher tiers like 660, 680, and 700, plus reserves of about 6 months of PITIA. Cash-out is capped at 75 percent LTV, and loan amounts go up to $3,000,000 on standard programs. A rent schedule from the appraisal usually sets the rent used for lender review, so listing-site averages don’t decide it. Details vary by borrower, property, and lender.
Why do Menomonee Falls cash-out proceeds often come in below what the 75 percent cap implies?
Rent coverage usually binds first. Home values near $372,000 against rents the appraisal may support in the $2,000s produce coverage near or below 1.00x at full leverage, including taxes and insurance. When that happens, a lender may reduce the loan amount, and the investor can consider lower leverage, a sub-1.00 program, or interest-only structuring, each subject to lender review and approval.
Can I cash out on a sale-only duplex condo unit as if it were two rentals?
No. Individually titled condo units are single units, so each produces one rent, not two. The ten-building duplex project proposed on Custer Lane is sale-only, which means a buyer’s income is one unit’s rent. True duplexes owned as one parcel are a different product, and they’re rare in this village.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C., with DSCR eligibility generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. menomoneefalls.gov — Partners
2. NeighborhoodScout — Menomonee Falls Real Estate
3. including Downtown and the East Main Street Corridor
4. BizTimes, New Condo Development Planned for Menomonee Falls
5. Zumper
6. RentCafe, Menomonee Falls Rent Trends
8. Zillow — Home Values Menomonee Falls WI
9. Redfin
10. Walters Realty
11. Waukesha County Center for Growth, Village Economic Profile
12. Froedtert Menomonee Falls Hospital
13. Village of Menomonee Falls, Demographics
14. Village of Menomonee Falls, Current Development Projects
15. Yahoo Finance — 7 Developments Slated 2025 Completion
16. Zillow’s new-home listings
17. a 2025 Scotsman Guide Top Mortgage Workplace
18. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Menomonee Falls, Wisconsin: The 2026 DSCR Refi Guide to Main Street · DSCR Cash Out Refinance in Appleton, Wisconsin: The 2026 DSCR Guide to College Avenue Rentals · DSCR Cash Out Refinance in Fond Du Lac, Wisconsin: The 2026 DSCR Financing Guide to Main Street
Guides: Investment Property Cash-Out Refinance in Wisconsin
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.