
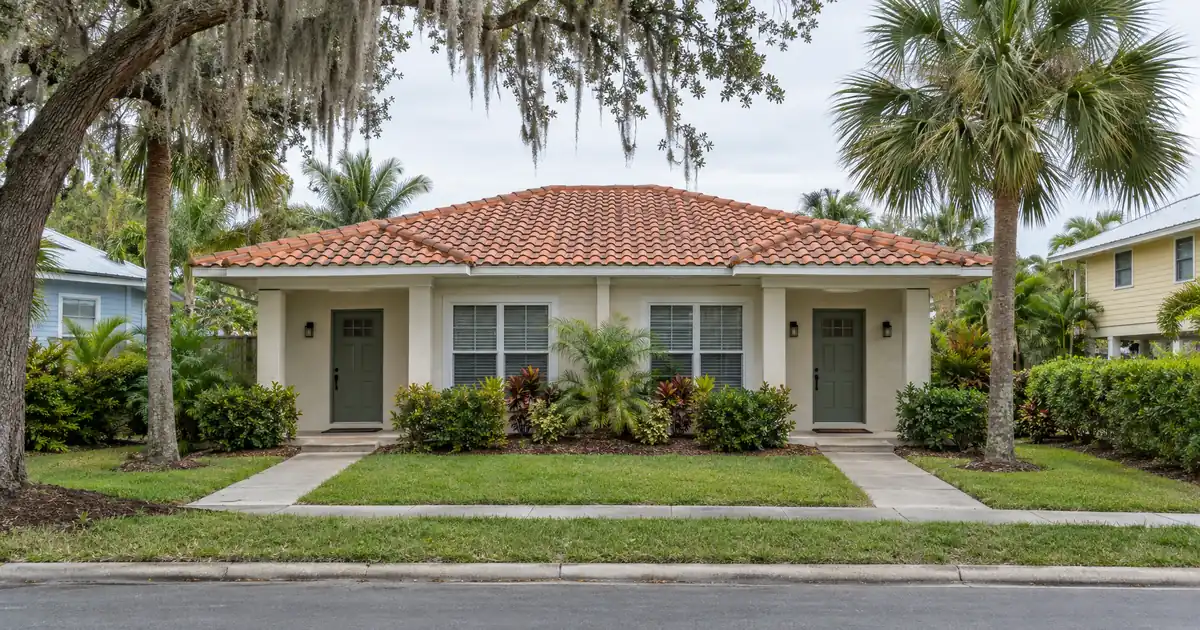
The Miami metro posted a multifamily vacancy rate of 6.6 percent, the lowest among the largest South Region metros, according to Miami Realtors. That figure frames the question for any cash out refinance investment property in Tamiami, Florida: the tenants are there, but does the coverage math let an owner pull equity without over-leveraging the rent? Tamiami is an unincorporated Miami-Dade community with a thin, tight rental base, a pile of appreciation, and cash flow that lags it.
At a Glance: A DSCR cash-out refinance on a Tamiami, Florida rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds limited by a 75 percent loan-to-value ceiling and roughly six months of seasoning from title recording, all subject to lender guidelines and property review.
DSCR Cash-Out Calculator
Run the cash-out numbers in Tamiami, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Rental vacancy is low, per Census-sourced housing data.
- Median sale price has climbed over the past year, per Redfin.
- Detached single-family rentals model below 1.00 coverage. Small attached multi-unit product clears it.
- A meaningful share of local housing is row houses or attached homes, per NeighborhoodScout.
Tamiami Market Snapshot
A quick read on the Tamiami investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $748,097 median price (NeighborhoodScout – Tamiami) |
| Typical rents | $3,174 avg (NeighborhoodScout – Tamiami) |
| University enrollment | Mdcps 40,000+ employees/350,000 students (Clearpoint HCO – Top Miami) |
| Population | 54,212 population (Wikipedia – Tamiami, Florida) |
| Employment | +10,608 private jobs Dec 2024-Dec 2025 (Miami Realtors – Miami-Dade) |
| Vacancy | 2.2% (Wikipedia – Tamiami, Florida) |
Appreciation Is Running Ahead of Rent
Equity is building faster than income here, and that tension decides how much to pull out. Redfin’s read on Tamiami shows the median sale price climbing over the past year, with homes selling faster than they did a year earlier. NeighborhoodScout’s separate read lands higher, reflecting a different methodology.
Next door, the pattern sharpens. Sweetwater values rose 12.66 percent year over year while average rents fell 5 percent, per Foreclosure.com and Zumper. The FHFA index for the Miami-Kendall division shows about 4.37 percent annual appreciation and roughly 77.61 percent cumulative gains over five years, as summarized by a local market analyst.
The mechanical point: a 6.8 percent appraisal gain lifts the 75 percent ceiling by the same 6.8 percent. The cash-out is the gap between that ceiling and the existing payoff. But the same ceiling gets tested by the rent used for lender review, and rent is the weak leg.
Why Detached Single-Family Struggles on Coverage
Detached single-family rentals in Tamiami typically model under 1.00 on a cash-out, even at conservative leverage. NeighborhoodScout’s average Tamiami rent of $3,174 against a $748,097 median works out to a monthly gross yield near 0.42 percent. In Sweetwater, a median value of $857,492 against $2,290 median rent is under 0.3 percent a month.
Run the numbers on a hypothetical $660,000 rental at the $3,174 average rent (modeled assumptions, not a listing). Coverage including taxes and insurance lands around 0.75x at 75 percent LTV. It improves to roughly 0.85x at 60 percent LTV and still sits below the 1.00 benchmark.
A 1.00x baseline is common because rent covers the full payment at that level. Some lenders review lower ratios, but those files usually bring stronger compensating factors, reduced leverage, or different pricing. If a detached rental sits here, the structures a lender might review include a sub-1.00 program, interest-only restructuring, or a smaller cash-out. Each is subject to credit approval, reserves, and property review.
Here’s the catch. Reaching for sub-1.00 on every Tamiami SFR suggests the property type may be the issue, not the loan program.
The Row-House Case (and Where It Pencils)
Attached multi-unit product is where coverage works. About 38.0 percent of the residential stock in Tamiami is row houses and attached homes, and 96.1 percent was built between 1970 and 1999. That is a consistent-vintage inventory, and an investor holding a duplex or triplex stacks several rents against one mortgage.
Consider a modeled scenario: a three-unit attached property valued at $900,000, with each unit renting at the Sweetwater apartment average of $1,987 from Zumper. Both the value and the rent stack are assumptions. Including taxes and insurance, coverage looks like this:
| Structure | LTV | Modeled coverage |
|---|---|---|
| Detached SFR at $660K | 75 percent | About 0.75x |
| Detached SFR at $660K | 60 percent | About 0.85x |
| Three-unit attached at $900K | 75 percent | Just above 1.0x |
| Three-unit attached at $900K | 65 percent | Low 1.1s |
The three-unit file clears at the ceiling but without much cushion. Dropping to 65 percent LTV buys meaningful breathing room. This is a genuine toss-up for owners: pull the maximum and sit near 1.0x, or leave equity in and keep a buffer against a vacancy or a repricing of taxes and insurance.
DSCR files in markets like this one typically look like a split between two types. Attached and multi-unit properties tend to come in near the 1.00 line at maximum leverage and improve sharply with a modest LTV trim. Detached high-value properties tend to need a reduced cash-out just to get rent and debt service into the same conversation. Borrowers who order rent comps and confirm full PITIA before choosing a cash-out amount usually avoid re-cutting the file. The cash-out qualification details cover how the pieces fit together.
Condos and townhomes are a moderate fit. Redfin-sourced inventory data shows a large stock of each on the market, but HOA and condo-project review adds another layer of lender scrutiny.
Six Months, 75 Percent, and What Else Gets Checked
Three program parameters drive most Tamiami cash-out files, and all are typical guidance rather than guarantees.
- Seasoning: roughly six months of ownership, measured from title recording.
- LTV ceiling: 75 percent for cash-out, which is lower than the purchase cap.
- Coverage: a 1.00 benchmark on rent used for lender review against PITIA, with credit tiers starting at a 620 floor and about six months of reserves on most files.
Equity available depends on rent used for lender review, PITIA, reserves, and that ceiling. It is not a fixed cash figure. Loan size can reach up to $3,000,000 on standard programs, which comfortably covers every Tamiami price point in the research. The refinance pathway for investor properties outlines the steps, and the guide “What Is a DSCR Loan” explains how coverage is calculated from monthly rent divided by the full monthly obligation.
If the property sits in an LLC, the structure works subject to lender program eligibility.
DSCR vs. conventional financing
Two common ways to finance an investment property in Tamiami, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The Tenant Base: FIU, Hospitals, and a Bed Shortfall
The demand story here is institutional, not seasonal. Florida International University’s Modesto A. Maidique Campus spans 342 acres along Tamiami Trail in West Miami-Dade. FIU’s final enrollment reached 55,673 students, per Miami Today. FIU News reports roughly 10,000 students living on campus or within walking distance, and a waitlist for university housing even as 820 affiliated beds come online.
Supply is tightening from the other side too. WLRN reports that four University Apartments buildings are slated for demolition to make room for a $160 million medical education complex. Third-party student housing listings name Tamiami as a primary off-campus FIU neighborhood, alongside Sweetwater and Westchester.
Healthcare adds a second layer. Baptist Health South Florida runs West Kendall Baptist Hospital, with 203 private rooms and an FIU family medicine residency, just south of Tamiami. HCA Florida Kendall Hospital adds 417 beds. Shift-based workers, residents, and university staff make a durable tenant pool, and Miami-Dade added 10,608 private jobs over a recent 12-month stretch, per Miami Realtors.
Rent data supports it. Miami-Dade asking rents rose 1.5 percent to $2,660 while stabilized occupancy held at 95.4 percent, per the Miami Realtors rental report. County figures are a proxy, not a Tamiami series. Sweetwater’s 5 percent rent dip is a reminder that nearby pockets can move differently.
Pockets Worth Pricing
The named submarkets are International Gardens, Tamiami Lakes, Sweetwater Groves, Southern Estates, and Sweetwater Estates. No verified per-neighborhood price or rent series exists for them, so the useful read is qualitative.
- Tamiami Lakes matches the row-house density finding, which makes it the most natural place to look for duplex and triplex income stacking.
- International Gardens is an established resale pocket, better suited to detached rentals where a reduced cash-out may be the trade.
- Sweetwater Groves and Sweetwater Estates sit adjacent to the FIU-proximate workforce and student demand.
- Southern Estates leans workforce single-family, so expect the detached-SFR coverage profile above.
Pull live rent comps before choosing a cash-out amount. Metro figures will not stand in for a specific block.
What the Proceeds Are For
A cash-out here funds the next purchase or improves the current one. Redeploying into another attached multi-unit in the same corridor keeps coverage workable at current pricing. Sending proceeds into a market where the rent-to-value math is thinner than Tamiami’s is a different decision, and worth stress-testing first. How DSCR compares to conventional matters mostly at the portfolio level: investors with several financed properties or entity-held title often find conventional options narrowing. For more on local programs, see Florida DSCR investor loans.
Investors who want to see how the math lands on a specific property can get a DSCR quote or call Lendmire at 828-256-2183. Verify current Miami-Dade rental rules, taxes, and insurance with qualified local professionals before committing to a number.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Tamiami, Florida?
Qualification centers on the property’s rent against its full monthly obligation, with a 1.00 benchmark on most files. Lenders typically also look at credit (a 620 floor, with better tiers at 660, 680, and 700), about six months of reserves, and roughly six months of seasoning. A maximum 75 percent LTV caps the cash-out. Final eligibility depends on lender guidelines and property review.
What are the requirements for an investment property loan in Tamiami, Florida?
Expect a rental property that is not a manufactured home, log home, or barndominium, since those fall outside these programs. Lenders review rent used for program review, PITIA, credit, and reserves. Loan sizes run up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network.
Does FIU enrollment really support rents around Tamiami?
It supports demand, though not a specific rent number. With 55,673 students, about 10,000 of them on campus or within walking distance, and a continued on-campus housing shortfall, a large student and staff pool competes for nearby rentals. No verified Tamiami-level rent series exists, so comps matter.
Can a detached single-family rental in Tamiami clear 1.00 coverage on a cash-out?
Usually not at today’s price levels. Modeled coverage including taxes and insurance stays below 1.00 even at 60 percent LTV. A lender may review sub-1.00 programs, interest-only structures, or a smaller cash-out, but each is subject to credit approval and property review.
Two Paths Forward
Tamiami owners face a real fork. One path is to pull the full 75 percent on an attached multi-unit, put the proceeds into the next corridor deal, and accept coverage near 1.0x with little margin if vacancy ticks up. The other is to take a smaller cash-out around 65 percent, keep a cushion in low-1.1 territory, and deploy less capital more safely. Either way, the FIU renter pipeline and a 2.2 percent rental vacancy give both paths a foundation. Only one of them leaves room for a bad year.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. Eligibility review centers on the property’s rental income rather than the borrower’s traditional personal-income documentation, which suits self-employed operators and portfolios beyond four financed properties. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and was a top-ranked workplace in 2025.
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Tamiami, Florida: The 2026 DSCR Financing Guide to Tamiami Trail · DSCR Cash Out Refinance in South Miami, Florida: The 2026 DSCR Financing Guide to Sunset Drive · DSCR Cash Out Refinance in Miami Lakes, Florida: The 2026 DSCR Financing Guide to Main Street
Guides: Investment Property Cash-Out Refinance in Florida
References
2. Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis
3. Census-sourced housing data
4. Redfin
7. Wikipedia – Tamiami, Florida
8. Miami Realtors – Miami-Dade
10. Zumper
11. as summarized by a local market analyst
12. Florida International University’s Modesto A. Maidique Campus
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.