
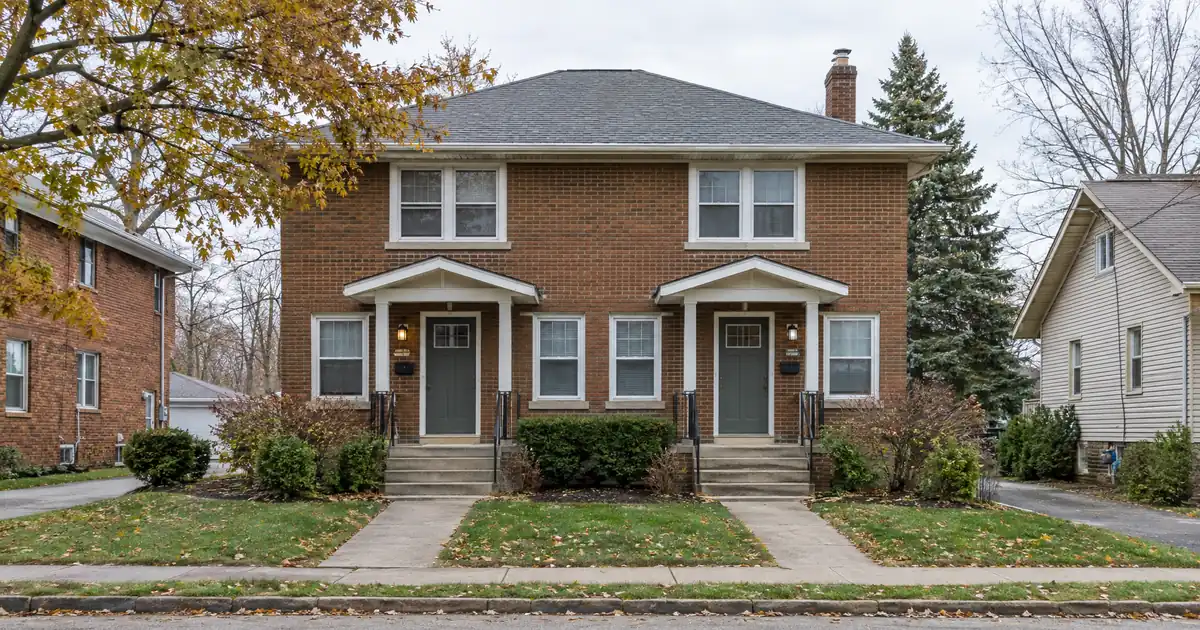
Over the next 6 to 18 months, the number to watch in Twinsburg is rent, not price. Redfin shows median sale prices up 5.4 percent year over year at a median near $335K, while Apartments.com’s CoStar-based trend data has rents up only 2 percent. Equity is building faster than income. That gap decides how much a cash-out refinance on a Twinsburg rental can actually return.
Lendmire, a non-QM mortgage broker (NMLS# 2371349), looks at this market with some skepticism. Lendmire helps arrange DSCR financing for Twinsburg, Ohio investors as part of a broader non-QM footprint reaching 41 markets, including D.C. The honest read is that the appraisal will rarely be the constraint here; rental coverage is far more likely to be the limiting factor.
DSCR Cash-Out Calculator
Run the cash-out numbers in Twinsburg, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A cash-out refinance on a Twinsburg, Ohio rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file has to show coverage around the standard 1.00 benchmark once the 75 percent LTV ceiling, roughly six months of title seasoning, and reserves are applied, subject to lender guidelines.
- Redfin’s median sale price sits near $335K, up 5.4 percent year over year.
- Redfin’s average rent of $1,549 leaves median-priced houses short of 1.00 coverage.
- Only 51 homes sold in May versus 70 a year earlier, so comps are thin.
- Cleveland Clinic and the Cornerstone Business Park logistics cluster anchor tenant demand.
Where the Equity Is Coming From
Twinsburg is an appreciation market. Pricing is the reason an investor would refinance here at all.
Redfin’s market page shows the $335K median, up 5.4 percent, with homes selling after 13 days on the market versus 23 a year earlier. Redfin’s city page shows a higher headline, $359,429, up 12.4 percent, because it uses a different window and method. Zillow’s home value page reads closer to 2.2 percent growth. Three sources, three growth rates. Quote a range and underwrite to the low end.
The ownership base matters too. Per City-Data’s Census-derived figures, Twinsburg has about 19,504 residents and an estimated median household income near $96,618. It’s an owner-occupied, single-family-heavy suburb. Investor-held houses are a small slice, which keeps supply tight and supports values. It also means few rental comps, which becomes a problem in the rent section below.
The Coverage Problem, Stated Plainly
Run the arithmetic on a median-priced house and the cash-out math breaks. On the portal figures, monthly rent-to-price lands around 0.36 to 0.42 percent, a gross yield of roughly 4.3 to 5.1 percent. That’s the research’s own arithmetic, built from portal data pulled at different dates.
Rent sources conflict, and the spread is wide:
| Source | Rent figure | Caveat |
|---|---|---|
| Redfin | $1,549 average | All unit types |
| Apartments.com | $1,287 two-bedroom | Apartment-heavy |
| ApartmentFinder | $1,415 two-bedroom | Listing-based |
| Zumper | $2,168 median | Skews to houses; down 9 percent |
Now a modeled scenario, using assumptions rather than sourced facts. Picture an investor holding a house valued near the $335K median, seeking a 75 percent LTV cash-out, with $1,549 in monthly rent. Divide that rent by full PITIA (principal, interest, taxes, and insurance at Ohio-typical levels) and coverage comes out roughly in the 0.65 to 0.75 range. Rent would need to rise something like 35 to 45 percent to reach 1.00. Only the house-skewed Zumper median gets near the benchmark, and a 9 percent annual decline in that series is no comfort.
So what does a sub-1.00 file do? Lenders may review a lower-leverage cash-out, a sub-1.00 program with compensating factors such as strong credit and reserves, or an interest-only structure that lowers the debt-service denominator. Each trades away proceeds, pricing, or flexibility, and eligibility stays subject to lender guidelines, credit approval, and property review. This is why Lendmire’s primer on DSCR loans stresses the ratio first and the appraisal second.
Lower-basis properties clear more easily. Any investor who bought below today’s median and carries a modest balance faces a very different coverage picture than someone refinancing at current values.
The Glenwood Corridor: Competing Supply, Not a Buy Zone
Glenwood Pointe, a garden-style apartment community, and Glenwood Square, a 55+ community, anchor the Glenwood corridor. That’s institutional supply competing directly with a small landlord’s rent. It isn’t a place to buy, and it caps what a nearby house can credibly ask unless the house wins on garage, yard, and square footage.
RentCafe puts the apartment stock at about 37 years old on average, with 20 percent built since 2000 and the stock mostly low-rise garden-style. Older competition cuts both ways. Tenants will pay up for newer or better-finished houses, which helps a renovated rental. But the same older stock keeps the floor on apartment rents low. One listing site calls Twinsburg’s vacancy “low.” No reliable source backs that up, so treat it as unverified.
The property-type picture is lopsided. City-Data shows a mean value of roughly $235,899 for 2-unit structures, but the sample is thin. Duplex stock is scarce, and any multifamily comp needs local MLS or broker verification. For most investors, the realistic DSCR-eligible product is a single-family house, townhome, or condo.
Who Actually Rents Here
Employment anchors the demand, though not at big-city scale. The Cleveland Clinic’s Twinsburg Family Health and Surgery Center occupies 80 acres off Darrow Road with a 24-hour emergency department. The Cornerstone Business Park, built on the former Chrysler stamping site, now holds an Amazon fulfillment center plus FedEx and O’Reilly Auto Parts warehouses. Crain’s Cleveland estimated nearly 4,600 Amazon FTEs across its North Randall, Euclid, and Twinsburg facilities, a multi-site figure that shouldn’t be credited to Twinsburg alone.
The city sits roughly halfway between Cleveland and Akron, with I-480, I-271, and the Ohio Turnpike nearby. Rental demand pulls from logistics, warehouse, and healthcare workers, plus amenity-driven renters near Township Square, a three-acre downtown greenspace, and the Darrow Road retail corridor. The city’s own filings list a Central Twinsburg redevelopment. Tenant demand is steady. It isn’t spectacular.
The city also hosts Twins Days, and Spectrum News reported more than 2,000 sets of twins at the latest edition. It’s a distinctive local draw. It isn’t an underwriting input.
What Does the Lender Review on a Twinsburg Cash-Out?
Terms here are typical guidance, not commitments, and every file is subject to lender guidelines.
Typical cash-out parameters run like this: a 75 percent LTV ceiling, about six months of ownership measured from title recording, 1.00 as the standard DSCR benchmark, a credit floor near 620 with better tiers at 660, 680, and 700, and reserves of about six months of PITIA. Equity extracted is a function of rent used for lender review, PITIA, reserves, and the LTV cap. It’s never a guaranteed figure. Loan amounts on standard programs reach up to $3,000,000, though that’s irrelevant at Twinsburg price points.
The data suggests a pricing gap matters more than any parameter. Cash-out proceeds in Twinsburg will be capped by coverage, not appraised value. A house can appraise comfortably and still return little cash if rent can’t carry the new balance.
Thin comps compound that. Fewer than 60 closings a month means a post-rehab refinance appraisal may lean on a small comp set. Ask about each lender’s comp radius and lookback before ordering anything.
Practitioner view: in suburban Ohio markets with this profile, the common friction point on cash-out files is the gap between a house’s appraised value and its documented rent. The cleaner files tend to arrive with a signed lease, a rent comp set that includes houses rather than apartments, and a clear seasoning timeline. Files that lean on a portal’s average rent often need rework once the lender reviews it. Lendmire’s deal desk tends to see that pattern repeatedly.
For structure details, see the cash-out refinance details. The side-by-side comparison shows when a conventional refinance beats DSCR. Investors should also verify current local rental rules, taxes, and insurance with qualified local professionals before underwriting. Anyone ready to test a specific property can get a rental-income loan quote or call 828-256-2183.
Where Do the Proceeds Actually Go?
Twinsburg’s pitch is stability, not yield. Zillow’s listing page puts Twinsburg’s average value at $318,379, against Northfield at $267,527, Streetsboro at $247,383, Bedford at $140,306, and Maple Heights at $112,505. Those are different Zillow metrics than the $364,841 on the home-values page, so use them only as a relative comparison.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Twinsburg, OH, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The comparison points to a recycling strategy: hold the appreciating Twinsburg asset, extract equity within the LTV cap, and deploy proceeds into lower-basis properties in the same commute shed, where rent-to-price runs higher. The catch is that none of those markets has sourced rent data in this review. Verify rents there before assuming the yield is better. (Cheap doesn’t mean it cash flows.)
The stronger play might be a smaller extraction. Taking less cash at lower leverage can lift coverage past 1.00 and cut reserve pressure, though investors chasing maximum proceeds could argue the other way. For statewide context, see Lendmire’s Ohio DSCR financing page.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Twinsburg?
Qualification centers on the property’s rent against its full monthly obligation, with a 1.00 benchmark as the common baseline. Lenders also review credit tiers (a 620 floor is typical), reserves near six months of PITIA, roughly six months of seasoning, and the 75 percent LTV ceiling. In Twinsburg, rent documentation on houses is the usual sticking point. Approval remains subject to lender guidelines.
What are the requirements for an investment property cash-out refinance in Twinsburg, Ohio?
Expect a rental property such as a 1-4 unit, condo, or townhome, with manufactured and log homes outside these programs. Typical requirements include about six months of title seasoning, a 75 percent maximum LTV, a lease or rent appraisal, and reserves. Eligibility varies by borrower, property, and loan scenario, and nothing here is a commitment to lend.
Is Twinsburg a cash-flow market or an appreciation market?
It leans toward appreciation. Prices have been rising faster than rents, and rent-to-price runs thin on median-priced houses. A refinance thesis should rest on equity growth and conservative rent underwriting, not on expecting rents to close the coverage gap.
Why can a Twinsburg refinance appraisal be harder to support?
Sales volume is thin. Redfin reports 51 homes sold in May versus 70 a year earlier, which leaves a small comp set for any post-renovation appraisal. Ask lenders how far back and how wide they search before you order the appraisal.
What loan-amount ranges may DSCR lenders review for Twinsburg rental properties?
Lendmire arranges DSCR investor loans. Standard programs generally cover balances up to $3,000,000, while smaller balances route through select lenders in the network. Final terms depend on program review.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. Lenders evaluate DSCR loans on rental income rather than personal income, subject to lender guidelines, which suits LLC-owned portfolios (subject to program eligibility), self-employed investors, and operators scaling past conventional loan caps. The firm was recognized by Scotsman Guide in 2025 and as a 2026 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Twinsburg housing market
2. Apartments.com: Twinsburg rent trends
3. Redfin: Twinsburg rental market
4. Redfin: Twinsburg city page
5. Zillow: Twinsburg home values
6. RentCafe: Twinsburg apartments
7. Cleveland Clinic: Twinsburg Family Health and Surgery Center
8. Crain’s Cleveland: Northeast Ohio’s largest employers
9. City of Twinsburg Annual Information Filing
11. Zillow: Twinsburg new homes and nearby values
12. Scotsman Guide Top Workplaces 2025
13. Scotsman Guide Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Ashland, Ohio: A 2026 DSCR Guide to Pulling Equity From Ashland Rentals · Cash Out Refinance Investment Property in Dublin, Ohio: The 2026 DSCR Guide to Bridge Park · Cash Out Refinance Investment Property in Gahanna, Ohio: Pulling Equity in a Flat Creekside Market
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.