Cash-out Refinance For College Tuition: What Changes And What Lenders Ask
Cash-Out Refinance For College Tuition — Not directly. A lender does not underwrite the tuition bill.

Cash-Out Refinance articles from Lendmire: how-to guides, requirements and eligibility checklists, cost and timeline questions, and side-by-side comparisons for borrowers and investors. Start with the Cash-Out Refinance program page or browse the Cash-Out Refinance Guide Library.
Cash-Out Refinance For College Tuition — Not directly. A lender does not underwrite the tuition bill.
Cash-Out Refinance Vs Selling The Home — It depends on whether you want to stay.
Low Appraisal Rental Refinance Options — It depends on what the refinance was supposed to do.
Cash-Out Refinance To Pay Off A Second Lien — Usually, yes, and the label depends on how the second lien was used.
Expect full underwriting on credit, income, assets and debt-to-income ratio. Program details are subject to lender guidelines and full file review.
Some programs let net proceeds count and some require separately held, seasoned funds.
Before the switch, the file runs on lease rent or market rent.
Across the wholesale network, the loan is made to the LLC and a member signs a personal guaranty.
Airbnb Cash-Out Refinance Low DSCR — Sometimes, but it is a narrow lane. Standard short-term rental programs start at 1.00 coverage.
Airbnb Vacation Rental Cash-Out Refinance — Usually, yes, if the property has real hosting history and the numbers cover the new payment.
Your best summer doesn’t set your income.
Short-Term Rental Cash-Out Refinance Documentation — It depends on how long the property has operated as a nightly rental.
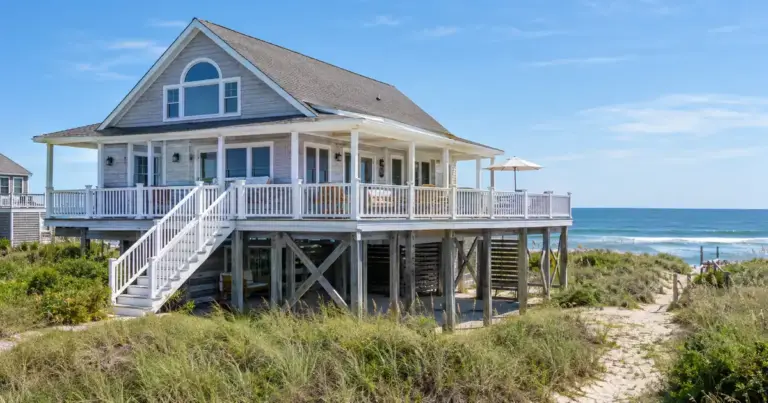
The file qualifies primarily on property-level rental income covering the payment, subject to lender guidelines.
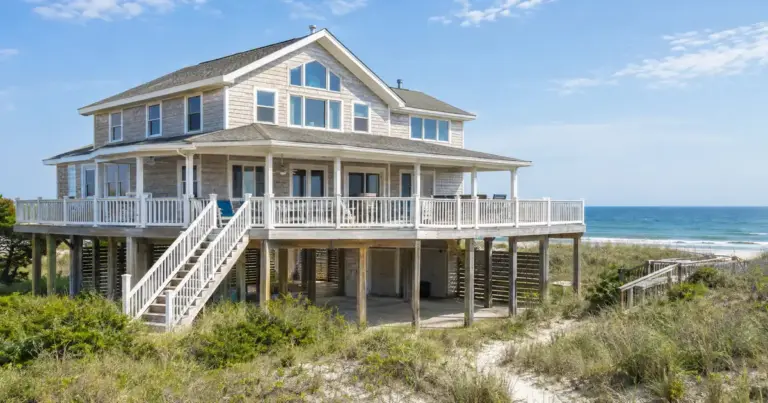
The market data report is typically an AirDNA-style projection, and it works only when the program counts it.
Whether it does depends on the value the lender recognizes, the seasoning window, and rent coverage.