Jumbo DSCR Loan Requirements For A Non-warrantable Condo Rental
Everything below explains how that review actually works, where it breaks down, and what an investor should expect on a real file.

Everything below explains how that review actually works, where it breaks down, and what an investor should expect on a real file.
Below that line, an investor still has room; above $3,000,000, cash-out disappears from the table entirely on most programs.
What changes at higher balances is leverage, credit score, and appraisal count — not the reserve-months multiplier itself.
Jumbo DSCR Rental Loan Always Trigger — No.
The LLC has to be properly formed and in good standing by closing day, not by application day.
Above roughly $2 million, leverage steps down and documentation load steps up: two appraisals, tighter credit, and case-by-case review past $4 million.
DSCR lenders don’t care about that classification.
Investors buying or refinancing a short-term rental often assume vesting choice changes their loan terms. It mostly doesn’t.
Lenders discount gross short-term rental revenue, usually to 80% of documented income, before it ever enters the coverage-ratio math.
The underwriting still runs through a person, not the entity.
Above that size, the file typically has to lean on the appraiser’s long-term rent analysis instead of actual booking history.
How The Experienced-investor Rule Shapes A Vacation Rental DSCR Loan — Yes, your track record as a landlord changes the loan.
An LLC protects your other assets if someone sues over the rental itself. Most retirees think they’re choosing one or the other.
Above $4 million, most files move from a published rate sheet into case-by-case underwriting. That’s the short version.
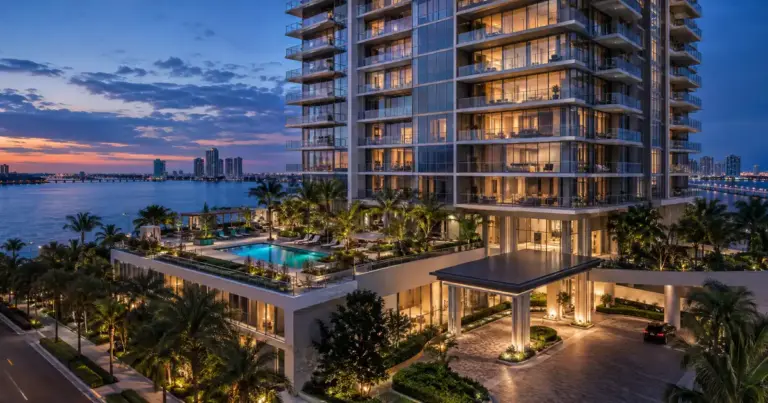
DSCR underwriting looks at whether the unit’s rent covers its monthly obligation, not at the condo project’s warrantability status.