DSCR Vs Bank Statement When Business Expenses Shrink Income
DSCR loans ignore personal income entirely and qualify on the property’s rent.

DSCR loans ignore personal income entirely and qualify on the property’s rent.
Amortizing DSCR loans cost more per month but chip away at principal from day one, building equity a retiree can lean on later.
An individual DSCR loan finances one property at a time, qualifying on that property’s rent alone.
Interest-only frees up monthly cash flow and can lift your coverage ratio, which helps if you’re deploying proceeds into several properties at once.
Neither choice changes how the loan qualifies — that runs on the property’s rent either way.
An LLC gives liability isolation and is the more common choice for portfolio investors; personal-name vesting is simpler and skips entity paperwork.
Neither product is automatically “better” — the right one depends on whether the property or the person is doing the qualifying.
What changes is liability separation, tax reporting, and how the file gets documented at closing.
Bank statement loans qualify the borrower’s deposit history, which fits self-employed cash flow, not distributions, dividends, or Social Security.
A bank statement loan looks at your deposits, but it still counts your existing debt against you.
Seasoning is a title-based test, not an income test.
The lender still asks a simple question: does the property’s income cover the payment?
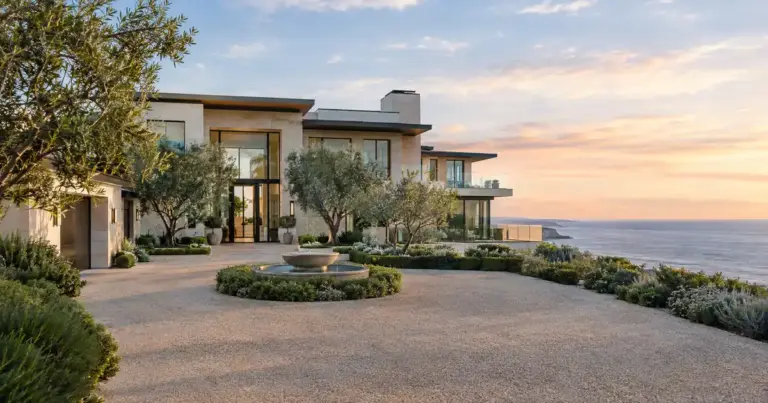
Luxury Rental DSCR Loans In La Jolla — These loans qualify a high-value rental property on its own rent, not on the owner’s tax returns.
Coverage, property type, and local rental rules each shape how much leverage a lender will actually offer.
DSCR programs step into that gap, sizing loans up to $10,000,000 with leverage that steps down as the loan gets bigger.