Can You HELOC A Rental Property?
Expect a lower combined loan-to-value ceiling, a higher credit floor, and a maximum line size well below what a primary-residence HELOC can reach.

Expect a lower combined loan-to-value ceiling, a higher credit floor, and a maximum line size well below what a primary-residence HELOC can reach.
The right fit depends on occupancy, how the property is titled, and how much equity a borrower wants to pull without touching an existing first mortgage.
That acquisition loan is usually a DSCR loan, sized to the rental’s own income rather than your personal finances.
Each path gets underwritten on a different set of rules. A line against a primary home leans on personal credit and income.
Xcan You Invest In Real Property By Taking A HELOC?
Can You Refinance A Rental Home — Yes, a rental property can be refinanced, but the rules differ from a primary home.
Can I Do A HELOC On An Investment Property — Yes, but it’s a narrower door than the one you’d use on your own house.
A property financed as a primary residence can’t just start collecting rent while the original mortgage stays in place unaddressed.
One test checks how much the appraised value supports. The other checks whether the rent covers the new payment.
Can I Take Out A HELOC On An Investment Property — Yes, but it’s a narrower product than the HELOC most people know from their own home.
One track runs on your personal income and debt, the same way a home loan on your primary residence works.
On a DSCR loan, the answer runs through appraised value, loan-to-value limits, seasoning time, and a rent-to-payment ratio — not a paycheck or a tax return.
Home equity loans on investment properties are a financing option that landlords and investors sometimes use to access equity for additional purchases
You need six months of title ownership, a separate 12-month clock on the loan being paid off, and leverage that sits below what a primary residence gets.
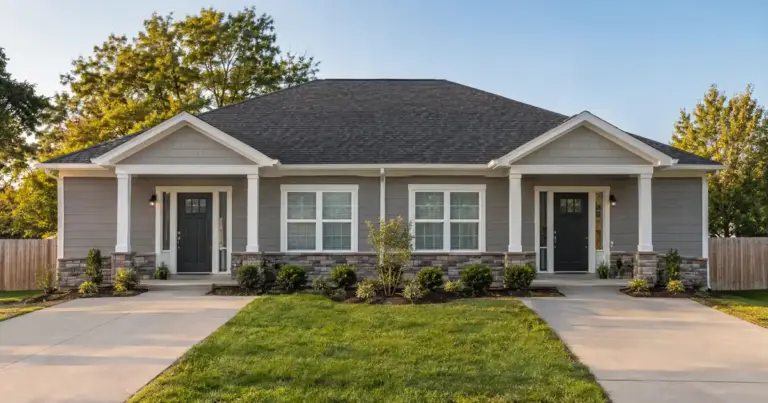
Can You Refinance An Investment Duplex Property — Yes.