What Is A Private Money Loan?
The lender is underwriting the deal and the collateral, not the borrower’s paycheck. That’s the short version.

The lender is underwriting the deal and the collateral, not the borrower’s paycheck. That’s the short version.
That’s the short version. The rest of this comes down to mechanics, who this actually works for, and where the risk sits.
Terms typically run 6-18 months, payments are interest-only, and the loan comes due in one balloon payment when you sell or refinance.
Big banks routinely decline lines on non-owner-occupied property regardless of how strong the file looks, which is the real gap these programs fill.
How To Qualify For A Hard Money Loan — Qualification runs on the deal, not the borrower’s paycheck.
I Do A Cash Out Refinance And Then Rent My House Out — Yes, this happens all the time, and it isn’t fraud by default.
HELOC From Primary Deducted From Rental Income From Investment — The answer splits into two separate tracks.
This guide walks through the mechanics, the qualification standards, and where the standard rulebook actually breaks down.
Underwriting centers on the property, the renovation plan, and the after-repair value — not your tax returns.
What changes isn’t the unit itself, it’s the building around it. A single-family house has one owner, one title, one set of liens.
Terms run 6-18 months, interest-only, with no prepayment penalty.
Underwriting looks at purchase price, rehab scope, and after-repair value first, and the borrower’s file second.
A standalone HELOC underwrites your personal credit and income. A DSCR cash-out refinance underwrites the property’s rent.
– The investment-property equity line caps at 70% CLTV and a $500,000 program ceiling, regardless of whether the borrower’s credit sits at 700 or 720.
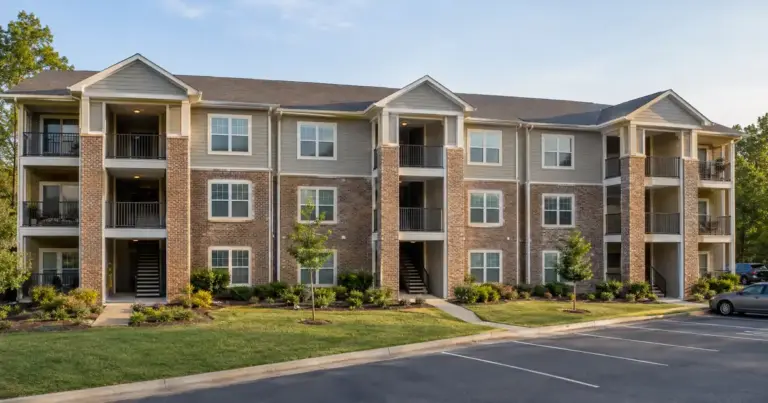
It exists because five-plus unit buildings get appraised and underwritten differently than a duplex or fourplex the moment they cross that unit-count line.