What Is The Difference Between ADR And Monthly Market Rent?
Monthly market rent is an appraiser’s opinion of what a property would lease for on a standard monthly lease, built from comparable closed leases.

Monthly market rent is an appraiser’s opinion of what a property would lease for on a standard monthly lease, built from comparable closed leases.
Underwriters use that figure, not the investor’s pro forma and not always the signed lease, to calculate the debt-service-coverage ratio on a DSCR loan.
Two separate clocks control your timeline: how long you’ve held title, and how much real booking history the property has generated.
Condotel Loan Requirements Explained — Condotels don’t qualify for agency or government-insured financing at all — Fannie Mae, Freddie
Every DSCR loan, Airbnb or not, runs on the same basic question: does the property’s income cover its own payment?
Turnkey buys certainty and a faster path to bookings.
DSCR loans work the opposite way: they qualify on the property’s rental income and carry no occupancy requirement at all.
An LLC earns its extra paperwork once liability exposure, multiple owners, or a growing portfolio enter the picture.
Rate assumptions belong in the calculator, and the article should discuss coverage qualitatively.
DSCR is the tool for the property that already earns, or can document, income strong enough to cover its own payment.
That makes it a real path for investors whose booking history is thin or whose projected income won’t clear a standard coverage floor.
The mechanics below walk through exactly how that math gets built, file by file.
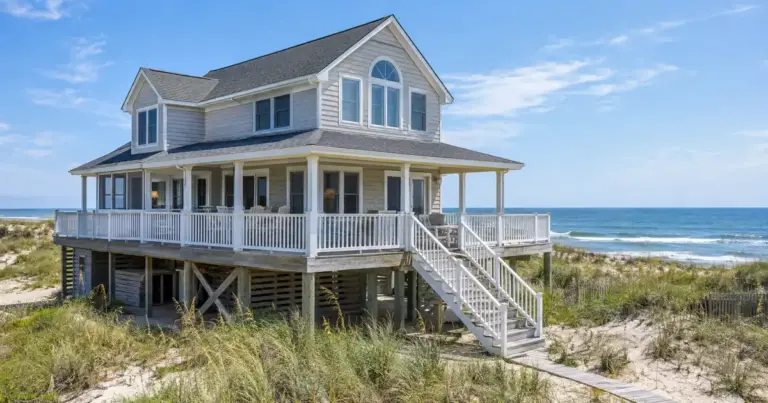
– Beach rentals typically qualify on a DSCR loan, which compares the property’s rent to its full monthly obligation rather than your personal income.
Seasonal Rental Markets And DSCR Qualification — Lenders don’t qualify a seasonal or short-term rental off its best month.
The lender looks at whether the projected income covers the monthly obligation, not whether the borrower’s paycheck does.