What Changes On A Jumbo DSCR Rental Loan File At $2M?
Cash-out gets capped or disappears depending on the exact balance.

Cash-out gets capped or disappears depending on the exact balance.
Pick based on the property, not the price tag. Both products sit outside the world of Fannie Mae and Freddie Mac. Neither follows a published agency grid.
Reserve requirements hold steady at six months of PITIA on the subject property regardless of size.
None of it is automatic — it runs through underwriting property by property.
Amortizing fits someone who wants the loan balance shrinking from day one and doesn’t want to think about a reset.
A portfolio loan qualifies you on your whole financial picture, held by the lender that made it rather than sold off.
That pooling can rescue a thin-margin triple-decker that would fail standalone underwriting.
The loan qualifies on the properties’ income, not the borrower’s tax returns, subject to lender guidelines.
Lenders add up rent and debt payments across the whole group and test one blended coverage number.
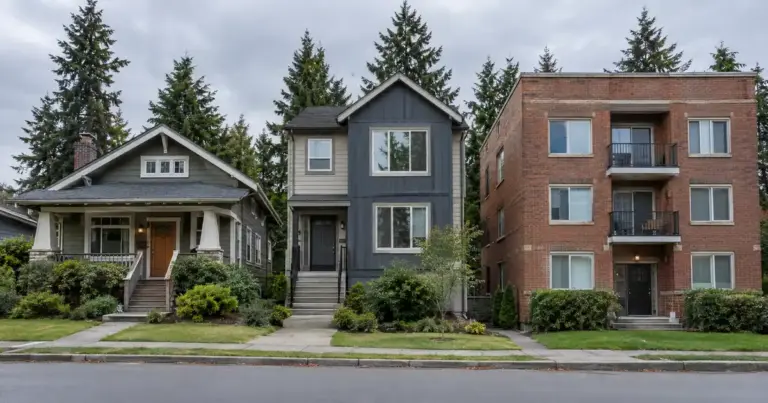
Underwriting sums the rent and the payment across the whole group and tests one blended ratio, not each property alone.
Lenders in Lendmire’s wholesale network size these from $150,000 up to $10,000,000, with leverage stepping down as the balance grows.
Every property still gets its own appraisal and rent number, but they’re cross-collateralized under a single note.
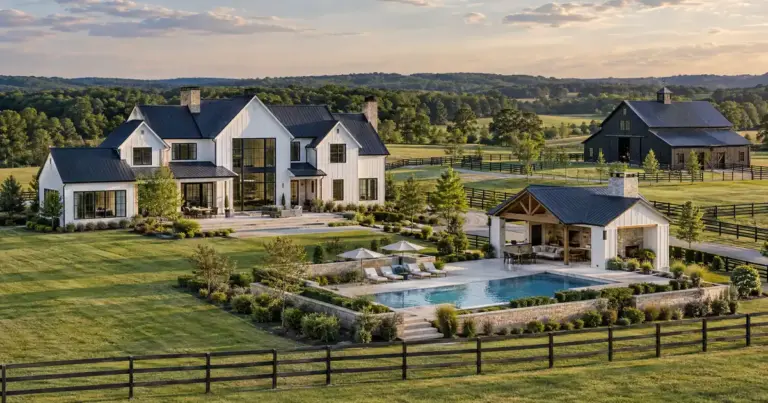
Leverage steps down as loan size climbs, and cross-collateralization is the tradeoff that makes the consolidation possible.
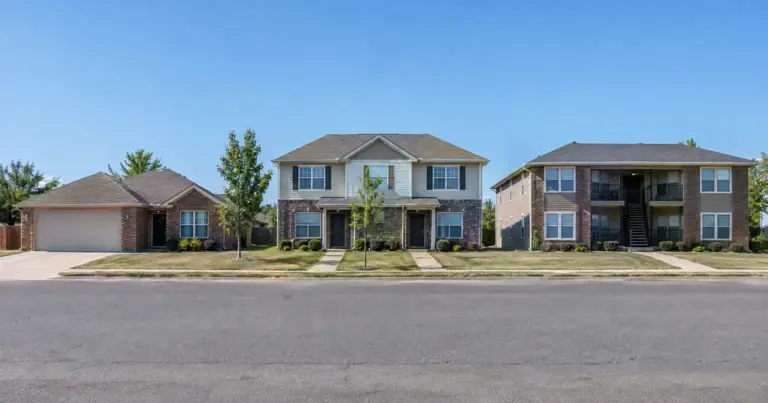
Qualification still runs primarily on property-level rental income covering the payment, subject to lender guidelines, not personal tax returns.
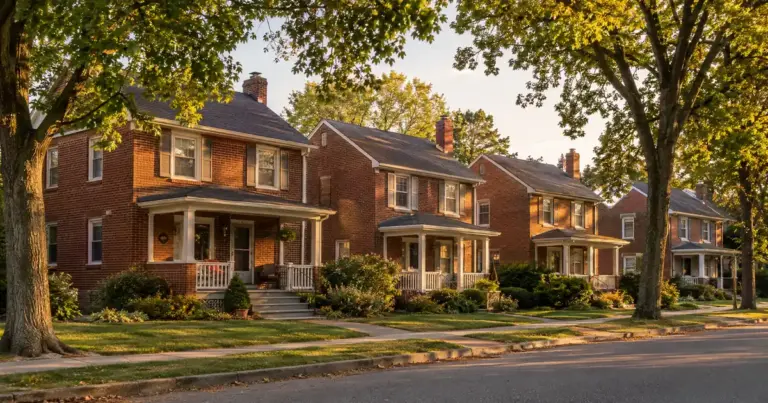
Rents from a strong duplex can offset a weaker rowhouse, which is the entire appeal.