Super Jumbo DSCR Loans In Cherry Hills Village
Leverage, credit floors, and reserve requirements all tighten together as the loan size climbs.

Leverage, credit floors, and reserve requirements all tighten together as the loan size climbs.
Coverage of 1.00 or better earns full leverage; below that, select programs still work but at reduced leverage.
Which lane applies, and how it gets discounted, decides the leverage an investor gets on a mountain-town luxury property.
A ratio at or above 1.00 means the rent covers the payment on paper. 1007 rent schedule: an appraisal form built for long-term lease comps.
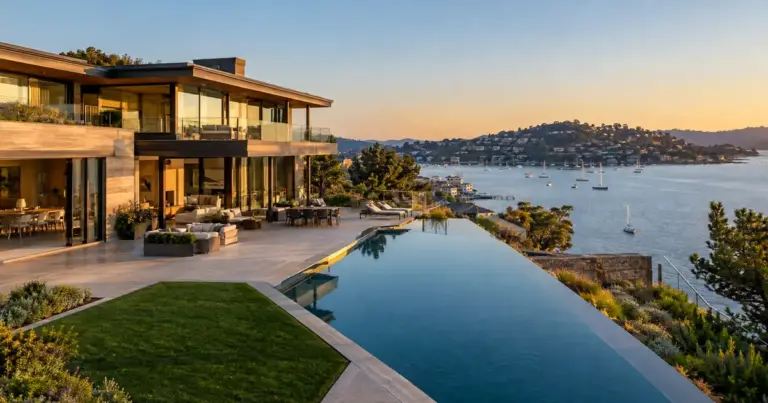
Super Jumbo DSCR Loans In Tiburon — These loans qualify on the rental income the property produces, not the investor’s tax returns.
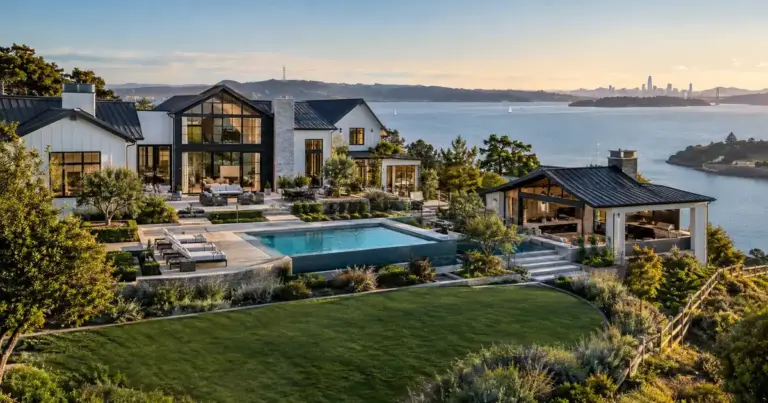
Luxury Rental DSCR Loans In Tiburon — A DSCR loan qualifies on what the property’s rent covers, not on the buyer’s paycheck.
Reserves, appraisal support, and full trailing-twelve-month documentation matter more here than almost anywhere else in the DSCR space.
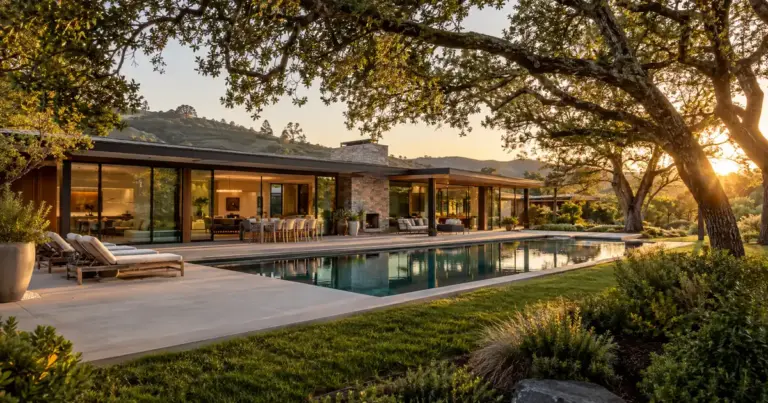
Luxury Rental DSCR Loans In Sonoma — A DSCR loan on a Sonoma luxury rental gets sized by the rent, not by the buyer’s income.
Luxury Rental DSCR Loans In Del Mar — A seasonal luxury rental doesn’t get financed on its best month.
Leverage steps down as the loan balance climbs, credit floors step up, and two appraisals become standard above $2,000,000.
In Los Altos Hills, the town’s licensing rule is built around owner-occupancy, which is a structural mismatch with a non-owner-occupied DSCR loan.
Reserves, appraisal count, and permitting status all move with loan size and property type, not with the calendar.
DSCR stands for debt service coverage ratio.
Leverage steps down as the loan gets bigger — roughly every million dollars — while credit floors and reserve documentation step up at the same time.
Sale prices in the area (MLSListings) push most acquisitions into the higher leverage tiers, where purchase financing typically tops out at 65-75%.