Cash-out Rules On A $1.5M Jumbo DSCR Rental Loan
Cash-Out Rules on a $1.5M Jumbo DSCR Rental Loan — At $1.5M, a DSCR rental cash-out refinance stops behaving like a standard-size deal.

Cash-Out Rules on a $1.5M Jumbo DSCR Rental Loan — At $1.5M, a DSCR rental cash-out refinance stops behaving like a standard-size deal.
None of these lines are set by a regulator — they’re lender convention, and they move file to file.

Cash-out Rules On A $4M Super Jumbo DSCR Rental Loan — At $4 million, cash-out is off the table.
Leverage in this band typically runs 75% on purchase and rate-and-term, and 70% on cash-out for standard rental collateral, with a 700 credit floor.
Neither option is better in the abstract. They solve different problems.
The federal conforming loan limit — the “ceiling” — is a Fannie Mae and Freddie Mac purchasing rule, not a legal wall on business-purpose DSCR lending.
The trustee doesn’t hand over the full trust agreement — a short certificate of trust does the job.
Loan sizes on this ladder run from $150,000 up to $10,000,000, with leverage stepping down as the balance climbs.
Loan sizes across the wholesale network run from $150,000 to $10,000,000 on the portfolio program, with short-term-rental files capped at $2,000,000.
Credit floors rise at the top of the ladder too, and short-term rental income gets qualified differently than a signed lease.
Loan sizes above $2 million usually mean two appraisals, and first-time investors should expect twelve months of reserves instead of six.
The property’s own rental income drives the ratio, not the entity’s payroll structure.
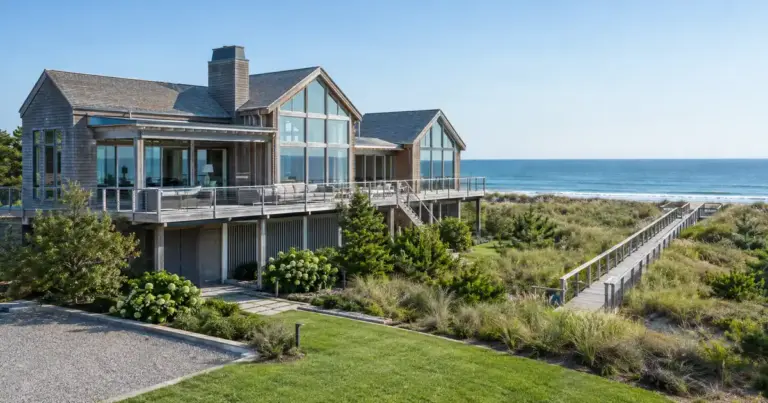
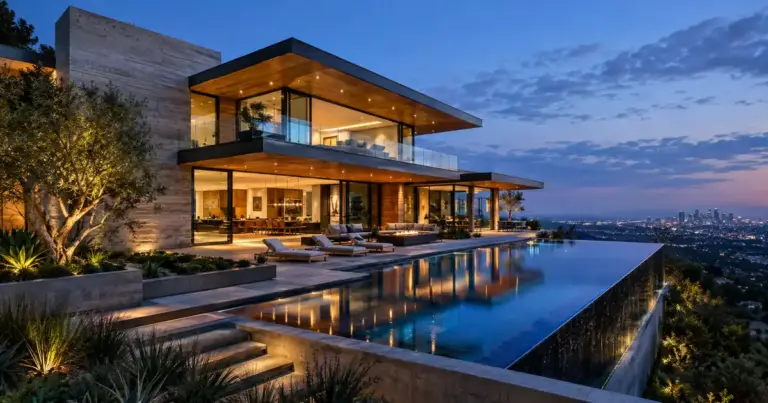
Documents a Lender Needs for a Luxury Vacation Rental DSCR Loan — The file centers on rental income proof, not personal income proof.
DSCR financing sidesteps that problem entirely, because qualification runs on the property’s rental income, not the borrower’s W-2 or K-1.
Every address in the pool gets its own valuation and rent conclusion — there’s no blended average.