How To Add A Jumbo Short-term Rental DSCR Loan To Your LLC Portfolio
Leverage steps down as the loan gets bigger, and the LLC shields property-level liability — not the loan itself.

Leverage steps down as the loan gets bigger, and the LLC shields property-level liability — not the loan itself.
Either way, expect the lender to apply a haircut to the income and use the most conservative figure available, not the highest one.
Does An LLC Short-Term Rental Need A Personal Guaranty On A DSCR Loan? — Yes, almost always.
Condotels blend a hotel operating model with individual unit ownership.
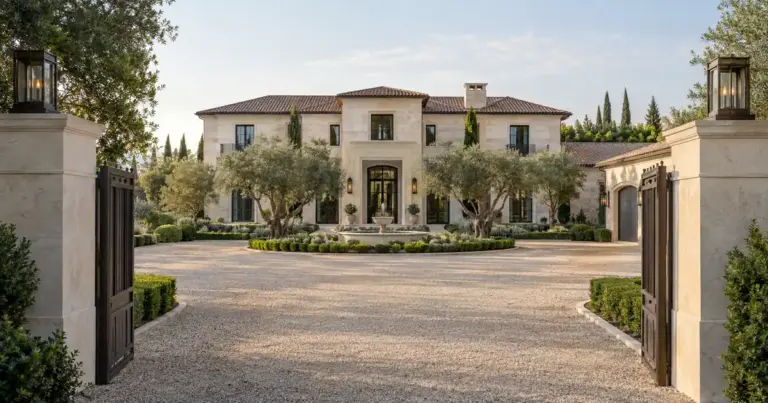
Above roughly $1 million, leverage steps down and credit requirements tighten.
That person’s credit, not the entity’s, drives the file.
Portfolio structure is a real choice: separate DSCR notes on each door, or a true blanket loan with cross-collateralization and a release clause.
Get title vested correctly at closing, not transferred afterward, and short-term rental income gets counted at a discount to gross, not full nightly rate.
Business-purpose DSCR financing solves the property side by qualifying on the unit’s rental income instead of a tax return.
Does A Llc-owned Short-term Rental Still Need Your Guaranty — Yes.
Qualification runs on the property’s rental income, documented either through twelve months of platform history or an appraiser’s short-term-rent analysis.
Does A Luxury Short-term Rental DSCR Loan Override A Below-market Lease — No.
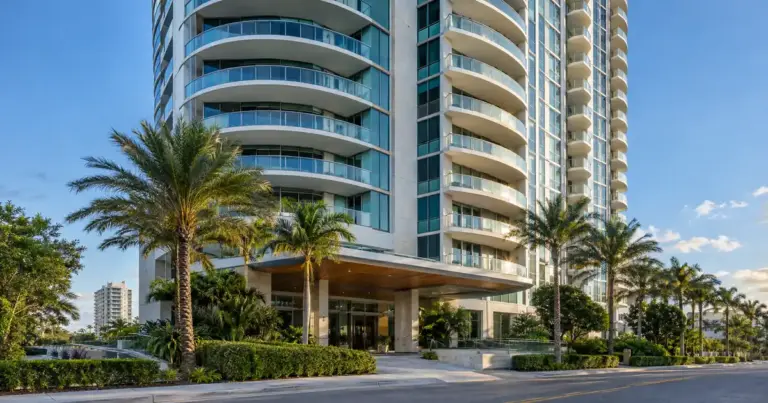
Coverage still matters, but property classification sets the ceiling first.
For a leased property, the lender takes the lower of the signed lease amount or the appraiser’s market-rent opinion.
If there’s a signed 12-month lease, or the borrower plans to rent long-term, the file runs on lease income.