Can A Family Office Hold A Short-term Rental Financed With A DSCR Loan?
Yes, a family office can hold a short-term rental financed with a DSCR loan, and this is not a workaround — it’s how these loans are built.

Yes, a family office can hold a short-term rental financed with a DSCR loan, and this is not a workaround — it’s how these loans are built.
But the income the lender can count changes overnight.
The path exists, but it narrows fast as the loan amount climbs.
The bigger the house, the more this matters. That’s the mechanic worth understanding before you shop a large vacation-rental purchase or refinance.
The lender blends those individual numbers into one coverage ratio for the loan, while still watching each address like it’s the only one that matters.
No. A super jumbo DSCR loan does not require long-term rent once the loan size climbs past the short-term-rental ceiling.
Does A Large Short-term Rental Have To Qualify On Long-term Rent: what investors need to know about large-balance DSCR financing, from Lendmire.
The result becomes the qualifying rent, subject to underwriting and lender guidelines.
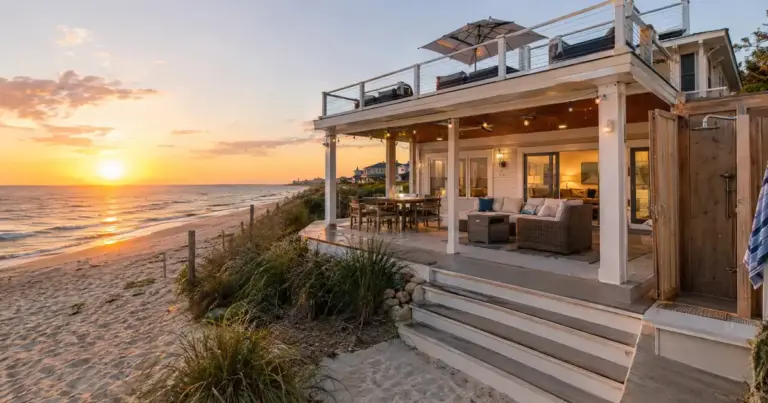
Can A Short-term Rental Purchase Qualify On Projected Rent — Yes, in most cases.
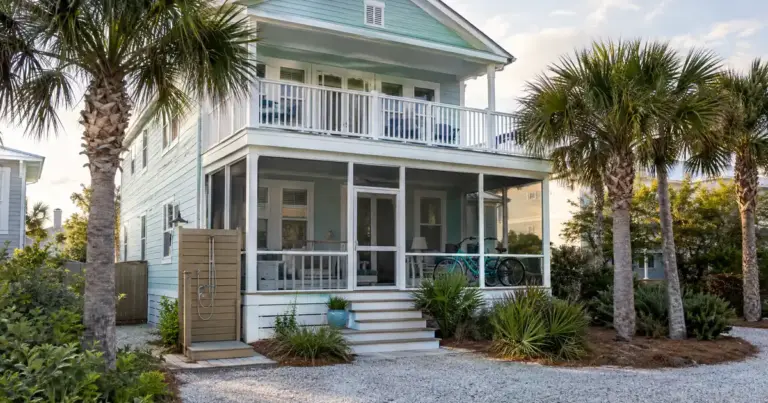
A standard long-term rent schedule won’t get you there because it’s built for monthly leases, not nightly bookings.
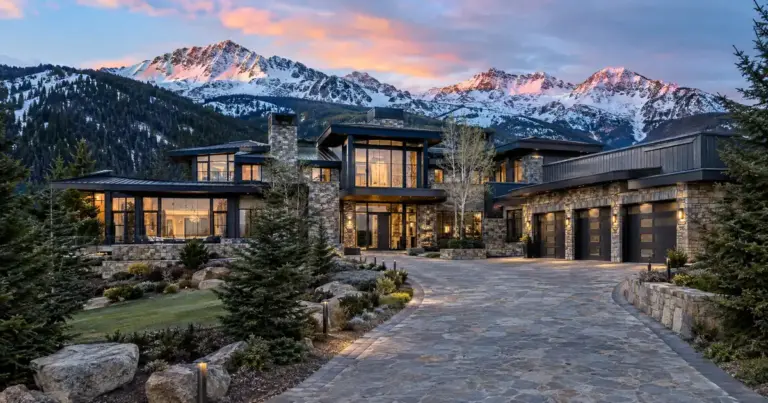
Luxury Short-term Rental Purchase Qualify On Projected Rent — Yes, in many cases.
Each property still gets its own appraisal and title work — only the cash flow and payment get pooled, not the collateral review.
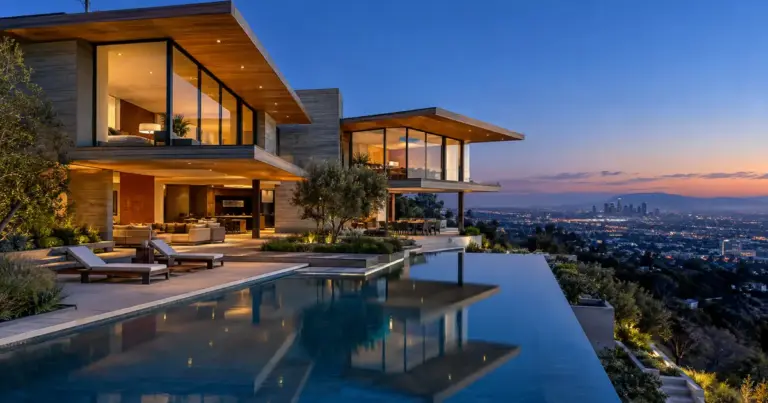
Leverage compresses as the loan gets bigger, cash-out disappears past a certain point, and every large file gets reviewed case by case.
Which path your file takes changes how much rent counts toward your DSCR ratio — and that changes your loan size.
Here’s how the mechanics actually work and where first-time buyers trip.