
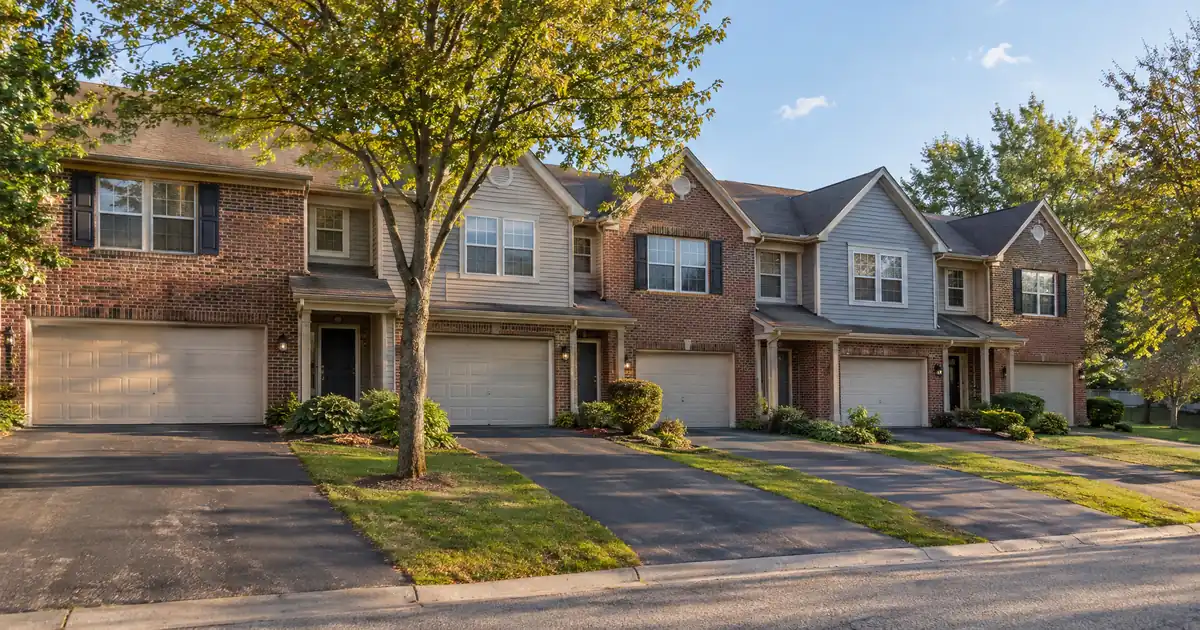
Only about 2% of Bolingbrook’s housing units are duplexes or small multifamily, according to NeighborhoodScout, while 72.5% are single-family detached. A 14.63% slice of attached townhomes and rowhouses sits on top of that. For an investor pulling equity out of a Bolingbrook rental, this lopsided mix sets the file. Appraisers have few multi-unit comps. Rent schedules get built from houses and townhomes. The cash-out math depends on one question: what will the appraiser say the property is worth?
Lendmire, a DSCR-focused mortgage broker, arranges cash-out refinances for investors who already own and want to redeploy capital. This article covers the plumbing for that move in Bolingbrook: seasoning, the 75% loan-to-value ceiling, documentation, and where the local data helps or hurts.
DSCR Cash-Out Calculator
Run the cash-out numbers in Bolingbrook, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance in Bolingbrook, Illinois is underwritten primarily on the rental property’s income measured against its full monthly obligation, rather than on the owner’s personal income documents. Proceeds depend on the appraised value, rent used for lender review, reserves, and the lender’s leverage ceiling, all subject to lender guidelines.
- Cash-out leverage typically tops out at 75% of appraised value, not the 80% available on purchases.
- Ownership of about 6 months, measured from title recording, is the typical seasoning benchmark.
- Local median price estimates range from roughly $316,000 to over $400,000 depending on source, so the appraisal decides the outcome.
- Bolingbrook’s rental stock is mostly single-family and townhome, so small-multifamily comps run thin.
- Most files are built on a 1.00x coverage baseline, with stronger credit tiers and reserves helping.
Bolingbrook Market Snapshot
A quick read on the Bolingbrook investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | ~7,000 students (romeoville.org — Lewis University) |
| Employment | 66,800 employees company-wide (Wikipedia: Ulta Beauty) |
Why the Appraisal Matters More Than Any Median
Published Bolingbrook price figures disagree by about $85,000, and that disagreement is the first thing a cash-out borrower should understand. Data USA, drawing on Census survey data, puts median property value at $314,700, up 6.5% from $295,500 the prior year. Prop:Metrics shows a $320,000 median price with a 3.9% year-over-year gain. Redfin’s dated figure was $365,000. NeighborhoodScout’s market-value estimate is $401,619. Same village, four numbers.
The gap comes from definitions: assessed versus sold, owner-estimated versus market, ZIP-level versus village-wide. For a borrower, the practical read is simple. Skip the median. Loan sizing is driven by the appraised value of the specific property, at a leverage cap of 75% for cash-out. Whether the subject appraises near $320,000 or near $400,000 moves the coverage ratio from comfortable to marginal, as the scenarios below show.
The embedded equity is real, though. NeighborhoodScout reports 93.58% cumulative appreciation over ten years, placing Bolingbrook in the top half nationally. An owner who bought three to ten years ago is likely sitting on meaningful equity. Recent momentum is softer. Prop:Metrics shows a Zillow one-year projection of just 0.9% and median days on market of 37, up 18% from a year earlier. So the refinance should be underwritten on today’s appraisal, not on what the property might be worth later.
What the Seasoning Clock Actually Measures
Seasoning is the most mechanical requirement in a cash-out file, and the one that trips investors who are close to the line. Most programs in the network look for about 6 months of ownership, measured from the date the deed records with the county, not from the contract date or the closing table. An investor who bought in a hurry and is counting from the signing date can be off by several weeks.
The typical sequence for a seasoned Bolingbrook owner looks like this:
1. Title check. Recording date of the current deed, plus any liens or prior cash-out activity on the property.
2. Lease or market-rent basis. A signed lease, or an appraiser’s rent schedule, depending on program.
3. Reserves. Liquid assets of about 6 months of PITIA is the typical benchmark (higher on very large loans).
4. Credit tier. Tiers commonly sit at 620, 660, 680 and 700, with 620 as the floor. Higher tiers generally support better leverage and pricing.
5. Entity documents. If the property sits in an LLC, the operating agreement and related documents get reviewed, subject to lender program eligibility.
Nothing glamorous. But the cash-out qualification details follow this skeleton, and files that arrive with recorded-deed evidence, a current lease and reserve statements in one package tend to move through lender review with fewer conditions.
Rent-to-Value: Why Bolingbrook Sits at the Thin End
Bolingbrook’s rent-to-value ratio is modest, and that is the central tension in a cash-out here. Rentcast data on Prop:Metrics shows median rent of $2,350 for a 2-bedroom, $2,600 for a 3-bedroom and $3,060 for a 4-bedroom. Against a $320,000 median price, the 3-bedroom works out to roughly 0.8% monthly rent-to-value (Lendmire Research arithmetic, not a sourced figure). A property priced above the median does worse.
That ratio matters because a DSCR loan is sized against the rent, not just the equity. How the qualification works is straightforward: qualifying monthly rent divided by the full monthly obligation, which includes principal, interest, taxes, insurance and any association dues. Most standard programs are built around a 1.00x baseline because rent covers the obligation at that level. Some lenders review lower ratios, but those files usually need lower leverage, more cash, stronger compensating factors or different pricing.
Run the numbers on a 3-bedroom rented at $2,600, taking that rent as a modeled assumption. All three cases below use 75% LTV and full PITIA, taxes and insurance included. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
| Appraised value | Modeled coverage | Read |
|---|---|---|
| $320,000 | Around 1.15x | Clears the baseline |
| $365,000 | Roughly 1.0x | Borderline |
| $401,000 | Below 1.0x | Needs restructuring |
Modeled on assumed rent and assumed taxes and insurance, not sourced market data.
Same rent. Same leverage. The only variable is what the appraiser says the house is worth. A 4-bedroom at a modeled $3,060 rent on the middle value lands in the low-1.2s under the same assumptions, which is why larger floor plans carry more of the cash-out load in this market.
When a file lands below 1.00x on long-term rent, the paths a lender may review include a sub-1.00 program at reduced leverage, an interest-only structure to lower the qualifying obligation, or a lower loan amount. Each is subject to lender guidelines, credit review and property review. None is automatic.
The Rent Data Disagrees Too (Don’t Underwrite on Growth)
Underwrite on the appraiser’s rent schedule or a signed lease, not on a rent-growth narrative. Bolingbrook’s published rent figures point in different directions. Zumper, a listing-based aggregator, shows average rent of $2,595, down 3% over the year. Rentcast, through Prop:Metrics, showed $2,460 average with 8.8% year-over-year growth at its earlier reading. Redfin’s rental page shows $2,003. The Census-derived median gross rent on City-Data is $1,760, which reflects existing leases, including older ones below today’s asking levels. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Flat to mixed is the fair description. Listing data tends to run above what in-place tenants pay, and Census figures trail the market. A lender will usually take the lower of a lease and an appraiser’s market rent, so a borrower who is holding a lease well below asking should not assume the asking number counts.
That has a practical consequence. If the lease on the subject sits at $2,300 and the appraiser’s schedule says $2,600, the conservative number drives the coverage ratio. Raising rent at renewal before applying, where the lease and local rules permit, can improve the file. Verify current local rental rules, taxes and insurance with qualified local professionals before changing terms.
Employment Anchors Behind the Rent Roll
Bolingbrook’s tenant base rests on a logistics-and-corporate mix, not a single employer. The Will County Center for Economic Development lists Ulta Beauty at 2,034 employees in Bolingbrook, plus Amazon at 10,000 across multiple county locations. Valley View School District #365 employs 2,400, and Joliet Junior College employs 1,576 across its Joliet and Romeoville campuses.
The industry data tells the same story at the village level. A Chmura JobsEQ overview hosted by Choose DuPage shows Transportation and Warehousing as the largest local sector at 6,049 workers, followed by Retail Trade at 5,670 and Wholesale Trade at 5,329. That data is a few years old, so read it as structure, not a current count. On the resident side, Data USA shows Health Care and Social Assistance leading at 5,358 workers, then Manufacturing at 5,162.
Two details make Bolingbrook different from a bedroom suburb. First, Ulta is headquartered here and runs a distribution operation in the village, so the tenant pool includes salaried office staff and warehouse workers. Second, City-Data counts 10,471 workers (28.8%) who both live and work in the village, and daytime population rises by 6,215 from commuting. A quarter-plus of the workforce with no commute risk is a steadying factor for long-term lease renewals.
The Hospital Corridor and the 60446 Edge
Bolingbrook’s submarkets are best described by what anchors them. No reliable neighborhood-level rent or price source exists, so this section stays qualitative on purpose.
The 60440 core. Most of the village’s single-family subdivisions sit here. Prop:Metrics data is keyed to this ZIP, and its rent and price figures are the closest thing to a core-market benchmark. Planned-community stock built mostly after 1960 means fairly uniform product, which helps appraisal comparability. Uniform product is a real advantage for a cash-out, because an appraiser can find three similar recent sales without a wide search.
The Remington Boulevard hospital area. UChicago Medicine AdventHealth Bolingbrook is a 138-bed medical center with a Level II trauma designation, serving the area since 2008 and listed in the Illinois Hospital Report Card. Hospital staffing is a steady source of renter demand for nearby townhomes and smaller houses. Health care is also the largest resident occupation group in the village.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Bolingbrook, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The 60446 side toward Romeoville. The edge toward Romeoville puts renters within reach of Lewis University, with nearly 7,000 students on a 410-acre campus, and of Romeoville’s Amazon and refinery payrolls. Bolingbrook has no four-year university of its own, so student demand here is an overflow effect, not a core driver. Don’t pitch a file as a student rental.
The Route 53 and I-55 corridor. Retail and highway access, with the Arbor Drive logistics belt nearby. Logistics tenants gravitate here for commute reasons. Proximity to warehouse employment supports long-term leasing, though it says nothing about coverage ratios on its own.
Where Small Multifamily Gets Complicated
A cash-out on a duplex, triplex or fourplex in Bolingbrook is possible but harder to appraise. With about 2% of units in small multifamily, comps are scarce. An appraiser may widen the search radius or reach into adjacent suburbs, and that can pull the value in either direction. Borrowers holding a rare two-to-four unit should expect extra appraisal scrutiny and should not assume a single-family-style valuation.
The income-stacking play in this market leans toward the 4-bedroom house or larger townhome, not the fourplex. That is Lendmire Research’s inference, not a sourced fact. Rentcast’s $3,060 median for 4-bedrooms against $2,600 for 3-bedrooms shows a rent premium for the extra bedroom. Whether that premium justifies the higher price on a specific house depends on the appraisal.
Large apartment complexes account for 10.79% of units, but those are institutional assets, not DSCR-loan territory for small investors. Manufactured homes, log homes and barndominiums fall outside these DSCR programs entirely.
What the Deal Desk Tends to See
Files from planned-community suburbs like this one tend to share a pattern. The cleaner files from a documentation standpoint arrive with a recorded deed, a current signed lease, a fresh insurance declaration and reserve statements already assembled. The common friction point is a gap between the lease rent and the appraiser’s rent schedule, which quietly shifts the coverage ratio after the application is in. Investors who have held a property several years often carry below-market leases, so the ratio they expect on day one is not always the ratio the lender calculates.
Short on Room? Reading a Sub-1.00 File
Some Bolingbrook files will land under the baseline, especially on houses appraised well above the median. Think about what that looks like. An investor owns a 3-bedroom valued near the top of the local range, and rent doesn’t cover the full obligation at 75% leverage. Options worth raising with a broker: a lower leverage request, a program that reviews sub-1.00 coverage, an interest-only period or a rate-and-term refinance in place of cash-out. Each changes the proceeds. The stronger play is often a smaller cash-out that clears coverage cleanly, though an investor with a specific acquisition in mind could argue for the larger draw and accept the tighter file. Both paths are reviewed, not promised.
Investor competition looks limited, for what it is worth. Prop:Metrics reports investors made 2.0% of HUD-reported loans in the most recent year available. That is a thin data point, but it suggests the market isn’t crowded with leveraged landlords bidding against each other.
For a broader view of how the financing structure differs from traditional underwriting, Lendmire’s comparison of DSCR versus conventional loans covers it in more depth. For owners weighing a rate-and-term move instead, Lendmire’s refinance guidance for investor properties covers that route. Loan amounts on standard programs run up to $3,000,000, with smaller balances routed through select lenders in the network. Bolingbrook balances sit well inside that range. Investors ready to test a specific property can request a scenario quote or call 828-256-2183. Broader statewide context lives on the Illinois DSCR investor loans page.
The Choice at the End of the Seasoning Clock
Bolingbrook owners who have passed six months of ownership face a fork. One path is a full cash-out at the 75% ceiling, which maximizes proceeds for the next acquisition but leaves coverage closer to 1.0x on any house appraised above the local median. The other is a smaller draw that keeps coverage comfortably above the baseline and leaves more room if rents soften, at the price of less capital to redeploy. With Zumper showing rents down and appreciation projections near flat, the question is whether the next property’s upside justifies thinning the cushion on this one.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on a Bolingbrook rental?
Qualification centers on the property’s rent used for lender review relative to its full monthly obligation, with a typical 1.00x baseline. Lenders also review credit (floor commonly 620), about 6 months of reserves, and roughly 6 months of ownership from deed recording. Eligibility depends on lender guidelines, credit approval and property review.
What are the requirements for an investment property loan in Bolingbrook, Illinois?
Expect a 75% maximum LTV on cash-out, an appraisal with a rent schedule, proof of ownership and a current lease where one exists. Entity-owned properties add document review, subject to program eligibility. Manufactured homes, log homes and barndominiums are outside these programs.
Why might two Bolingbrook investors with similar houses get different cash-out proceeds?
Appraised value and documented rent drive the difference. Local median estimates span roughly $316,000 to over $400,000 depending on the source, and a lease below the appraiser’s rent schedule lowers the coverage ratio. Proceeds are never a fixed number until the appraisal and program review are in.
Does Bolingbrook’s single-family-heavy housing stock help or hurt a cash-out?
Mostly it helps, because uniform subdivision product gives appraisers comparable sales close by. The limit is rent-to-value, which runs around 0.8% on a median 3-bedroom, so higher leverage can press the coverage ratio. Small multifamily is the opposite case: rare, and harder to value.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage rather than personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage and program. The brokerage has been recognized by Scotsman Guide as a 2026 Top Workplace and recognized by Scotsman Guide in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. NeighborhoodScout: Bolingbrook real estate
2. Village of Romeoville: Lewis University
6. Zumper: Bolingbrook rent research
7. Will County Center for Economic Development: major employers
8. Choose DuPage: Village of Bolingbrook economic overview
9. UChicago Medicine AdventHealth Bolingbrook
10. Illinois Hospital Report Card
11. recognized by Scotsman Guide as a 2026 Top Workplace
12. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Bolingbrook, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.