
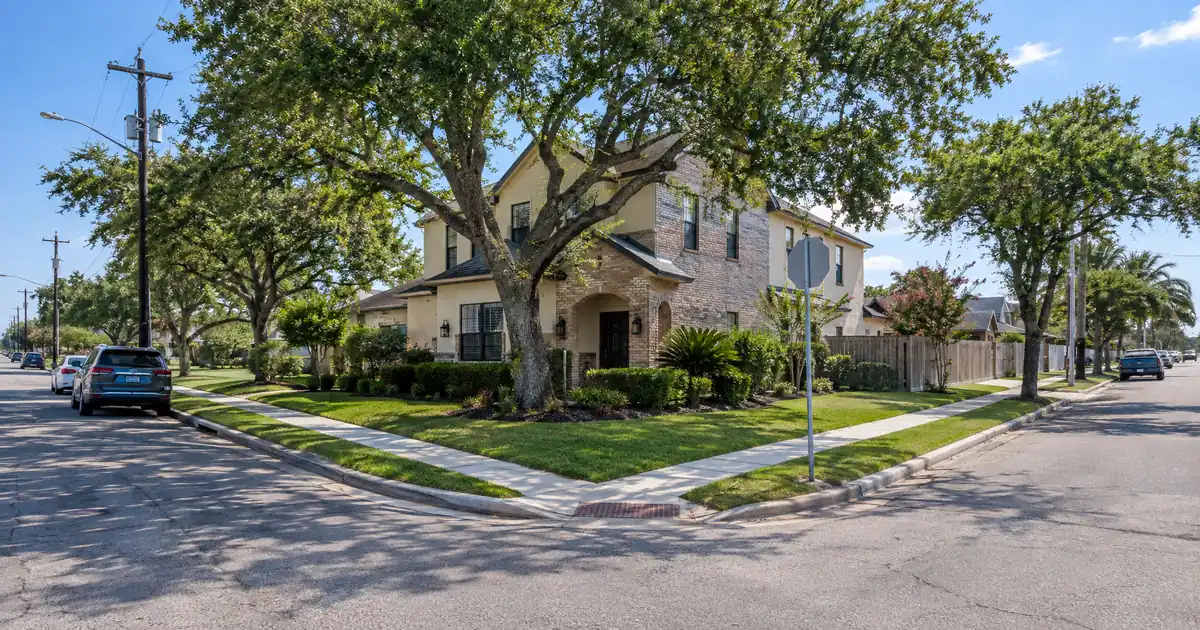
A cash-out file in Corpus Christi starts with a coverage problem, not an equity problem. Against a median rent near $1,500 per Zillow and a median sale price of $262K per Redfin, the citywide numbers do not clear 1.00 once taxes and insurance sit in the denominator. The investors who pull equity here pick the right submarket first, then the right loan-to-value, then document the rent.
The Short Version: A DSCR cash-out refinance in Corpus Christi, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file turns on a supportable rent, a clean appraisal, and about 6 months of title seasoning before any proceeds are sized.
DSCR Cash-Out Calculator
Run the cash-out numbers in Corpus Christi, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out caps at 75% LTV, below the purchase ceiling, and proceeds shrink if the appraisal lands flat.
- Redfin shows a $262K median sale price, down 0.38% year over year (Redfin).
- Tactica RES lists metro apartment vacancy at 9.7% (Tactica RES).
- Southside and Annaville carry the best rent-to-value on the research.
- Flour Bluff files need flood-zone and insurance documents early.
- Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Corpus Christi Market Snapshot
A quick read on the Corpus Christi investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Employment | 7,110 direct employees (Texas Comptroller, NAS Corpus) |
| Vacancy | 9.7% (Tactica RES) |
Where the Coverage Number Clears (and Where It Doesn’t)
Southside and Annaville are where cash-out coverage works best in Corpus Christi. Southside 3-bedroom rents sit well above the citywide median, and Annaville pairs a low price with solid rent. Citywide medians, by contrast, run below 1.00 on full PITIA at cash-out leverage.
Run the numbers on the citywide picture first. Modeled assumptions: a property valued at the $262K Redfin median, a 75% cash-out loan, rent at a modeled $1,500, and a payment that includes taxes and insurance. That lands around 0.8x. A property like that is a sub-1.00 file. Lenders may review it through a sub-1.00 program, a lower LTV, or an interest-only structure, subject to lender guidelines, credit approval and property review. Treat those as options a lender reviews, not outcomes.
Now Southside. Prop-metrics reports a ZIP 78418 median home price of $302,000 and Rentcast-sourced median rents of $1,650 for 2-bedrooms and $2,370 for 3-bedrooms. Model a $302,000 value at 75% LTV against the 3-bedroom rent, including taxes and insurance, and the coverage sits around 1.1x. Round down, because the aggregator rent is a median across the ZIP, not your unit. Southside rent moved -0.5% year over year in the same data, so don’t underwrite growth. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Annaville is the value end. NeighborhoodScout puts the median price at $230,209 and the average rent at $1,640. Same modeled structure, and the coverage lands right around 1.0x. That is thin. A single stale lease or a rent that comes in under the schedule pushes it under.
(The Southside and Annaville figures come from aggregators that disagree with other sources. Ark7 shows a lower Southside price range. Use the figures as direction, then replace them with closed comps and a signed lease.)
Flat Values Change the Cash-Out Math
Corpus Christi values are flat to soft, so cash-out proceeds depend on today’s appraisal, not on appreciation since purchase. The sources spread widely. Zillow’s typical home value is $218,988, up 0.2%, Redfin shows $262K, and Movoto shows $295,000 with 73 days on market. A separate aggregator, Bricksly, shows -1.9% year over year.
Mechanically, that means three things on the file:
- The 75% LTV ceiling applies to the appraised value, not what you paid or what a portal says.
- Seasoning runs about 6 months from title recording, and the settlement statement is the proof. Files that assume it away get kicked back.
- Equity is not a guaranteed cash figure. It depends on rent used for lender review, PITIA, reserves of about 6 months, and the LTV cap.
- These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
The honest read: an investor who bought in the last couple of years may find little equity to pull. The better candidates are owners who bought below the current median, or who added value through renovation that the appraiser can support. Appraisal reconsideration is a routine step here. A packet with recent in-neighborhood closed sales and condition adjustments is what moves a light number.
Skip the Coastal Product
Padre Island and North Beach lean toward short-term use and sit outside this article’s long-term-rental math. Downtown has apartment-heavy stock and a tourism-driven tenant base. The strongest documented long-term demand is for 3 to 4 bedroom rentals in Southside and Flour Bluff, per LRG Realty.
Flour Bluff: Steady Tenants, Heavier Paperwork
Flour Bluff pairs a stable workforce tenant base with a documentation burden. The peninsula sits next to Naval Air Station Corpus Christi, and Texas Comptroller data puts the installation at 7,110 direct employees, including 1,917 active-duty personnel. The Corpus Christi Army Depot is the largest industrial employer in South Texas. That is employment-driven rental demand with built-in rotation.
Pricing is softer. Redfin’s Flour Bluff page shows an average house price of $250K, down 4.2% year over year, and the same page flags major flood risk. I found no reliable Flour Bluff rent figure, so the coverage number has to come from your lease and an appraiser’s rent schedule, not a portal.
Here is where files stall. The flood zone determination and the insurance quote have to be complete before the file goes to the lender. A quote priced on last year’s assumptions that gets re-run during review can drop the coverage ratio below the floor. Pull a fresh binder first. Verify current local rules, taxes and insurance with qualified local professionals.
What Small Multifamily Does to the Math
Duplexes and fourplexes can lift rent-to-value above single-family, but the evidence here is asking-price data only. Homes.com lists 54 multifamily properties for sale, priced from $79,900 to $3.9M, with a 79-day average time on market. Downtown listings run from $105,900 to $550,000 per Homes.com. Southside new-build duplexes show 3-bed, 2.5-bath sides of about 1,330 square feet per Homes.com.
I found no sourced per-unit rents for these, and one listing’s advertised 10.3% cap rate is a marketing claim. Don’t underwrite off it. For a cash-out on a small multifamily property you already own, the rent roll is the file. Each unit needs a lease, and the rent roll needs to tie to the appraiser’s rent schedule.
Vacancy Is Structural, Not New
Corpus Christi vacancy runs high but is not worsening from new supply. Tactica RES lists metro apartment vacancy at 9.7% against a five-year average of 10.3%, with a 0.40% supply ratio (Tactica RES). High vacancy is normal here, not a new phenomenon.
For a DSCR file, that matters in the rent used. Underwrite on conservative rents and a real lease, not a best-case market rent. This is not Sun Belt tightness.
The Demand Base Behind the Rents
Energy and the military carry rental demand, with healthcare behind them. A Texas A&M-Corpus Christi economist quoted by Marketplace says energy accounts for roughly 40% of local economic output. The Texas Economic Development Corporation names healthcare, energy and advanced manufacturing as the main workforce sectors.
Employer names from a dated HUD report include Corpus Christi ISD, CHRISTUS Spohn Health System, H-E-B, Driscoll Children’s Hospital and Corpus Christi Medical Center. Texas A&M University-Corpus Christi reports 8,673 undergraduates. Population is flat at about 317,247 per Census data, so demand comes from jobs, not in-migration.
The Water Question
This is the one risk with no equivalent in peer Texas cities, and it deserves its own line in any underwriting file. The Texas Tribune reports the city could become the first U.S. city to run short of water, with emergency restrictions projected for December and desalination delivering water in late 2029 at the earliest. It is not a loan-qualification item today, but it is a hold-period consideration. A property that sits unrented through a stressed stretch still carries its debt.
How a Cash-Out File Typically Looks Here
DSCR files in markets like this one typically look the same: a modest coverage cushion, a flat appraisal, and a delay-prone checklist. Rent is supported by a lease and the appraiser’s rent schedule. Entity documents sit in the file if the property is titled in an LLC, subject to lender program eligibility. Reserves are documented as about 6 months of PITIA. The files that stall are the ones where the lease is expired or the insurance quote is incomplete, and where the appraisal comes back under the number the investor assumed. Credit tiers start at a 620 floor, with better terms at higher scores.
Here, the equity recycle pathway works when the proceeds fund the next deal and the existing property still covers its payment afterward. Run the post-refinance coverage, not just the cash. For the underlying mechanics, see the DSCR qualification mechanics. For the alternative path, see the guide “Where DSCR and Conventional Diverge” and investor refinance options.
Where Most Investors Get It Wrong Here
They treat the portal median as the appraisal. Four sources show four different medians, and none of them is your property. Honestly, the stronger play is probably the lower-priced southside or Annaville property with a documented lease, over a coastal asset with an uncertain rent. Appreciation-minded buyers could argue the other way, but flat values make that a hard case right now.
For a rental-income quote on a Texas property, see get a rental-income loan quote or call 828-256-2183.
Next Step: Build the Comp Packet
Before any application, pull three closed rental comps and three closed sale comps from the subject’s own ZIP, and confirm the lease in place matches the rent you are modeling, because in Corpus Christi the appraisal and the lease, not the portal median, decide how much equity comes out.
Frequently Asked Questions
How do you qualify for a DSCR loan in Corpus Christi?
Qualification centers on the property’s rent against its full monthly obligation, with a 1.00 baseline common on standard programs. Lenders also review credit, with a floor around 620, and reserves near 6 months of PITIA. Subject to lender guidelines, credit approval and property review. See Texas DSCR investor loans for the state overview.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Corpus Christi, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property cash-out refinance in Corpus Christi, Texas?
Expect a 75% maximum LTV, about 6 months of seasoning measured from title recording, and a coverage ratio of at least 1.00 on typical programs. The file needs a lease or rent schedule, an appraisal, insurance documents and reserves documentation. Exact eligibility depends on the lender and the property.
How much equity can you pull if Corpus Christi values are flat?
Less than an appreciation-driven market would allow. The cash-out is sized on the appraised value at 75% LTV, minus the existing balance, and is limited by coverage and reserves. Sources show values roughly flat, so model off today’s appraisal and expect little gain from seasoning. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Do Flour Bluff properties need extra documentation?
Yes, flood-zone and insurance documents come first. One source flags major flood risk in the neighborhood, so the insurance quote has to be complete and current before the file goes to the lender. Rent evidence matters too, since no reliable Flour Bluff rent figure exists in the research.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C. Lenders generally review eligibility on the property’s cash flow rather than traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2025 Scotsman Guide Top Workplace and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin, Corpus Christi housing market
3. Tactica RES
4. Texas Comptroller, NAS Corpus Christi
5. Prop-metrics
7. Zillow — Home Values Corpus Christi TX
8. Movoto
9. Bricksly
10. LRG Realty
12. Homes.com
13. Homes.com
14. Homes.com
15. Marketplace
16. Texas Economic Development Corporation
17. HUD report
18. U.S. Census Bureau QuickFacts
19. Texas Tribune
20. a 2025 Scotsman Guide Top Workplace
21. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Corpus Christi Texas · DSCR Loans in Corpus Christi, Texas: Investor Financing for North Beach, Flour Bluff, Portland & Real Estate Investors · DSCR Investment Property Loans in Port Aransas, TX: The 2026 DSCR Financing Guide to Mustang Island
Guides: Investment Property Cash-Out Refinance in Corpus Christi, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.