
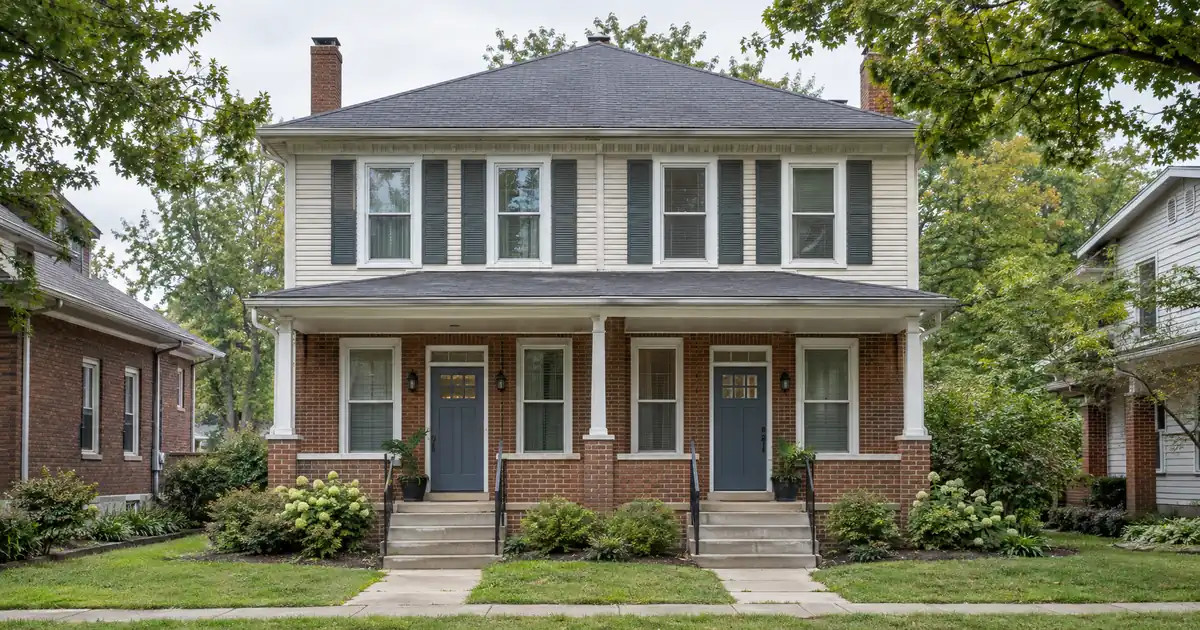
The first number on an Evansville cash-out file is the appraised value, not the rent. South Side sales sit near a $130K median, and a 75 percent LTV ceiling on a value that size leaves a small loan. Whether that loan clears the coverage test depends on what the appraiser’s rent schedule says.
TL;DR: A DSCR cash-out refinance on an Evansville, Indiana rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the amount you can pull out capped by appraised value, seasoning and reserves. Lender guidelines govern the outcome.
DSCR Cash-Out Calculator
Run the cash-out numbers in Evansville, IN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV tops out at 75 percent, and seasoning runs about six months from title recording.
- Evansville’s median sale price is $154,897, down 10.2 percent year over year, so appraisals need scrutiny.
- Older one- and two-star apartment stock has the lowest vacancy, at 4.9 percent per Kirkland.
- Stacked units (duplexes through fourplexes) carry more coverage cushion than a single 3BR at the same value.
Evansville Market Snapshot
A quick read on the Evansville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Population | 273K/271K population figures (Kirkland Company, Feb 2025) |
| Vacancy | 5.5% (The Kirkland Company) |
The Appraisal Is the Real Gate Here
Evansville’s citywide median sale price is $154,897, down 10.2 percent year over year. That is a falling number, and cash-out math runs on value. Don’t assume “appreciation” as a blanket trend in this city. It isn’t one.
The submarkets split. The South Side sits at that $130K median, down 3.8 percent. The East Side runs $230K, up 6.2 percent. The North Side shows $202K, up 12.2 percent. So an investor who bought on the North Side and held six months is in a different equity position than one who bought on the South Side.
This is the appreciation-versus-cash-flow tension in one city. The South Side gives you the best rent-to-price ratio and the weakest value trend. The East and North Sides give you value momentum and thinner coverage. Which one works for a cash-out depends on which constraint binds first on your file: the 75 percent LTV cap or the 1.00 coverage benchmark.
Two program facts frame everything else. Seasoning before cash-out is about six months, measured from title recording, and the settlement statement is the proof. Equity available depends on rent used for lender review, the full monthly obligation, reserves and the LTV ceiling. It is never a guaranteed cash figure. Details are subject to lender guidelines, and Lendmire’s DSCR cash-out refinance page lays out the structure.
Run the Numbers: One 3BR Versus Stacked Units
Metro-wide, Rental Beast reports 1BR rents at $685, 2BR at $885 and 3BR at $1,100. Its single-family average is $900, but its definition of “single-family” is four or fewer units. So that $900 includes duplexes through fourplexes. Read the category carefully before you put it in a rent schedule.
Run the numbers on a modeled 3BR house. Assume $1,100 rent (the Rental Beast MSA figure, not a property-specific comp) on a $130K appraised value at 75 percent LTV. Measured against the full monthly obligation including taxes and insurance, coverage lands around 1.3x. Now move the same $1,100 rent to a $230K East Side value at 75 percent. Coverage drops below 0.85x. Same rent, different price, different file.
Below 1.00 isn’t a dead end. A lender may review options such as a sub-1.00 program, an interest-only structure or a lower LTV. Each comes with its own pricing, reserve and credit conditions, and none is a given. Better to see it before the appraisal than after.
Stacked units change the picture. Two 2BR doors at $885 each (modeled, MSA-wide) put far more rent against the same property value than one 3BR at $1,100. In a market where the value is low and the rent per door is modest, unit count does the work. A duplex or fourplex is the natural DSCR cash-out property here. This is the practical version of the rate-and-term and cash-out refi details most investors need to see side by side.
DSCR files in markets like this one typically look the same. Purchase price is low, rents are modest and the loan balance is small. The coverage ratio clears comfortably on stacked income and gets thin on a single door at a higher price. The stronger files show up with a signed lease for each unit, an entity operating agreement that matches the title vesting, and a reserves statement already in hand. The weaker ones stall on a rent schedule that doesn’t match the appraiser’s, or on seasoning proof that arrives late.
Where the Equity Sits
South Side. This is the entry-price play. Redfin puts the median at $130K and $110 per square foot, up 6.8 percent, and scores the market as very market-rate. Workforce single-family and small multifamily dominate. Balances here run small. Smaller loans route through select lenders in the network rather than the standard programs, which affects both eligibility and pricing. Plan for that before you plan the payout.
Lamasco, Jacobsville, Riverside and Culver. These historic-core neighborhoods hold the older duplexes and small multi-unit buildings where income stacking works best. Lamasco, on the west side around Franklin Street, is home to the annual Nut Club Fall Festival. Jacobsville, north of the Lloyd Expressway, sits around Garvin Park and Bosse Field. Riverside is the walkable historic district that United Neighborhoods of Evansville describes. Price data for these areas is thin and mostly from investing blogs. Treat any neighborhood-level rent as directional and let the appraiser’s comps carry the file.
East and North Sides. Newer construction and more suburban single-family stock. Values are rising, so a six-month-seasoned purchase may appraise above its basis. But a single house at these prices carries the coverage problem from the math above. These work best when you’re refinancing something that already carries strong rent.
Downtown. Handle with care. NeighborhoodScout models a $379,449 median price and $1,557 average rent with 91.4 percent renter-occupied housing. Rent.com reports far lower asking rents for the same area. The sources conflict, and new and condo product skews the price. It’s a genuine toss-up whether Downtown belongs in a cash-out plan at all, since the value is high but small-unit rents may not carry it. Underwrite it from actual comps, not either model.
Newburgh. Warrick County has the highest rents by submarket, at $1,266 per unit with 3.4 percent growth. It’s the appreciation-led side of the metro, outside city limits, with healthcare employment nearby. Higher rent generally comes with higher price, so coverage doesn’t automatically improve.
Why the Rent Roll Holds
Kirkland puts market vacancy at 5.5 percent across 18,589 units, with only 162 under construction. Vacancy runs 7.2 percent in four- and five-star product, 5.6 percent in three-star and 4.9 percent in one- and two-star. Older, lower-cost stock is the tightest segment. That’s the stock a DSCR cash-out borrower typically owns.
Kirkland calls rent growth stable but moderating, and Multi-Housing News reports 3.7 percent year over year. Growth figures differ across reports (Kirkland’s metro asking-rent figure is 2.3 percent), so pick one source and label it in your file. Don’t mix them.
Demand comes from the job base. The MSA population is 273,519 and unemployment is 2.5 percent. Education and health services and trade, transportation and utilities each account for about 27,000 jobs. Deaconess Health System is the largest employer, with roughly 10,500 employees per ez Home Search, a secondary source. Treat that as approximate. Toyota’s Princeton plant sits about 25 miles north and Berry Global is headquartered in the city. On the hospital side, the Indiana Department of Health lists 571 staffed beds at Deaconess Midtown and 450 at Ascension St. Vincent Evansville.
None of this is a boom. The recent additions are logistics-oriented, so underwrite steady rents rather than outsized appreciation.
What Derails Evansville Cash-Out Files
Rent schedule mismatch comes first. The lease says one number, the appraiser’s rent schedule says another and the lender uses the lower one. Reconcile before submission. If the appraisal comes back light, an appraisal reconsideration packet with recent in-neighborhood sales is a routine step, not an emergency.
Seasoning proof is second. Files that count from contract date instead of title recording get kicked back. The settlement statement is the document that matters.
Unit-count definitions are third. Pulling the Rental Beast “single-family” average into a fourplex schedule is a common shortcut. The number covers one to four units, so it blurs the property you’re actually financing.
Balance size is fourth. South Side loans can fall below what standard programs prefer. Ask early whether the file routes through a select lender.
Last is documentation. Entity documents, current leases and reserves documentation (about six months of the full monthly obligation on most files) need to match each other. LLC-held rentals are eligible subject to lender program eligibility. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Clean paperwork gives the lender fewer preventable gaps. It doesn’t guarantee an outcome.
Where the Proceeds Go
The point of a cash-out is the next deal. In Evansville, that usually means a second small multifamily building at South Side or historic-core prices. A cash-out on one duplex can fund the down payment on the next. The leverage is real, but so is the stacking risk. Two loans at 75 percent LTV on a market with a falling median leaves little cushion if values slip further. Size the second purchase to clear the 1.00 benchmark on its own, not on the strength of the first.
Some investors will find a rate-and-term refinance cleaner than a cash-out, especially where the appraisal is light. The DSCR guide explains how the ratio works. And start your quote or call 828-256-2183 to run a specific file. Verify current local rental rules, taxes and insurance (including flood coverage) with qualified local professionals before you commit.
DSCR vs. conventional financing
Two common ways to finance an investment property in Evansville, IN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Evansville?
Qualification centers on the property’s rent against its full monthly obligation, with 1.00 as the common benchmark. Lenders also review credit (620 minimum), reserves of about six months, about six months of seasoning from title recording and the 75 percent LTV ceiling. Eligibility depends on lender guidelines, property review and credit approval.
What are the requirements for an investment property loan in Evansville, Indiana?
Expect an appraisal with a rent schedule, current leases, entity documents if the property is LLC-held and proof of reserves. Loan sizes run up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network. Manufactured homes, log homes and barndominiums fall outside these programs.
Does a falling citywide median price hurt a cash-out in Evansville?
It can, because cash-out proceeds depend on appraised value, and the citywide median sale price has been declining year over year. But the East and North Sides are rising, so results depend on the submarket. A South Side property may appraise flat or lower, while a North Side property may appraise above its purchase price.
Why do duplexes and fourplexes work better than single-family homes here?
Rents per door are modest, at about $885 for a 2BR metro-wide, while values on the South Side are low. Stacked units put more rent against the same property value, which supports coverage. A single 3BR at the same rent gets thin quickly as price rises.
What documents matter most for an Evansville DSCR cash-out review?
Current leases, the entity documents, the settlement statement showing title recording and a reserves statement matter most. Lendmire arranges these files through its wholesale network, and its DSCR programs qualify primarily on the property’s rental income rather than personal income documentation.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. Lenders generally review DSCR eligibility around a property’s rental income rather than personal income documentation, which suits LLC-held rentals, self-employed investors and portfolios growing past conventional financed-property limits. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace, was a top-ranked workplace in 2025 and was covered in the Top Workplace press announcement.
Over the next six to twenty-four months, expect Evansville’s older duplex and fourplex stock to keep its edge. Vacancy is tightest there, near-term apartment supply is a single 162-unit project and job additions are modest but steady. Investors who season a small multifamily purchase and hold coverage above 1.00 will likely have workable cash-out files, while single-family owners at higher price points will have to earn theirs.
For broader investor-financing rules and property-type coverage across the state, see Indiana DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $130K median
2. $154,897
3. Kirkland
5. East Side
6. North Side
8. United Neighborhoods of Evansville
9. NeighborhoodScout — Evansville Downtown Evansville
11. ez Home Search
12. Indiana Department of Health
13. recognized by Scotsman Guide as a 2026 Top Workplace
14. Scotsman Guide — Top Workplaces 2025
15. the Top Workplace press announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Evansville, IN · Investment Property Cash-Out Refinance in Indiana
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.