
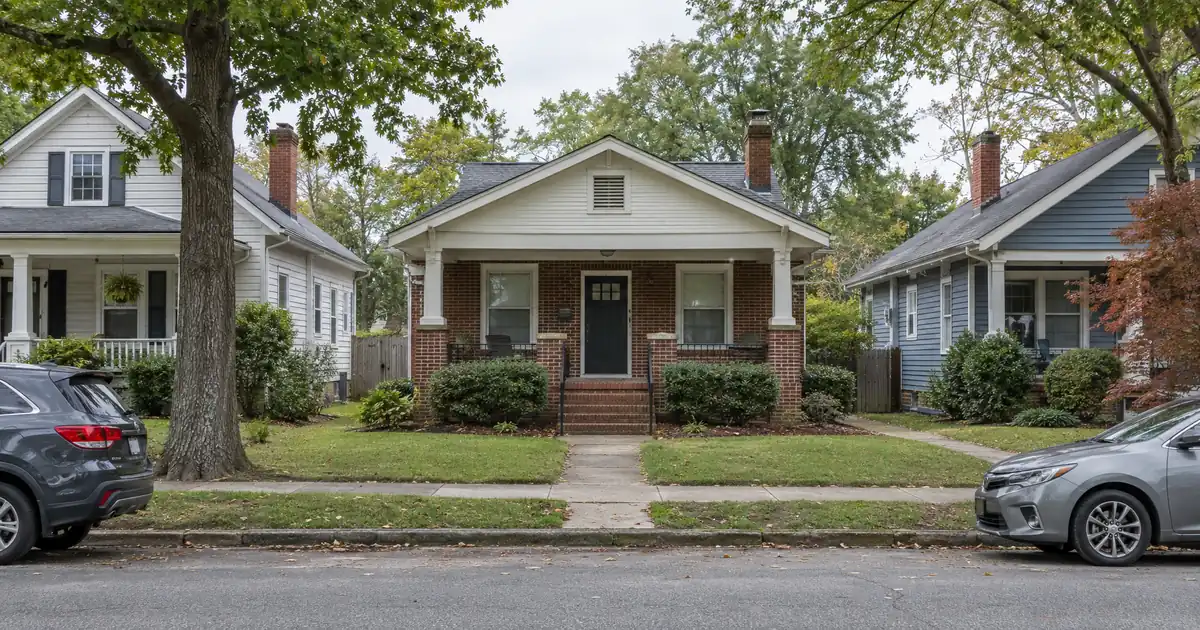
A DSCR cash-out on a Fayetteville rental comes down to one test: does the rent, set against full monthly obligations that include taxes and insurance, hold at or above 1.00 after the 75% LTV cap trims the loan? Fayetteville’s median home prices sit in the mid-$200Ks, so coverage is tight on single-family houses and stronger on small multifamily. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
The Quick Read: A cash-out refinance in Fayetteville, North Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, with loan size capped at 75% of appraised value, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Fayetteville, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow puts the average Fayetteville home value at $225,510, up just 0.1% year over year.
- Houzeo shows a flat $250,000 median sale price and a 1.91-month supply.
- Owners who bought before 2022 hold equity from a completed run-up, not a continuing one.
- Duplexes through fourplexes give the coverage ratio more cushion than a single house renting near $1,300.
- Cash-out typically needs about 6 months of ownership, measured from title recording.
Fayetteville, North Carolina rental property investors can tap DSCR programs that Lendmire arranges, available across 41 markets, including Washington, D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, so it places these loans through investor lending channels and does not underwrite them itself. Review details are subject to lender overlays.
Fayetteville Market Snapshot
A quick read on the Fayetteville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median income $56,685 (CityView NC, housing and rental) |
| University enrollment | ~2,500 military-family students (CityView NC, FSU and FTCC) |
| Population | 209,485 population (Census Reporter, Fayetteville) |
| Employment | 9,500+ employees (Cape Fear Valley Health) |
Why the Equity Is Already Sitting There
Fayetteville owners who bought before 2022 hold the most usable equity, because most of the price gain has already happened. The median single-family price climbed about 54% from 2021 to August 2024, from $155,000 to $239,000, per City of Fayetteville data reported by CityView NC. Current aggregators show a flat market. Medians run between roughly $225K and $265K depending on source and month.
That tension shapes everything. An investor who bought a three-bedroom near Hope Mills a few years back may sit on a large gap between basis and value. Someone who bought last year probably does not. Because most of the price gain already happened between 2021 and 2024, per City of Fayetteville data reported by CityView NC, you can’t count on appreciation to get a newer purchase to the 75% ceiling. Equity has to come from the purchase price, value-add work, or paydown.
The investment property refinance options cover rate-and-term and cash-out paths. How the cash-out works is the place to start if you’re sizing proceeds.
What the 75% Cap and 6-Month Seasoning Mean Here
Cash-out on a Fayetteville investment property is capped at 75% LTV, and most programs want about 6 months of ownership from title recording. Minimum coverage is 1.00, credit tiers start at a 620 floor, and reserves run about 6 months of PITIA. Equity available depends on rent used for lender review, PITIA, reserves, and that ceiling. It is never a guaranteed figure. Smaller balances route through select lenders in the network, and standard programs reach up to $3,000,000.
Flat values change how the cap behaves. Houzeo reports homes selling at 97.94% of asking, and for-sale inventory grew from 390 homes in 2021 to 1,390 in late 2025. Deeper comps and near-asking closings help an appraisal hold up. But the city’s economic development director described the shift as a return to equilibrium, not a seller’s market, so appraisers may weight recent closings conservatively. Model proceeds on a conservative value, not the top of the range.
For a primer on the mechanics, see Lendmire’s DSCR walkthrough. Both are short reads.
Where Single-Family Coverage Gets Tight
A median-priced Fayetteville house does not automatically clear 1.00, and the article that promises otherwise is selling something. Zumper lists some of the more affordable neighborhoods by rent as Terry Sanford at $1,200, Downtown Fayetteville at $1,275 and E E Smith at $1,300. Set a $1,300 rent against a $225,510 average value and the gross rent-to-value lands around 0.55% to 0.6%. That is thin once taxes and insurance join principal and interest.
Run the numbers on a modeled case. Assume a house valued at $240,000 renting for $1,400, refinanced at 75% LTV. Including taxes and insurance, coverage lands below 1.00 in our modeled band. That is a modeled assumption, not a market quote. On a file like that, the structures a lender may review include a sub-1.00 program, interest-only payment structuring, or a lower loan amount. Whether any fits depends on lender guidelines, credit approval, and property review.
The better single-family candidates are lower-basis, well-selected houses, often held long enough that the balance has amortized. Third-party platform Ark7 ranks Fayetteville with the lowest price-to-rent ratio tracked in North Carolina, at 13, and calls it a cash-flow-led market over an appreciation one. Read that as a relative ranking. It is a secondary source.
Duplexes Through Fourplexes: Where the Ratio Improves
Multi-unit stacking is the stronger path to coverage in Fayetteville, because four doors share one price and one loan. RentCafe’s Yardi Matrix data shows average rent of $1,289, up 0.82% year over year, with two-bedrooms at $1,287 and three-bedrooms at $1,614. That data covers only 50+ unit buildings, so small-building rents likely run lower. Zumper’s listing-based two-bedroom figure is about $1,099.
Consider a fourplex of two-bedrooms renting between $1,100 and $1,290 a unit. Gross rent would land around $4,400 to $5,160 a month. Those are modeled inputs. Against a single house near $1,300, the same financing structure spreads across four rent streams, and in our modeled band coverage including taxes and insurance clears 1.00 more comfortably at a price in the mid-$400Ks. Not guaranteed. Sources diverge by about $190 per two-bedroom, so stress the low end.
DSCR programs typically cover single-family homes, condos and 2-4 unit rentals. Manufactured homes, log homes and barndominiums fall outside these programs.
DSCR files in markets like this one typically look like a long-held single-family rental with a modest balance and rent that barely covers full obligations, sitting next to a small multifamily that covers with room to spare. Brokers in military-anchored markets often see the borrower’s real question shift from “can I pull cash out” to “which property should carry the loan.” Running both properties through the coverage math before choosing usually settles it.
Where the Demand Holds Up
Fort Bragg is the demand floor, and the neighborhoods that pencil best sit closest to it or to the medical corridor. A CityView NC column calls the Army the main driver of almost everything that happens in the city. Roth Capital, a secondary source, puts the post at over 52,000 active-duty soldiers plus 10,000+ civilian employees. The post has carried both the Fort Bragg and Fort Liberty names, so confirm the current one if you cite it. Veterans also make up a meaningful share of the city’s residents, which adds a second layer of military-linked housing demand beyond the active-duty base.
Spring Lake and the Bragg Boulevard corridor. Realtor sources describe Spring Lake, along with Hope Mills and Raeford, as consistently appealing to PCS-driven renters. Tenants here are often enlisted soldiers whose housing allowances anchor rents. I’d treat that as a demand story rather than a verified number, since BAH figures should be checked with the Defense Travel Management Office. This corridor is the natural home for small multifamily.
Downtown and Haymount. Haymount is described as walkable and historic, and it sits near Cape Fear Valley Health, a 950-bed, eight-hospital system with more than 9,500 employees by its own count. Demand here leans toward medical staff, officers and young professionals. Zumper’s $1,275 Downtown rent sits inside the band where most local apartments rent. RentCafe shows 71% of apartments at $1,001 to $1,500.
Hope Mills and Rockfish. Affordable suburbs with a mix of newer and older homes, serving family and military tenants. These are lower-basis single-family territory, where coverage depends on buying well.
Fayetteville State University area. Fayetteville State University enrolled a record 7,628 students, with about 2,500 from military families, per CityView NC. Nearby, Fayetteville Technical Community College reports nearly 31,000 students, up 5%. No reliable neighborhood price data exists, so treat this as a tenant-pool observation only.
Renters are 53% of households, and median household income is $56,685 per Census data reported by CityView. A $1,300 rent takes roughly 28% of gross monthly median income by our arithmetic. Rents pushed above the $1,000 to $1,500 band meet resistance. Underwrite inside it.
Is Supply a Problem? (Mostly at the Top)
New apartment supply is the one place competition is visible, and it lands on Class A rents. A city presentation reported by CityView cited an 8% vacancy rate, slightly above a 7% industry standard, with new construction outpacing demand. That figure has no independent confirmation. Rent growth of 0.82% supports flat-rent stress testing. Older workforce-priced units below Class A rents face less direct competition, but the cautious move is to assume no rent growth when sizing a cash-out.
Note what that means for proceeds. A refinance that only works if rents rise will not survive a flat year.
Using the Proceeds
The money is capital for the next deal, which raises a sequencing question. Some investors pull cash from an older, appreciated house and buy a fourplex with it. Others refinance the fourplex to fund a second one. Because Fayetteville values have flattened, the first approach uses equity that’s already been earned. The second relies on rent holding up.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Fayetteville, NC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Investors comparing paths can review DSCR loan options for North Carolina investors. To discuss a specific file, reach Lendmire at 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Fayetteville?
The property’s rent has to cover its full monthly obligation, including taxes and insurance, at a 1.00 minimum in typical programs. Credit tiers start at a 620 floor, and reserves run about 6 months of PITIA. Ownership of about 6 months from title recording is typical. Final eligibility is subject to lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Fayetteville, NC?
Expect a 75% LTV ceiling on cash-out, a rental-income coverage test, and a credit profile at or above the 620 floor. Eligible property types generally include single-family, condos and 2-4 unit rentals. Terms vary by lender and scenario.
Does flat appreciation hurt a Fayetteville cash-out?
It limits it for recent buyers. Zillow shows only a 0.1% gain year over year, so a 2024 or 2025 purchase probably won’t have built much equity. Owners from before 2022 are in a different position, since prices rose about 54% from 2021 to 2024. Proceeds also depend on the appraisal, which may weight recent closings conservatively.
Is a duplex or fourplex easier to refinance than a single-family rental here?
Often the coverage ratio is easier, because several rent streams share one loan. A single house near $1,300 rent runs tight against a mid-$200Ks value. Small multifamily usually renders a stronger number, though small-building rents run below the RentCafe large-apartment averages, so stress the low end.
What documents matter most for a Fayetteville DSCR cash-out review?
Lendmire arranges DSCR investor loans and the core file centers on the lease or rent analysis, insurance, and entity documents. Rental coverage, not personal income paperwork, is the program’s key feature. For LLC-titled properties, eligibility is subject to lender program requirements.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. Lendmire was also a top-ranked workplace in 2025, and its press releases are collected in its newsroom.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow home values, Fayetteville
2. Houzeo — North Carolina Fayetteville
3. CityView NC, housing and rental market
4. CityView NC
5. Census Reporter, Fayetteville
7. Terry Sanford at $1,200, Downtown Fayetteville at $1,275 and E E Smith at $1,300
8. ranks Fayetteville with the lowest price-to-rent ratio tracked in North Carolina, at 13
9. RentCafe, Fayetteville rent trends
11. rothcapital.com — Top Employers in the Fayetteville Metro Fort Liberty and Beyond
12. Fayetteville State University
13. a 2026 Scotsman Guide Top Mortgage Workplace
14. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Loans in Fayetteville, North Carolina: Investor Financing for Fort Liberty, Hope Mills & Haymount, Military Rental Demand & Real Estate Investors · DSCR Cash Out Refinance in Concord, North Carolina: What It Takes to Qualify on $1,900 Rent · DSCR Cash Out Refinance in Kannapolis, North Carolina: The 2026 Guide to Research Campus
Guides: Investment Property Cash-Out Refinance in Fayetteville, NC · Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.