
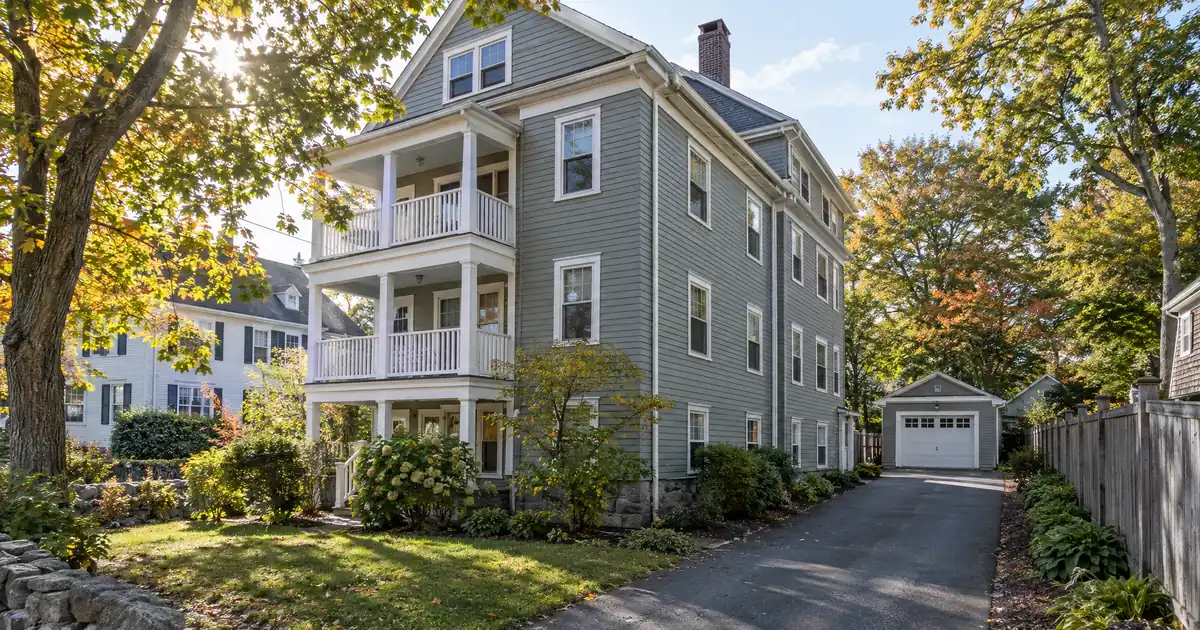
A cash-out refinance on a Haverhill investment property lives or fails on one line: rent divided by full monthly obligation, taxes and insurance included. Redfin shows seven multi-family homes for sale in Haverhill at a median listing price of $745K, while Rentometer puts the typical 2-bedroom rent at $2,498. Two rent checks against one loan is what pushes a Haverhill file toward 1.0x. One rent check against a $570K-plus single-family price usually doesn’t get there.
Lendmire, a non-QM mortgage broker (NMLS# 2371349), works with Haverhill, Massachusetts investors through a DSCR program footprint spanning 40 states plus Washington, D.C. This piece is about the owner who already holds the property and wants to pull equity out for the next deal.
DSCR Cash-Out Calculator
Run the cash-out numbers in Haverhill, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A DSCR cash-out refinance in Haverhill, Massachusetts is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the sequence runs from confirming ownership seasoning and appraised value to testing coverage, sizing reserves, and only then deciding how much equity to take.
- Cash-out is capped at 75% LTV, and seasoning runs about 6 months from title recording.
- Two-family and three-family buildings cover more easily than single-family homes at Haverhill’s $530K median sale price.
- Modeled single-family coverage at median prices, taxes and insurance included, lands well below 1.00x.
- New riverfront apartment supply may cap rent growth, so underwrite flat rents. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
All program figures are typical guidance and subject to lender guidelines, credit approval, and property review.
Why Two-Family Buildings Do the Work
Two-family and three-family buildings are the natural cash-out property in Haverhill because the rental stock is built around small units. Point2Homes reports 10,393 renter-occupied units, roughly 40% of the housing stock, with 4,126 two-bedroom rentals as the largest share and only 1,927 three-bedrooms.
So underwrite a duplex or triplex as stacked 1-2 bedroom units. That is where the deepest renter pool sits, and the appraiser will have plenty of rental comps to lean on. Current listings match the pattern: Victorian-era two-families are common, and the city’s housing stock skews old, with single-family detached homes at just 41.58% of about 26,300 units.
Run the numbers on a modeled duplex valued near the $745K listing median with two 2-bedroom units at $2,498 each. These are modeled assumptions, not a specific property. At 75% LTV, with full taxes and insurance in the obligation, coverage lands just over 1.00x, call it 1.05x rounded down. Now take a single-family home near the $572K median listing price renting at the 3-bedroom figure of $2,755. The same method puts coverage around 0.75x. That’s not a rounding error. It’s a different loan. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Cash-out at 75% LTV on that duplex clears the standard 1.00x baseline only barely, and a 1.05x file has almost no cushion if an appraiser’s rent schedule comes in light. Drop to 65% LTV and coverage climbs to roughly 1.15x, at the cost of less cash out. That’s the core tradeoff. More proceeds mean thinner coverage. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
The Neighborhood Split: Rent per Dollar vs. Appreciation
Downtown and the Washington Square core offer the better rent per dollar for a small-multifamily refinance, while Bradford and the Highlands are priced for appreciation. Homes.com shows downtown single-family medians near $487,500, against about $718,500 in Bradford Greens and $749,000 in the Highlands. Those are directional figures from a listing portal, not appraisals.
Bradford is the tension point. Its prices sit far above downtown’s, yet its rents don’t run meaningfully higher. An owner there is holding an appreciation-led asset, and a cash-out at 75% LTV depends heavily on the appraisal supporting the value. Downtown works the other way: lower basis, strong commuter and hospital-worker demand, and the coverage math has more room. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Mount Washington deserves a look for two-family owners. Redfin lists a median listing price of $582K there, with 8 multi-family units for sale in the past month. That’s a submarket where the property type matches the DSCR structure. Riverside and Upper Main Street sit at the lower price points, with condos and older homes. They suit smaller balances, which route through select lenders in the network rather than standard programs.
Rocks Village? Skip it for this purpose. It’s a low-density historic village, and the price trend there has been soft.
Flat Prices Change the Seasoning Story
Haverhill prices are roughly flat, so the equity you pull will come from what you bought below market or improved, not from waiting. Redfin shows a $530K median sale price, up 2.0% year over year, with homes selling in about 22 days and 4 offers on average. Movoto’s listing median was down about 1% over the same stretch.
The six-month seasoning clock, measured from title recording, matters less here than the appraisal. An investor who bought a tired two-family and finished renovations can show value the market didn’t hand over. An investor who bought at the median and did nothing may find 75% LTV leaves little to extract once existing debt is paid off. That equity isn’t a guaranteed figure. It depends on rent used for lender review, full monthly obligation, reserves of about six months, and the LTV ceiling. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
This one’s a genuine toss-up for owners in the middle: a light rehab that lifts value and rents may justify waiting past the minimum seasoning, while a stabilized building with no upside may be better left alone. Refinancing just because you’re eligible isn’t a strategy.
What the New Apartments Mean for Your Rent Schedule
New supply near the rail stations may cap rent growth on renovated 1-2 bedroom units nearby, and the evidence is mixed rather than alarming. The Beck opened as a 290-unit, 97% market-rate development beside Bradford Station, and Harbor Place downtown adds 80 units, 24 of them market-rate. Larger downtown redevelopment is also in the pipeline, with the city’s current projects page tracking downtown and riverfront work.
Rent aggregators disagree on the direction. Some show citywide averages slipping while others show gains. Treat that as mixed evidence, not a confirmed oversupply.
The practical response is to underwrite at flat rents. If your refinance only works with a rent bump, the file is fragile. Check what an appraiser’s rent comps will show before ordering anything. Owners near Bradford Station and downtown face the most direct competition from the new buildings, while older stock away from the rail corridor competes on price rather than amenities.
What Working Brokers See in Older Mill-City Markets
Working DSCR brokers see a recurring pattern in older mill-city markets like Haverhill: the appraiser’s rent schedule, not the owner’s actual leases, sets the coverage number. Owners with below-market legacy rents on long-tenured units often find the refinance works better than expected, since the appraisal can support market rent. Owners who’ve been pushing rents up find the opposite when comps come in lower. Pulling recent comparable rents into the file before submitting prevents most surprises.
Who Should Take the Cash and Who Shouldn’t
DSCR cash-out fits the investor who is buying the next building in the same corridor. Pulling equity from a Haverhill duplex to acquire another two-family near the commuter rail, where coverage still clears 1.0x, is a straightforward use of proceeds. Cash-out refinance mechanics are simple when the next deal covers itself.
It’s a different decision if the proceeds go into a market where the math doesn’t pencil, or into a single-family Haverhill purchase that would sit near 0.75x on its own. A portfolio with one cash-flowing duplex and one negative-coverage property isn’t diversified. It’s subsidized.
Conventional financing may be the better lane for a W-2 owner with one or two rentals and clean traditional personal-income documentation. Where DSCR and conventional diverge is mostly about documentation and portfolio count, and conventional can carry a lower cost when personal income supports it. DSCR becomes more practical for LLC-held buildings (subject to lender program eligibility), self-employed owners, or portfolios past the conventional financed-property limit.
If coverage lands below 1.00x, a sub-1.00 program, interest-only structuring, or a lower LTV are options a lender may review. Each has tradeoffs. Expect lower leverage, stronger credit requirements, and possibly different pricing. Qualification stays subject to lender guidelines, credit approval, and property review. If an owner needs sub-1.00 on every building they own, that’s a signal to reconsider what they’re holding, not which loan to use.
The Demand Anchors Behind the Rents
Haverhill’s tenant base rests on healthcare, a community college, and Boston commuters. Northern Essex Community College has its main campus in Haverhill with enrollment in the range of 4,300 to 4,700, and it recently launched a paid surgical technology apprenticeship with Merrimack Health Haverhill Hospital. The hospital is part of a newly formed regional system that includes Lawrence General and the Holy Family campuses. The city itself sits about 35 miles north of Boston, with a commuter rail line running through both downtown and Bradford, and city-data.com puts the population at 68,291.
None of these anchors produces a published headcount in the research, so keep the claim modest: steady, diversified demand for 1-2 bedroom units near the stations, not a boom.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Haverhill?
The property’s rent used for lender review has to cover its full monthly obligation, with 1.00x the standard baseline. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Eligibility varies by borrower, property, and lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Haverhill, MA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Haverhill, Massachusetts?
Most standard programs cap cash-out at 75% LTV, with loan amounts up to $3,000,000, and require rental income that supports the debt. Smaller balances route through select lenders. Manufactured homes, log homes, and barndominiums fall outside these programs. Confirm current details through Massachusetts DSCR investor loans or a direct quote.
Does a Haverhill duplex really cover better than a single-family rental?
Yes, usually. A modeled duplex near the multi-family listing median lands near 1.05x with taxes and insurance included, while a single-family home at the median listing price lands well under 1.00x. The flip point is a single-family in the low price tiers, such as Riverside condos, where the numbers can work but balances are smaller.
Can a self-employed investor buying in Haverhill be reviewed for DSCR financing?
Yes. Lendmire arranges DSCR investor loans, and the files are underwritten primarily on the property’s rental income rather than personal income documents. That structure often suits self-employed owners, subject to program terms.
How long should I wait before refinancing a Haverhill rental?
The minimum is about 6 months from title recording, but waiting longer can make sense when renovations are still lifting appraised value. Flat local pricing means appreciation alone probably won’t create much equity, so let improvements and rent stabilization do the work first.
Where This Leaves Haverhill Owners
Start with the refinance pathway that fits the building. The refinance pathway for investor properties covers the cash-out and rate-and-term choices, and Lendmire’s DSCR walkthrough explains how coverage is calculated. Owners ready to test a specific building can get a rental-income loan quote or call 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
The Haverhill investors who pull equity from stabilized two-families near the rail stations and reinvest it in the next building that covers itself will come out ahead.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, spanning 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. The brokerage places loans through wholesale investor lenders and is not a direct lender. It was recognized by Scotsman Guide as a 2026 Top Workplace, and also named a 2025 Scotsman Guide Top Workplace, as covered in the 2026 Top Workplace recognition announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin Haverhill Multi-Family Listings
3. Redfin Haverhill Housing Market
4. Point2Homes Haverhill Average Rent
5. NeighborhoodScout — Haverhill Real Estate
8. Redfin — Mount Washington New Listings
9. The Beck opened as a 290-unit, 97% market-rate development beside Bradford Station
10. Harbor Place downtown adds 80 units, 24 of them market-rate
11. City of Haverhill Current Projects
12. recognized by Scotsman Guide as a 2026 Top Workplace
13. a 2025 Scotsman Guide Top Workplace
14. the 2026 Top Workplace recognition announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Haverhill, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.