
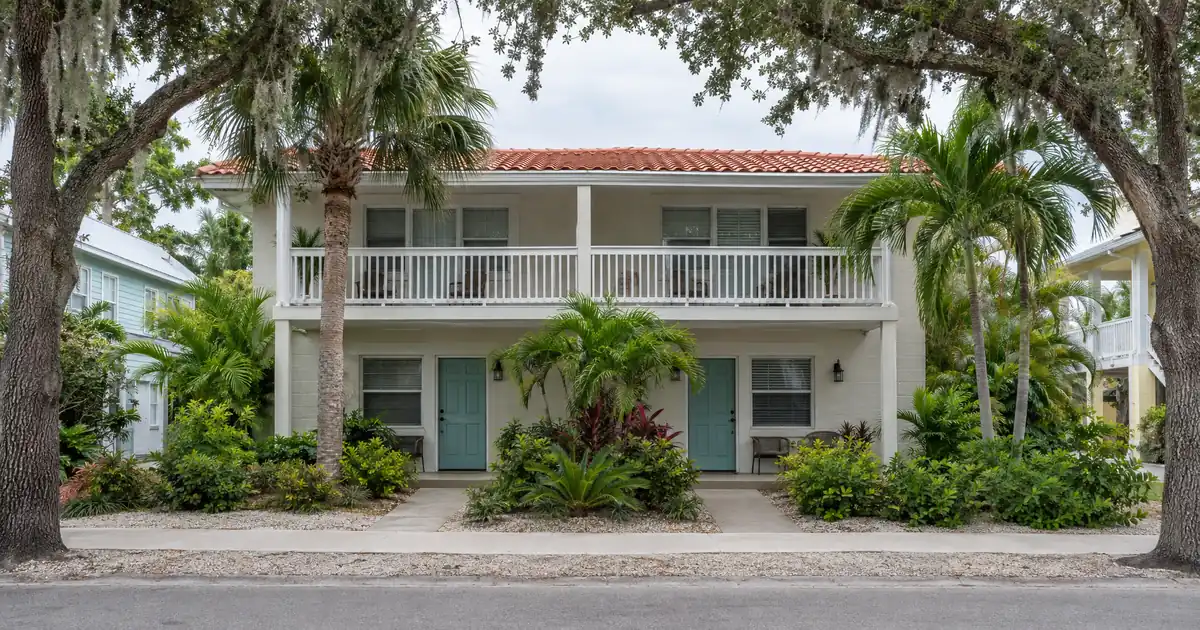
The objection to this market is fair. With a median sale price of roughly $1.4 million per Redfin, a standard single-family rental in Islamorada will not cover its own debt on rent alone, and a cash-out refinance built on that assumption will stall. This article takes that objection head-on. The real question is which properties can support an equity pull, and what the borrower does with the proceeds.
DSCR Cash-Out Calculator
Run the cash-out numbers in Islamorada, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance:
A DSCR cash-out refinance in Islamorada, Florida suits investors who already own a rental and can show rents against the full monthly obligation, and it suits multi-unit or workforce owners better than single-family holders, since the median home sells near $1.4 million.
- Cash-out caps at 75% LTV, with about six months of seasoning from title recording.
- The standard benchmark is 1.00x coverage, and median single-family homes typically land well below it.
- Small multifamily is rare here, which is why unit-by-unit rent comps matter.
- Smoothed value indexes are flat to slightly negative, so underwrite to rent and appraisal, not momentum.
Real estate investors buying in Islamorada, Florida can work with Lendmire (NMLS# 2371349) to access DSCR programs across a 41-market footprint that includes D.C. For owners who already hold property here, the useful question is how much equity is realistically accessible and whether the redeployment target justifies the cost.
Islamorada Market Snapshot
A quick read on the Islamorada investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 25 sales (Redfin, Islamorada housing) |
| Typical rents | ~$2,995 (WLRN, Monroe County workforce) |
The Coverage Problem, in Numbers
Median-priced single-family homes here run well under 1.00x coverage at the 75% cash-out ceiling. The gap between price and rent is the defining feature of the market. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Run the numbers on a modeled example. Assume a house appraised at $1.4 million, rented at the Homes.com median of $5,700, financed at 75% LTV. Counting taxes and insurance, coverage lands around 0.6x. Use the single-family listing median of $3,275 and it drops closer to 0.4x. Even at 50% LTV, the $5,700 rent does not clear 1.00. These are modeled assumptions, not sourced deal data. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The rent sources also disagree. Zumper shows an average near $5,000, while Homes.com’s median sits above its own single-family and condo medians, which points to a mix skewed toward luxury or furnished listings. Portal averages are starting points. The lender’s appraisal rent schedule is what actually counts.
Most standard DSCR programs are built around a 1.00x benchmark, because rent covers the obligation at that level. Some lenders review lower-ratio scenarios, but those usually require lower leverage, stronger credit, more reserves, or different pricing. Interest-only structures and sub-1.00 programs exist in the network. Whether any fits depends on lender guidelines, credit approval, and property review.
Should You Use a Sub-1.00 Structure Here?
Sub-1.00 is the base case in Islamorada, not an exception. That does not make it automatically wise.
If you hold a property with real scarcity value and plan to keep it for the long term, a lower-leverage cash-out that accepts thin current coverage can be defensible. The value case rests on replacement difficulty, not yield. If you are reaching for sub-1.00 because the property doesn’t pencil at any reasonable leverage and you need the cash to rescue something else, stop and re-examine the holding. The flip point is what the proceeds do: buying another asset that covers itself is sound, while covering a shortfall on this one is not.
Conventional financing deserves a look for a borrower with strong traditional employment income and one or two properties, since personal income can carry a low-coverage property that DSCR underwriting would not. The comparison gets decisive once entity ownership, portfolio count, or self-employment complicates personal documentation.
Where Multi-Unit Changes the Math
Small multifamily is the only realistic way to lift coverage, and it is scarce. NeighborhoodScout puts duplexes and small buildings at about 5% of the 3,080 housing units, and Redfin’s recent activity counts only five multi-family properties against 23 single-family sales in a month.
Consider a scenario with a modeled duplex appraised at $1.4 million, each side renting at the single-family listing median of $3,275. Combined rent of $6,550 at 75% LTV, including taxes and insurance, produces coverage in the low-0.7s. At 50% LTV it approaches the 1.00 benchmark. The pattern holds: more units lift coverage, but leverage has to come down to meet the benchmark. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
There is no published market benchmark for Islamorada duplex or fourplex rents. Any multi-unit cash-out file needs its own unit-by-unit comps, and the appraiser’s rent schedule will drive the result.
Submarkets Worth Knowing
The Village spans roughly mile markers 72.5 to 90.8 across several keys. No source breaks rents or prices out by key, so the analysis below is about tenant base and demand, not neighborhood price tiers.
Upper Matecumbe Key is the commercial core, with retail, restaurants, marinas, and the Morada Way Arts & Cultural District. It has the densest job base and the best fit for workforce rentals near employers. The village itself points to the local charter fleet as a defining industry, with what it describes as perhaps the world’s highest density of professional offshore charter boats. The Wet Net Villas development, 36 units built as 18 duplexes at Mile Marker 81 with a waiting list, signals unmet workforce demand. It also shows what private landlords compete with at the lower end.
Plantation Key sits closest to Baptist Health’s Mariners Hospital in Tavernier, the nearest acute-care hospital. Nurses, technicians, teachers, and service workers are a modest but real tenant pool. Plantation Key School serves the area.
Windley Key is narrow and mostly quiet, but Habitat’s Windley Point adds eight rental units and eight ownership units to the workforce mix.
Lower Matecumbe Key leans toward higher-end homes and resort use. It is the hardest place to make a coverage case.
Employment context is thin but sourced. Monroe County’s labor force was about 50,075, with 48,525 employed, and tourism drives the economy. The Village has roughly 7,000 residents per Census data. No published employer headcounts exist for individual Islamorada businesses, and there is no college campus or hospital inside village limits. Demand here is workforce-driven and modest in volume.
Appreciation Is Not the Thesis
Don’t build a cash-out on the headline price gains. Redfin’s housing-market page shows a median of $1.4 million, up 52.6% year over year, while price per square foot fell 25.4%. That is a small-sample artifact: only 25 homes sold that month. Zillow’s smoothed index, which carries a different methodology and a typical value near $1.43 million, shows values down 3.1% over the past year.
Competing sources pointing in opposite directions means the honest read is flat, with high volatility. Size the loan off the appraised value and the rent, and treat any appreciation as upside.
Appraisal variance is the related risk. Homes here average 139 to 161 days on market depending on the source, listings range from $386,000 to $42 million, and comparable sales are few. Expect conservative appraised values and leave an LTV cushion beneath the 75% ceiling. The cash-out refinance walkthrough covers the mechanics.
Seasoning, Reserves, and What Is Available
Cash-out eligibility generally requires about six months of ownership measured from title recording. LTV tops out at 75%, and standard programs run up to $3,000,000 in loan amount. Credit tiers typically start at a 620 floor, with better terms at 660, 680, and 700. Reserves typically run about six months of the full monthly obligation, rising to about nine months on balances above $1,500,000. That last threshold matters here, since many Islamorada loans will cross it. Reserve requirements are the piece Keys investors most often underestimate.
Available equity depends on the rent used for lender review, the full obligation, reserves, and the 75% ceiling. It is not a fixed figure. See how the math pencils before assuming a number.
Manufactured homes, log homes, and barndominiums fall outside these programs. Investors should also verify current local rental rules, taxes, and insurance with qualified local professionals before sizing any deal.
What Deal Desks Tend to See
In markets like this one, where listing data conflicts and comps are sparse, the cleaner files usually lead with a lease or rent schedule that matches the appraiser’s assumptions. The common friction point is a borrower who sized the cash-out off portal rents, then finds the appraisal rent schedule comes in lower. Files that arrive with unit-level rent documentation and a clear plan for the proceeds tend to have fewer surprises. While other non-QM platforms add state-specific overlays that shrink usable LTV, Lendmire works with wholesale lenders to match each file to the program where leverage and coverage line up best. Reserves, credit tier, and property review all factor in, and the refinance side covers the rest.
Investors can review Lendmire’s Florida DSCR platform or call 828-256-2183 to talk through a specific holding.
Redeploying the Proceeds
The cash-out thesis depends on where the money goes. If proceeds fund another rental in a submarket where coverage clears 1.00, the argument is straightforward. If they fund a low-coverage purchase in the same thin-margin segment, the portfolio’s blended coverage weakens, and a second sub-1.00 asset is a different bet than the first.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Islamorada, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
A sound redeployment might be a small multifamily asset elsewhere in the network that covers itself, which reduces reliance on Islamorada’s price-to-rent gap. The choice flips if you hold Islamorada property for lifestyle or long-term scarcity value, in which case leaving equity untouched may be the right call.
Frequently Asked Questions
Can an Islamorada single-family rental qualify for a DSCR cash-out refinance?
Sometimes, but the structure usually needs to change. At median prices, rent on its own typically falls well below the 1.00x benchmark, so lower leverage, a sub-1.00 program, or an interest-only structure may come into play. Whether any of those applies depends on lender guidelines, credit approval, and property review.
How long before I can pull equity from a property I just bought in Islamorada?
About six months of ownership, measured from title recording, is the typical seasoning threshold. The 75% LTV ceiling still applies after that, and with few comparable sales here, the appraised value may come in conservatively. Plan for that variance. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Why do Islamorada rent figures look so inconsistent?
Portals draw from different listing pools. Homes.com shows a $5,700 median across 34 listings, Zumper averages about $5,000, and some portals skew toward furnished or luxury stock. Use the appraiser’s rent schedule, which reflects long-term lease comps, for underwriting.
Does the workforce housing shortage help a long-term rental owner?
It supports demand, but it does not fix coverage. Wet Net Villas has a waiting list, which points to unmet workforce need. Those units are below-market competition at the low end, though, and no rent data exists for them.
Are duplexes easier to refinance than houses here?
They often cover better because two rents stack against one obligation. Inventory is small, and there is no market rent benchmark for them, so each file lives or dies on unit-level comps.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, which are 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios, subject to lender program eligibility. Lendmire places loans through wholesale investor lenders and is not a direct lender. It is a 2026 Scotsman Guide Top Mortgage Workplace and was recognized by Scotsman Guide in 2025.
The mispriced corner of Islamorada is the small multi-unit building on Upper Matecumbe Key near the marinas, restaurants, and charter docks, where scarce supply and a documented workforce shortage matter more than a headline median price that barely reflects those assets.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. WLRN, Monroe County workforce
4. Zumper
5. NeighborhoodScout — Islamorada Real Estate
6. Redfin — Islamorada Village of Islands New Listings
8. islamorada.fl.us — Why Islamorada Matters
10. careers.baptisthealth.net — Baptist Health Careers in the Florida Keys
11. keysnews.com — Tourism Economy Remains Healthy in Keys
12. U.S. Census Bureau (census.gov) — QuickFacts
13. Zillow — Home Values Islamorada FL
14. Homes.com — Islamorada FL Houses for Sale
15. a 2026 Scotsman Guide Top Mortgage Workplace
16. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Loans Key West & Florida Keys: Investor Financing for Old Town, Islamorada, Marathon, Big Pine Key & Real Estate Investors · DSCR Cash Out Refinance in North Miami, Florida: What It Takes to Qualify on $2,400 Rent · Cash Out Refinance Investment Property in Lauderdale Lakes, Florida: The 2026 DSCR Guide to State Road 7
Guides: Investment Property Cash-Out Refinance in Islamorada, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.