
Two sources, one city, and a wide gap. Zillow’s smoothed value index puts a typical Joliet home at $255,981, up 1.9 percent over the past year, while Redfin’s sale-price data shows a $310K median, up 11.7 percent. For anyone planning a DSCR cash out refinance on a Joliet rental, that spread matters more than either number. The appraiser’s comps set the value, the value sets the loan, and the loan sets the proceeds.
DSCR Cash-Out Calculator
Run the cash-out numbers in Joliet, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance in Joliet, Illinois is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds generally capped at 75 percent of appraised value and a seasoning period of about six months, so the appraisal and the lease income carry the file rather than traditional personal-income documentation.
- Citywide price sources disagree, so a conservative appraised value is the safer planning input.
- Duplexes trade near single-family prices but collect two rents, which is how coverage clears 1.00.
- Single-family at median price tends to land below 1.00 on modeled full-PITIA math.
- Cathedral Area and downtown hold the scarce older two- to four-unit stock.
- The lender relies on the appraiser’s rent schedule, not a citywide rent median.
Lendmire is a non-QM mortgage broker that arranges DSCR investor loans through wholesale channels. Lendmire’s DSCR program footprint covers Joliet, Illinois as part of a 41-market reach that includes Washington, D.C. This piece stays on the equity-extraction side. It assumes the reader already owns the property and wants to know what the file looks like when the goal is pulling capital out.
Joliet Market Snapshot
A quick read on the Joliet investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 2,912 total (Wikipedia, University of St. Francis) |
| Employment | 35% healthcare and retail jobs (Federal Reserve Bank of Chicago) |
Which Value Number Will the Appraiser Use?
None of the headline figures, exactly. The appraiser builds value from closed comparable sales, and Joliet’s comps are spread wide. Resideline shows recent closings spread across a broad band, with the middle half of sales covering a wide range and a median that sits near the center of it. Plan the refinance on a conservative value inside that band.
Run the sources side by side. Redfin’s $310K median and Resideline’s $305,000 median sit close together. Zillow’s index is lower and flatter, and the Census-based figure on a market source is lower still at $248,600. The gap suggests that part of the recent gain in sale-price medians comes from sales mix, meaning more larger and newer homes closing, rather than every block appreciating in step. An appraiser working from actual comps can come in under a headline “up 10 percent” story. It happens.
The 75 percent ceiling applies to the appraised value, not to what an owner paid or hoped for. Any shortfall in the appraisal passes through to proceeds at three-quarters weight, and the file still has to hold coverage on the smaller loan. The program also looks for roughly six months of ownership measured from title recording, so an owner who bought a Joliet duplex in the lower part of the price band and has held through the seasoning window has the cleanest equity case.
Downtown deserves its own caution. Redfin’s City Center data shows an enormous year-over-year jump in median sale price, but it is a thin-sample swing and not a trend. Underwriting a refinance on a single outlier month is how borrowers end up with a value that doesn’t survive review.
Duplex Math vs Single-Family Math
Duplexes carry the coverage in Joliet and median-priced single-family mostly does not. A duplex trades near the price of a typical house but collects two rents. On modeled full PITIA including taxes and insurance, a $300,000 duplex at 75 percent LTV lands roughly between 1.05 and 1.45, depending on which rent source a reader trusts.
The pricing evidence comes from a broker blog citing Redfin sales, which showed recent duplex and two-flat sales between about $274,000 and $320,000. That includes a brick two-flat with separate HVAC and a single-story duplex built in 2008. These are directional examples, not a median. Homes.com showed 19 multi-family listings in a snapshot, priced from $175,000 to $1,200,000. Inventory is thin.
Rent sources in Joliet conflict, and the conflict drives the math. Apartments.com reports an average of $1,126, Redfin’s rental page shows $1,260 and a market source shows $1,237. Zumper lists $1,900, up 19 percent year over year. That last figure is almost certainly a listing-mix artifact (more large houses on the market, not a rent surge). RentCast data for ZIP 60432 shows 2-bedrooms near $1,570.
Run the numbers on a modeled $300,000 duplex at 75 percent LTV. The rents below are assumptions drawn from each source and applied per unit, not a claim that every unit rents that way:
| Per-unit rent assumption | Source basis | Modeled coverage |
|---|---|---|
| $1,126 | Apartments.com average | about 1.05 |
| $1,260 | Redfin average | about 1.2 |
| $1,570 | RentCast, ZIP 60432 2BR | about 1.45 |
Every band includes taxes and insurance, and each is rounded down. Now flip to single-family. A modeled $305,000 house at the same 75 percent LTV, renting for $1,570, lands in the 0.7s. Even at the outlier $1,900 rent it only reaches the high 0.8s. Skip that one on coverage alone.
Where a file lands under 1.00, a lender may review other structures: a sub-1.00 program, an interest-only option or lower leverage. Those come with different pricing, tighter leverage or more cash left in the deal, and every one is subject to lender guidelines, credit approval and property review. The 1.00 benchmark is common because rent covers the payment at that level. Below it, outcomes depend on compensating factors, not on a rule. For a deeper look at how the ratio is built, see the guide “What Is a DSCR Loan”.
Cathedral Area and Downtown: Where the Two-Flats Live
The Cathedral Area is the best small-multifamily submarket in the research and the one most likely to produce a clean cash-out file. Redfin reports about 5,400 residents and 3,234 jobs in the neighborhood, with a walk score of 67 and a median multi-family listing price of $329K. Homes.com describes early-1900s stock in Victorian, Tudor and bungalow styles. The broker blog above cites a Zillow neighborhood median of $260,639 for Cathedral, which reflects mostly single-family sales and sits well under the multi-family listing price.
Scarcity is the structural point. City-Stats puts single-family at 79 percent of Joliet’s housing, so older two- to four-unit buildings are limited and tend to hold their value. That helps appraisers find a comp, but only when the right comps exist. Plan for a wide appraisal range, because a few active listings in a snapshot don’t make a deep comp pool.
The tenant base follows employment and education anchors. The University of St. Francis runs a guaranteed-admission pathway from Joliet Junior College, which calls itself one of the largest employers in the Will County area. Saint Joseph Medical Center sits downtown-adjacent and changed hands when Prime Healthcare took ownership from Ascension. Ownership transitions bear watching, though they are an employer-continuity item and not a rental-demand red flag.
Downtown has a policy tailwind. The City and RTA adopted a transit-oriented plan around the Gateway Transportation Center, and the mayor tied it to the need for more housing variety downtown. The Joliet City Center Partnership notes a JJC City Center campus and a courthouse that opened in late 2020. That supports daytime employment near the station. It is a planning intention, not a guaranteed rent lift, and an appraiser will not credit it.
South and Southeast Joliet (Cash Flow With Strings)
South and southeast Joliet offer the highest rent-to-value ratios and the highest execution risk. The broker blog’s Zillow neighborhood medians run from $145,919 in Southside and $174,060 in Southeast Joliet up through St. Pat’s at $200,246, St. John’s at $207,971, Cunningham at $217,992 and Reedwood at $231,958. If rents are broadly similar across the city, the $150K to $175K pockets carry the strongest coverage on paper. That is inference, not sourced rent data, and it needs property-level lease comps.
Here is the math at a modeled $175,000 value and 75 percent LTV, using the $1,237 Census-based rent. A single-family unit lands right around 1.0 including taxes and insurance, and I’d round it down. At Apartments.com’s $1,126 it sits in the low 0.9s.
The tradeoff is condition and exit. Lower-priced stock tends to carry deferred maintenance, and a cash-out file in these pockets can pick up appraisal conditions on the roof, mechanicals or safety items. Exit liquidity is also thinner, since a lower-priced pocket draws fewer buyers at resale. Is the extra coverage worth the extra review friction? It’s a genuine toss-up. Investors chasing yield on a smaller balance may say yes, while investors who want a clean appraisal in the Cathedral Area may reasonably say no.
Smaller balances in these pockets can also route through select lenders in the network, since standard programs are built for larger loan sizes (up to $3,000,000 on the high end).
The I-80 Belt and the Logistics Renter
The I-80 corridor, Ingalls Park and the east-side industrial belt serve a workforce tenant base tied to freight, warehousing and refining. That demand is real, and it is also concentrated. Data USA lists Retail Trade at 10,157 resident workers, Health Care and Social Assistance at 9,660 and Transportation and Warehousing at 9,070. Data Commons reports a population of 150,445 and unemployment of 5.3 percent.
The employer list is dated but informative. A Patch summary of the city’s financial report ranked Amazon first at about 3,500 workers, with ExxonMobil’s refinery at 680. Those headcounts come from an older reporting year, so use them for ranking and not as current counts. The Federal Reserve Bank of Chicago describes CenterPoint Intermodal at 3,600 acres and almost 20 million square feet of industrial space, one of the largest inland ports in the country. That profile is also dated, but the freight infrastructure hasn’t gone anywhere.
Ingalls Park sits between Pilcher Park and I-80 and had 3,460 residents at the last census. I found no reliable rent or vacancy data at the neighborhood level, so coverage here depends almost entirely on purchase price and whatever the appraiser’s rent schedule supports. For cash-out, that means a borrower who bought low has equity, and a borrower who bought at the top of the local band may not.
One supply signal belongs in the file notes. Shaw Local reports that residents are moving into The View apartments at Rock Run Collection, near the I-55 and I-80 crossing, alongside a hotel under construction. That adds retail and hospitality jobs and some new-build competition for nearby Class B rentals. I have no sourced unit count or rent figure for it, so treat it as a benchmark to check, not a forecast.
The Plumbing: What Slows a Joliet Cash-Out File
Most delays on a cash-out file come from documentation, not from the market. The appraiser’s rent schedule (Form 1007 for single-family, Form 1025 for two- to four-unit buildings) is the document that drives the coverage number, so a citywide median rent doesn’t substitute for it. The items that matter on a Joliet file:
- Title and seasoning. The roughly six-month clock runs from title recording, so a recent deed transfer or a quitclaim into an LLC can reset the question.
- Leases and rent roll. In-place leases for each unit, with the appraiser’s schedule reconciled to them.
- Metering and expenses. Separately metered units lower owner-paid expenses, which is why the duplex examples above are attractive.
- Insurance. A current declarations page, since the coverage ratio includes it.
- Reserves and credit. About six months of PITIA in reserves (about nine months above $1,500,000), with credit tiers at 620, 660, 680 and 700 and a 620 floor.
- Entity title. LLC-held properties are generally workable, subject to lender program eligibility.
The common friction point in markets like this one is the gap between what the borrower’s spreadsheet assumed and what the appraisal schedule supports. Files from small-multifamily markets with thin comps tend to go smoothest when the owner arrives with leases, utility metering details and a realistic value expectation already in hand, and they stall when the borrower anchors on a headline median. Lendmire’s deal desk tends to see the cleaner files from a documentation standpoint where the property type, rent roll and insurance are all settled before the appraisal is ordered.
Eligibility, as always, is subject to lender overlays and varies by borrower, property and loan scenario. Investors should also verify current City of Joliet and Will County rental rules, taxes and insurance with qualified local professionals.
Where the Proceeds Go
The proceeds are only useful if they land in a better asset than the one they came from. The usual play in Joliet is to pull equity from a seasoned duplex or two-flat and redeploy it into another small multifamily building, since that is the property type where coverage clears most reliably. A borrower who rolls proceeds into a median-priced single-family house at the citywide median is buying a sub-1.00 asset with another property’s equity.
For the mechanics of how the program works, see Lendmire’s DSCR cash-out refinance page. If the choice between a DSCR file and a conventional one is still open, the program-to-program comparison lays out the tradeoffs. Statewide context sits on the hub page for DSCR loans in Illinois. Investors who want to see what a specific property might support can request a quote or call 828-256-2183.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Joliet, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
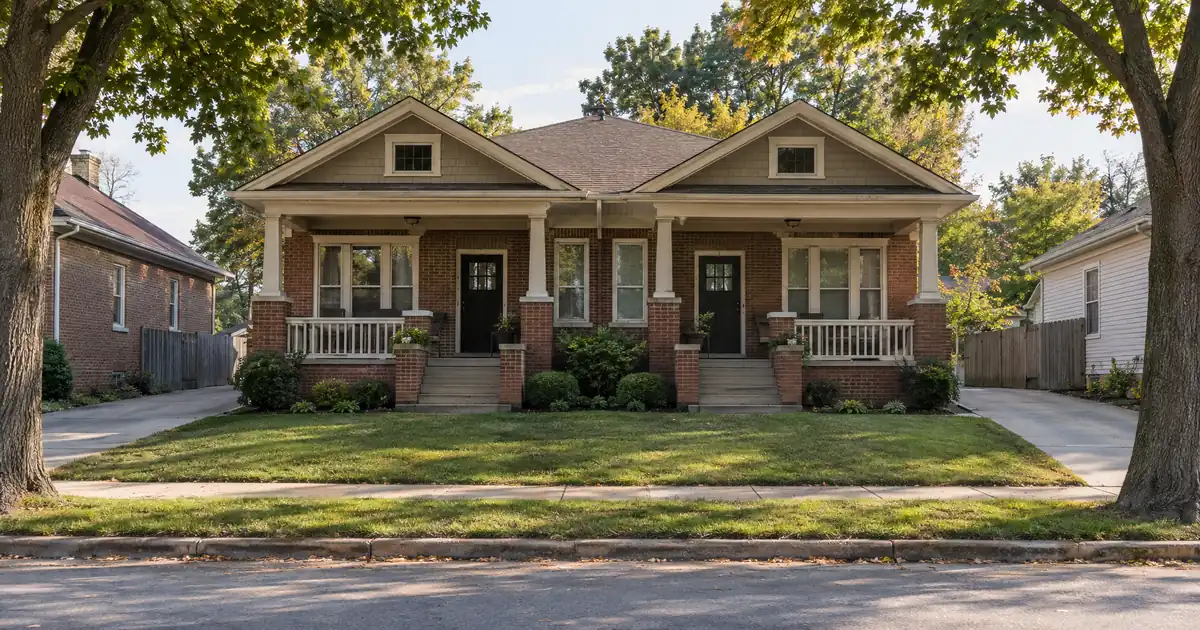
Value in Joliet follows the building and the block. A brick two-flat near the Cathedral Area and a newer single-story duplex trade for similar money, and the cash-out lives or dies on which comps the appraiser pulls.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Joliet, Illinois?
The property’s rental income, measured against its full monthly obligation of principal, interest, taxes, insurance and any HOA dues, has to support the loan. The common benchmark is 1.00, and the borrower generally needs about six months of ownership, a credit score at or above the 620 floor and reserves of about six months PITIA. Final eligibility depends on lender guidelines and the property review.
What are the requirements for an investment property loan in Joliet, Illinois?
Cash-out proceeds are generally capped at 75 percent of appraised value, with the standard program range running up to $3,000,000. Lenders review the appraisal, the rent schedule, title seasoning and reserves, and the credit tiers run 620, 660, 680 and 700. Manufactured homes, log homes and barndominiums fall outside these programs.
Which Joliet submarkets give the best odds of clearing 1.00 on a cash-out?
Older duplexes and two-flats in the Cathedral Area and downtown are the strongest fit, since two rents sit against one purchase price. Lower-priced south and southeast pockets can cover on paper but may add appraisal conditions. Median-priced single-family on the logistics side usually lands below 1.00 on modeled full-PITIA math.
How does a Joliet appraisal affect cash-out proceeds when price sources disagree?
The appraiser uses closed comps, not index values, so proceeds follow whatever value the comps support. With sale-price medians near $305,000 to $310,000 and Zillow’s index near $255,981, the safe plan is a conservative value inside the middle half of closings. At a 75 percent ceiling, appraisal shortfall comes out of proceeds directly.
Can Lendmire help structure DSCR financing for small multifamily investment properties in Joliet?
Yes. The key program feature is that qualification rests primarily on the property’s rental income, subject to lender guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) that arranges DSCR investor loans across 41 markets, Washington, D.C. included, through wholesale and investor-lending channels. The lender evaluates DSCR loans on the property’s rental income and not on the borrower’s personal income, subject to lender guidelines, which suits LLC-owned portfolios, self-employed investors and operators scaling past conventional loan caps. Lendmire is recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin, Joliet housing market
3. Wikipedia, University of St. Francis
4. Federal Reserve Bank of Chicago, Joliet profile
5. Resideline, Joliet housing market
6. Redfin, Cathedral Area multi-family
7. Homes.com
9. Zumper
10. Homes.com
12. Prime Healthcare took ownership
14. Joliet City Center Partnership
15. Data USA, Joliet
17. Patch summary of the city’s financial report
18. Shaw Local
19. a 2025 Scotsman Guide Top Mortgage Workplace
20. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Joliet, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.