
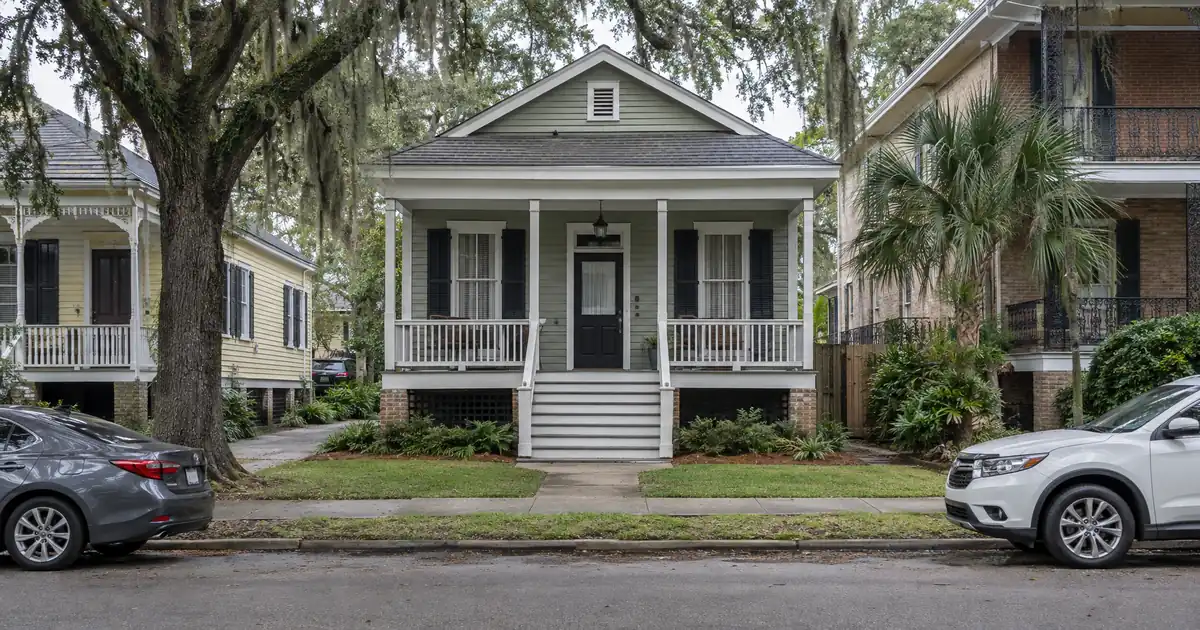
Can a Lake Charles duplex support a cash-out refinance when citywide values are growing slowly? Yes, but the equity comes from the purchase basis and the rehab, not from the market. Zillow puts the average home value at $206,355, up just 2.4 percent over the past year. That means the refinance is underwritten on what the property earns, which is how DSCR files work anyway. The real question is how long the rents hold.
TL;DR: A DSCR cash-out refinance in Lake Charles, Louisiana is underwritten primarily on the property’s rental income measured against its full monthly obligation, taxes and insurance included, with the lender sizing proceeds to a 75 percent loan-to-value ceiling and a seasoning period that runs from title recording.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lake Charles, LA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Rentometer shows 3-bedroom rents far above 2-bedroom rents, which favors 3-bedroom-per-side duplexes.
- Appreciation is modest, so proceeds depend on basis, rehab value, and rent used for lender review.
- LNG construction labor props up demand now and can fade as projects finish.
- Minimum coverage of 1.00x is the baseline; reserves of about 6 months apply, subject to lender guidelines.
Near McNeese, the Duplex Math Starts Here
The Ryan Street corridor beside McNeese State University is the cleanest small-multifamily submarket in the research. McNeese reported fall enrollment of 6,663, up 1.6 percent from 6,556 the year before. KPLC reports that enrollment had slid from roughly 9,000 about 14 years ago to a low of 6,061. The trend is now upward, but the school is smaller than it was a decade ago. Don’t underwrite a campus-adjacent fourplex as if the old enrollment were coming back.
No source in the research gives neighborhood-level duplex or fourplex rents. A listing near campus shows two duplexes (four units) with each unit asking $1,095. That is one asking-price listing, not a market statistic. Treat it as color, then pull your own comps.
What does help is the rent shape across unit sizes. Rentometer reports $1,053 for a 2-bedroom and $1,572 for a 3-bedroom. That is a big step up for one added bedroom. A duplex with three bedrooms per side stacks rent across two doors, and a lender reviewing the file sees two rent lines instead of one. Separate utilities per unit also make the lease evidence cleaner.
Rebuilt Duplexes and What an Appraiser Sees
Hurricane Laura hit as a category 4 storm, per Housing Louisiana, and the older housing stock has been rebuilt in pieces ever since. Duplex listings in the 70601 area describe new roofs and three-bedroom, two-bath units on each side. That is listing evidence, not a market study. It does tell you what product is common: post-storm rehab duplexes.
Here’s the catch for cash-out. A rehab investor often buys low, repairs, and then asks the appraiser to recognize the improved value. With citywide growth at 2.4 percent, the appraisal leans on the as-completed comps and the condition adjustments, not on a rising tide. Closing out the renovation paperwork matters: receipts, permits where required, photos before and after. An appraisal reconsideration is a routine step on older stock, and a packet of recent in-neighborhood sales with condition notes carries the most weight.
Seasoning is the other mechanical gate. Cash-out generally requires about 6 months of ownership measured from title recording, so the settlement statement or recorded deed has to be in the file. Investors who buy, rehab, and expect to refinance at month three get the file kicked back. Loan balances up to $3,000,000 are available on standard programs, and smaller balances route through select lenders in the network. Most Lake Charles duplexes sit well inside that range. Terms are subject to lender guidelines and vary by borrower, property, and loan scenario.
Running the Coverage Numbers
Debt coverage is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. The standard baseline is 1.00x, though exact eligibility depends on credit profile, reserves, and property review. The cash-out ceiling is 75 percent LTV, not the 80 percent used on purchases.
Run the numbers on a modeled duplex valued at $300,000 (an assumed value, not a market figure) at 75 percent LTV, with taxes and insurance built in at Louisiana-average assumptions:
| Unit mix (modeled) | Rent basis | Modeled coverage |
|---|---|---|
| Two 2-bedroom units | $1,053 each | About 1.1x |
| Two 3-bedroom units | $1,572 each | About 1.6x |
| 2-bedroom case, rents down 15 percent | Same basis, haircut | Right around 1.0x |
Those bands round down on purpose and include taxes and insurance. The 3-bedroom case has a lot of cushion. The 2-bedroom case clears but thinly, and a modest rent haircut pushes it to the baseline. If a deal lands below 1.00x on long-term rent alone, the options a lender may review include a sub-1.00 program, interest-only structuring, or a lower-leverage cash-out. Qualification stays subject to lender guidelines, credit approval, and property review.
DSCR files in markets like this one typically look the same on paper: a rehabbed older duplex, modest appreciation, and coverage that clears on the rent schedule but not by a mile. The friction is rarely the ratio. It is the lease evidence (are the leases current, are rents consistent with the schedule), the reserves documentation (about 6 months, and about 9 above $1,500,000), and the insurance quote reflecting the storm-exposed Gulf location. Fresh insurance binders in the file before submission prevent the coverage number from moving mid-review.
Rent growth has helped. RentCafe reports an average apartment rent of $1,127, up 7.46 percent year over year, with 39 percent of households renting. Note the basis: RentCafe covers buildings with 50 or more units. It is an apartment-complex benchmark, not a duplex one, so use it for direction only.
Equity available is not a guaranteed cash figure. It depends on rent used for lender review, the full monthly obligation, reserves, and the 75 percent ceiling.
The LNG Clock
Venture Global’s CP2 terminal is under construction in Cameron Parish with export capacity above 29 MTPA. The Advocate reports roughly 400 permanent workers and about 7,500 temporary construction workers. Woodside’s $17.5 billion Louisiana LNG project is expected to create 8,000 construction jobs, per The Advocate, and Bechtel expects about 5,000 workers at the project’s peak. Leaders for a Better Louisiana projects that construction jobs tied to six state megaprojects peak at 20,500 workers in late 2026 and early 2027, and says Lake Charles demand for industrial construction labor could more than double.
The demand window is real. Woodside targets first LNG later this decade, per its Business Wire release, so construction runs through a typical hold-and-refinance cycle.
The same fact is the risk. Construction rental demand falls away when projects finish. A KPLC report on a GO Group study projected a temporary shortage of about 10,000 housing units in Southwest Louisiana during the last LNG buildout. That study is 11 years old and is not vacancy data. No current vacancy rate for small multifamily turned up in the research. So underwrite on rents that survive the construction peak, not on the peak itself.
Honestly, this is the toss-up for 2-bedroom product. The coverage clears today with workers filling units, but the thin-cushion case has no room to absorb a soft lease-up. The 3-bedroom duplex has more margin, though it also has more exposure to the same workforce.
What Breaks the Pattern?
New supply is the first thing. The 78-unit Benoit Townhomes off Big Lake Road, a $22.5 million project per KPLC, opened as the Louisiana Housing Corporation marked continued recovery after Hurricane Laura. Mid-City Lofts adds more than 500 apartment and retail spaces on the former Lloyd Oaks site. Older workforce rentals near Big Lake Road and Mid-City compete with that new product.
A local agent’s market blog says new construction is also adding supply in Moss Bluff and parts of the I-10 corridor. That is one agent’s opinion, not neutral data. But combined with 2.4 percent value growth, it means the edges of the market are not short on inventory.
Rent gradients matter for comps too. Apartments.com, using CoStar data, ranks Villages of Lake Charles and Stillwood among the most affordable neighborhoods by rent, and Downtown and the Charpentier Historic District among the most expensive. No dollar bands came through, so pull your own neighborhood comps before you trust a coverage number. Downtown sales data is a thin sample and volatile, so it’s no basis for a cash-out value.
Skip the assumption that every Lake Charles submarket behaves like the McNeese corridor.
Hospitals, Plants, and Casinos Hold the Base
The permanent demand underneath the construction bump is the legacy employer base. The SWLA Alliance major employers list shows Lake Charles Memorial Health System at 2,795, Westlake Chemical at 2,000, Golden Nugget at 1,800, L’Auberge at 1,710, and CHRISTUS St. Patrick Hospital at 1,260. It is a regional list, not city-only. Healthcare and the casinos keep tenant demand steadier than any single construction project. Louisiana Economic Development describes the region as a hub for petrochemicals and energy, a logistics port, and a casino and resort sector.
The population backdrop is stable to growing. Census Bureau QuickFacts lists the city at 81,166, and USAFacts shows the metro growing from 200,200 to 243,000, a 21.3 percent increase. The SWLA Alliance states a goal of adding 100,000 residents over 10 years. That is a goal, not a forecast.
Putting the Proceeds to Work
Cash-out proceeds are only useful if the next deal is underwritten as carefully as this one. Investors holding a LLC-titled rental may pursue the refinance in the entity’s name, subject to lender program eligibility, with the operating agreement and articles in the file. Reserves documentation, lease evidence, and an insurance quote are the pieces that most often cause preventable gaps.
For program fundamentals, see the DSCR fundamentals and the side-by-side comparison. Mechanics for equity pulls are covered in pulling equity with a DSCR cash-out, and the broader menu of refinance options is covered separately. The state-level picture lives on the page for DSCR loans in Louisiana. Investors can also reach Lendmire at 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Lake Charles, Louisiana?
The property has to show rent used for program review at or above roughly 1.00x against its full monthly obligation, including taxes and insurance. On most files, a credit score of at least 620, about 6 months of reserves, and about 6 months of ownership from title recording are also needed. Cash-out LTV is capped at 75 percent. All of this is subject to lender guidelines and property review.
What are the requirements for an investment property cash-out loan in Lake Charles?
Expect an appraisal, lease evidence or a market rent schedule, an insurance quote, reserves documentation, and entity documents if an LLC holds title. Credit tiers run 620, 660, 680, and 700, with better tiers generally supporting stronger terms. Loan amounts up to $3,000,000 are available on standard programs, with smaller balances routed through select lenders.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Lake Charles, LA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How much equity can you pull if Lake Charles values are only up 2.4 percent?
It depends mostly on purchase basis and rehab value, not market appreciation. A duplex bought low and rebuilt can appraise well above basis even in a slow market. The 75 percent LTV ceiling and the coverage ratio both limit proceeds, so the cash is never a guaranteed number.
What happens to DSCR coverage when LNG construction ends?
Rents tied to construction labor can soften as projects wrap up, and coverage thins with them. The 2-bedroom duplex case sits close to the baseline after a 15 percent rent haircut. Underwriting on rents that hold after the peak is the safer approach. Current small-multifamily vacancy data was not found.
The Next Two Years
Over the next 6 to 24 months, three indicators will decide how cash-out files read in Lake Charles. First, whether Woodside’s workforce, almost 900 at last report, climbs toward Bechtel’s roughly 5,000 peak. Second, whether Mid-City Lofts and the new affordable townhomes lease up and pull rents on older rentals down. Third, whether McNeese holds its enrollment rebound. The likeliest outcome is that 3-bedroom duplexes with documented rents keep clearing coverage through the construction peak, while thin-margin 2-bedroom files get tougher once the peak passes. Investors who refinance while the megaproject payroll is still ramping will be underwriting on the strongest rent evidence the market is likely to offer.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing, arranging DSCR loans across 40 states plus Washington, D.C., 41 markets in all. Qualification rests on the property’s income rather than personal income documentation, subject to lender guidelines, which suits LLC-held rentals and growing portfolios. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and named a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Value Index, Lake Charles
2. McNeese fall enrollment of 6,663
3. KPLC, McNeese enrollment history
4. Rentometer, Lake Charles metro
6. RentCafe, Lake Charles rent trends
8. The Advocate, CP2 financing
9. The Advocate, Woodside Louisiana LNG
11. Leaders for a Better Louisiana
15. Louisiana Housing Corporation
17. Apartments.com rent trends
18. SWLA Alliance Major Employers List
19. Census Reporter, Lake Charles
20. USAFacts, Lake Charles metro
21. Scotsman Guide 2026 Top Workplace
22. Scotsman Guide 2025 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Lake Charles, LA · Investment Property Cash-Out Refinance in Louisiana
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.