
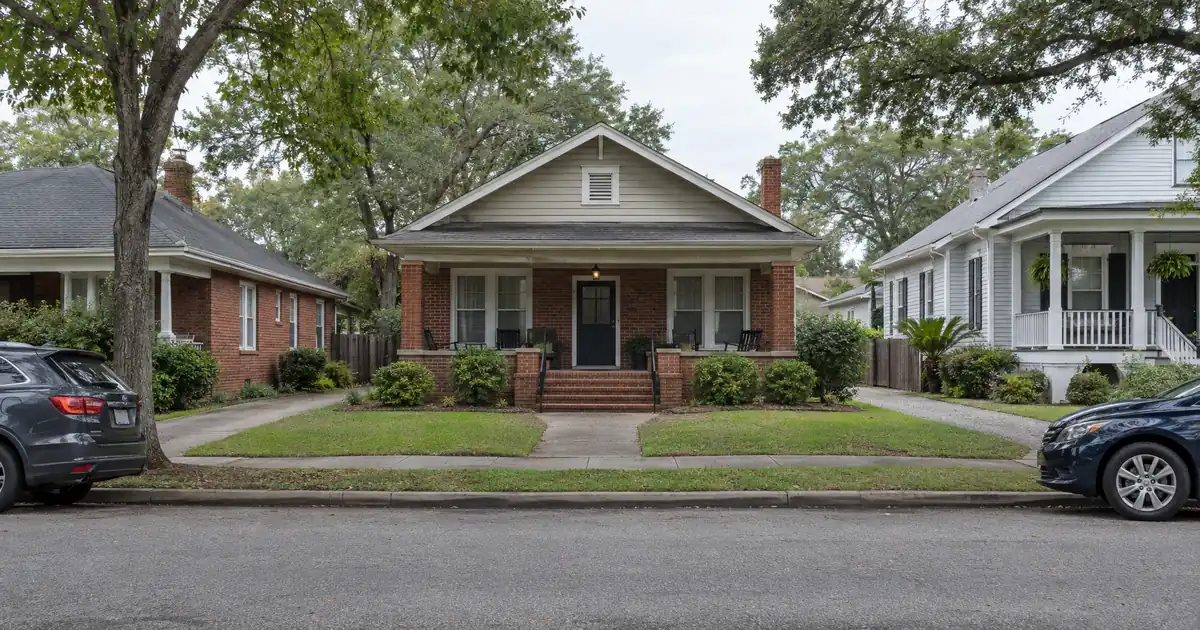
If you own a rental in Perry and assume the cash-out math works because the house has been yours for years, here’s what most brokers skip. In this market, the rent on the lease decides how much equity you can pull, and appreciation decides very little. The 75% LTV ceiling is the easy part. The coverage ratio is where files get reshaped. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
DSCR Cash-Out Calculator
Run the cash-out numbers in Perry, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance in Perry, Georgia is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the process runs from confirming title seasoning and a rent schedule, to sizing the loan under the lender’s leverage cap, to documenting reserves before the proceeds are redeployed.
- House rents of $1,725 (Zumper) to $2,074 (Homes.com) put coverage near 1.0x at 75% LTV.
- Cash-out typically requires about six months of ownership measured from title recording.
- Homes took 98 days to sell versus 59 a year earlier, per Redfin.
- Robins AFB commuters and Emory Hospital Perry staff anchor tenant demand.
- Duplexes are scarce, so proceeds usually flow to single-family or a wider Middle Georgia search.
Perry Market Snapshot
A quick read on the Perry investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | ~$306K median list (Movoto) |
| Recent appreciation | 6.44% avg annual (NeighborhoodScout) |
| Employment | 22,000+ employees (City of Perry) |
Why Equity Math in Perry Is Tight (and Where It Isn’t)
Perry’s price data supports a cash-out only if the lender’s value and the rent both cooperate. The market is soft enough that appreciation shouldn’t carry the thesis, and steady enough that a well-structured file still works.
Redfin puts the median sale price at $297,000, down 2.0% year over year, with price per square foot up 4.0% to $156. That’s a split signal: smaller or better-finished homes held value while the headline median slipped. This article uses the Redfin median throughout. Zillow reads lower on a different methodology, with an average home value of $277,463, up 3.0%. The two disagree on direction as well as level, which says the sample is thin and noisy.
NeighborhoodScout reports average appreciation of 6.44% a year over the last ten years. That’s a long-run number from a city that roughly doubled in population since 2000, per the Census-derived brief. Census Bureau QuickFacts puts the current population near 23,000. Don’t underwrite a refinance on a repeat of that decade. Months on the market lengthened from 59 to 98 days, and appraisers read that the same way.
The stronger play is a cash-out built on a purchase discount or documented renovation value, not market drift. An owner who bought below market and rehabbed has equity that appraisal comps can defend. An owner who bought near the top and is waiting on appreciation may find the 75% ceiling takes a smaller slice than expected.
The Rent Band Decides the Ratio
Perry house rents run from about $1,725 to $2,074, and the spread moves coverage by roughly 0.15x to 0.20x. Underwrite to the low end.
Zumper shows a median across all Perry rentals that sits toward the lower end of the portal readings. Apartments sit well below that: RentCafe lists an average that is modestly higher than a year ago, and most rentals fall in a fairly narrow band at the lower end of the rent range. A rented house competes with those apartments, so don’t assume steep rent growth in the refinance case. Anchor the underwriting to the lower, broader-market reading rather than to figures for newer, larger product.
Run the numbers on a modeled $297,000 value. The rents below are assumptions drawn from the portal medians, and coverage is rent divided by full obligation, including taxes and insurance. Figures are rounded down.
| Modeled scenario | At 75% LTV | At 65% LTV |
|---|---|---|
| House, $1,725 rent | Mid-0.9x | About 1.05x |
| House, $2,074 rent | About 1.1x | About 1.25x |
| Duplex, $215K, $2,526 combined rent | Above 1.5x | Above 1.5x |
The first row is the one that matters. A median-rent house at the full 75% LTV lands just under the 1.00x benchmark. A 1.00x baseline is common because rent covers the full payment at that level. Some lenders will review sub-1.00 files, but expect stronger compensating factors, lower leverage, different pricing, or more cash in reserve. The practical options for that first-row owner are a lower LTV, which the second column shows moving the ratio above 1.0x, or a sub-1.00 program a lender would review case by case. Qualification stays subject to lender guidelines, credit approval, and property review.
This is the central tension in Perry equity extraction. The market gives you more equity than it gives you coverage. A gross rent-to-value near 0.6% to 0.7% means the ratio, not the equity, caps the proceeds. Many owners will find the number clears at a 65% to 70% LTV and misses at 75%. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Seasoning, the 75% Cap, and Reserves
Cash-out on an investment property generally requires about six months of ownership from title recording, a 75% maximum LTV, and a minimum 1.00 DSCR benchmark. Equity available is a function of rent used for lender review, full obligation, reserves, and that ceiling. It is not a guaranteed cash figure.
A few program guidelines matter for Perry files. Reserves typically run about six months of PITIA, so the liquid cash required scales with the obligation, not the equity pulled. Credit tiers run 620, 660, 680, and 700, with a 620 floor; expect pricing and leverage to tighten toward the lower tiers. Standard programs reach loan amounts up to $3,000,000, though Perry balances will sit far below that. Manufactured homes, log homes, and barndominiums fall outside these DSCR programs, which matters on the rural edges of Houston County. LLC-titled properties are workable subject to lender program eligibility, and Georgia owners can review DSCR loans in Georgia for the state-level picture.
If the mechanics are new, the guide “What Is a DSCR Loan” covers how the ratio is built, and the conventional-vs-DSCR tradeoffs explain why an owner with a thin W-2 story and a fully leased house often lands here. The mechanics specific to this loan type sit in Lendmire’s DSCR cash-out refinance page, and the wider set of refi programs covers the rate-and-term alternative for owners who want a lower balance, not cash.
Program details can shift, so confirm current guidelines before relying on any parameter here.
Where the Rental Demand Actually Comes From
Perry tenant demand is employer-driven: military commuters, plant workers, and hospital staff. No four-year university sits in the city. That’s a steadier base than a student market, with a ceiling on how fast rents move.
Robins Air Force Base, about 20 miles away, is cited by the City of Perry as Georgia’s largest single-site employer, with more than 22,000 employees and a $2.7 billion annual economic impact. Perry is a commuter-shed submarket for the base, not an adjacent one, and it competes with Warner Robins on price. The Houston County Development Authority lists Frito-Lay, Perdue Farms, and Jack Link’s among the county’s industrial employers, and it describes the Perry Frito-Lay plant as one of the company’s largest in the U.S. Graphic Packaging operates a Perry carton facility whose first two phases were projected to employ more than 600 people, per Livability. That’s a 2024-era projection, so treat the headcount as directional.
Healthcare adds a third leg. Emory News reports that Houston Healthcare-Perry became Emory Hospital Perry, with more than 2,500 employees and 350 physicians across the two Houston County hospitals and 282 combined beds. Data USA shows resident employment led by retail trade at 1,303, health care and social assistance at 1,297, and public administration at 1,224. The Georgia National Fairgrounds & Agricenter draws almost 1 million visitors a year, per the City of Perry, which supports seasonal and event employment.
Working DSCR brokers see a recurring pattern in small commuter-shed markets like this one: the rent roll looks stable, but the appraisal and the rent schedule come in a notch below what the owner expected. Files that pencil on a seller’s asking rent often settle closer to the market-rent figure on the appraiser’s schedule. The owners who get the full cash-out they planned usually ran the coverage on the low end of the rent range before applying.
Renters are a minority here. RentCafe shows 33% of households, 2,773, renter-occupied and 67% owner-occupied. That’s a small pool, which is part of why the rent data stays thin.
Submarkets Worth Owning In
No reliable neighborhood-level rent or price source exists for Perry, so the submarket case is qualitative. Portals publish citywide figures only, and Zumper itself says Perry lacks the inventory to show neighborhood rents. Anyone quoting a Perry neighborhood rent to the dollar is estimating.
What the sources do support is the shape of each pocket.
Downtown and the historic districts. The Downtown, Swift Street, and Washington-Evergreen historic districts hold older housing and mixed-use infill, according to a local agent summary. Demand likely comes from county and city staff and downtown retail and hospitality workers. Older stock is where a converted or small multi-unit property is most likely to appear, but that’s unverified.
The Northside Drive, Perry Parkway, and Langston Road corridors. These host newer subdivisions. NeighborhoodScout says 54.78% of Perry’s housing was built since 2000, which suggests this is where commuter families rent. Newer product tends to appraise more cleanly, which helps a cash-out.
Morningside Drive and the hospital area. Demand is from Emory Hospital Perry staff. There’s no verified housing data, so it’s a thesis, not a number.
The I-75 and fairgrounds interchange. Part of the city sits in Peach County, a quirk of Perry’s geography. The mix is hospitality, event, and industrial workers. Traffic around fair dates is a known factor.
Big Indian Creek. Some areas near the creek are flagged by Homes.com as flood-prone. Check flood status on any property there before it goes into a refinance file.
Feeder submarkets (Centerville, Byron, and Kathleen) share the Robins commute shed. Honestly, a comparable house in one of them can offer a cleaner comp set than Perry’s thin sales volume, though the owner here is refinancing, not shopping.
Where the Proceeds Go: Small Multifamily Is Scarce
Perry’s rental stock is overwhelmingly single-family, so the next deal probably isn’t a Perry duplex. NeighborhoodScout puts single-family detached homes at 72.49% of housing units, and the most common building type is three- and four-bedroom houses.
A county listing aggregator, Realmo, showed only three active multifamily listings across all of Houston County. One was a renovated two-bedroom, one-bath duplex priced at $215,000. Using RentCafe’s $1,263 average two-bedroom rent for both units gives a combined rent of $2,526, which is where the table’s duplex row comes from. That’s a single listing with an unconfirmed location, so it illustrates the math and nothing more. Coverage near or above 1.5x on a duplex versus the mid-0.9x to 1.1x range on a median house is the gap that makes small multifamily attractive. Comps and rent-schedule support will be hard to find, though. Plan on a wider Middle Georgia search radius.
This is a genuine toss-up. Reinvesting in Perry single-family keeps the owner inside a market they know, at coverage that stays thin. Reaching for a duplex improves the ratio but trades away local knowledge and exit liquidity. Investors chasing the best coverage will lean toward multifamily. Those who value familiar comps will stay in single-family and accept a lower LTV.
What Could Break the Pattern?
Three shifts over the next 6 to 24 months would change the Perry cash-out math. The first is days on market. Redfin shows 98 days, up from 59. If that stretches further, appraisers tighten, and a 75% cap on a lower value pulls less cash. If it reverses, owners holding off on a refinance may find the window better than expected.
The second is rent. Apartment rents grew 2.39% against a house-rent range that spans nearly $350. Modest rent growth is the base case, and a refinance that works only with a rent bump probably doesn’t work. The third is employer news. Perry’s demand rests on a handful of anchors: Robins-linked work, the plant base, and the Emory system. A headcount change at any of them would show up in tenancy before it shows up in price data.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Perry, GA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Appreciation is the variable to lean on least. Zillow and Redfin disagree on direction, and the ten-year average is not a forecast.
Frequently Asked Questions
How much equity can I pull from a Perry rental?
It depends on the lower of two limits: the 75% LTV ceiling and the loan size at which rent covers the full obligation at 1.00x or better. On a median-rent house, the coverage limit often binds first, which is why many Perry files size nearer 65% to 70% LTV. Reserves and credit tier also shape the outcome, subject to lender review.
Does Perry’s soft sales market hurt a cash-out?
It can affect the appraisal. Redfin shows median sale prices down 2.0% and homes sitting 98 days versus 59, so an appraiser may weigh conservative comps. Since Zillow shows values up 3.0%, the sources disagree and the appraisal is the deciding number. Base the plan on the purchase basis or renovation value, not expected appreciation.
Can I use a refinance to buy a Perry duplex?
Yes, in principle, but supply is the constraint. Single-family is 72.49% of housing units and only three multifamily listings showed across Houston County. Expect to search a wider Middle Georgia radius, and expect comp and rent-schedule work to take effort.
Does Robins Air Force Base make Perry a safe rental market?
It makes it a steadier one. The base is about 20 miles away with more than 22,000 employees, and Perry competes with Warner Robins on housing cost. Demand rests on several anchors, including Frito-Lay, Graphic Packaging, and Emory Hospital Perry, not on the base alone.
Do I need six months of ownership first?
Typically yes. Seasoning is generally measured from title recording, at about six months. An owner who recently purchased should plan the refinance window around that date and have the rent schedule and reserves ready before it arrives.
What to Track Over the Next Quarter
Three indicators will tell Perry owners whether to move on a refinance or wait.
- Days on market against the 98-day Redfin figure. A move back toward the earlier 59 days would support stronger appraisals.
- House rents against the $1,725 to $2,074 band. A median that edges up lifts coverage more than any value change would.
- Employer announcements from the plant base and Emory Hospital Perry. Hiring or expansion news at these anchors is the earliest signal for Perry’s renter pool.
Perry’s equity story will turn on rent and appraisal comps long before it turns on a fairgrounds crowd or a county line.
If you hold a Perry rental and want to see where the ratio lands, review my scenario or call 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Two consecutive Scotsman Guide Top Mortgage Workplace recognitions: a top-ranked workplace in 2025 and a 2026 Scotsman Guide Top Workplace, covered in the 2026 industry recognition release.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zumper: Perry rent research
2. Homes.com
3. Redfin: Perry housing market
4. Movoto
9. RentCafe: Perry average rent
10. Houston County Development Authority: Key Industries
11. Livability
12. Emory News: Houston Healthcare integration
13. Data USA
14. City of Perry: Why Do Business in Perry
15. jacqueapplegate.com — Perry Ga Neighborhoods and Everyday Small Town Living
16. Realmo
17. Scotsman Guide — Top Workplaces 2025
18. a 2026 Scotsman Guide Top Workplace
19. EIN Presswire — Lendmire Recognized as a 2026 Top Workplace by Scotsman Guide
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.