
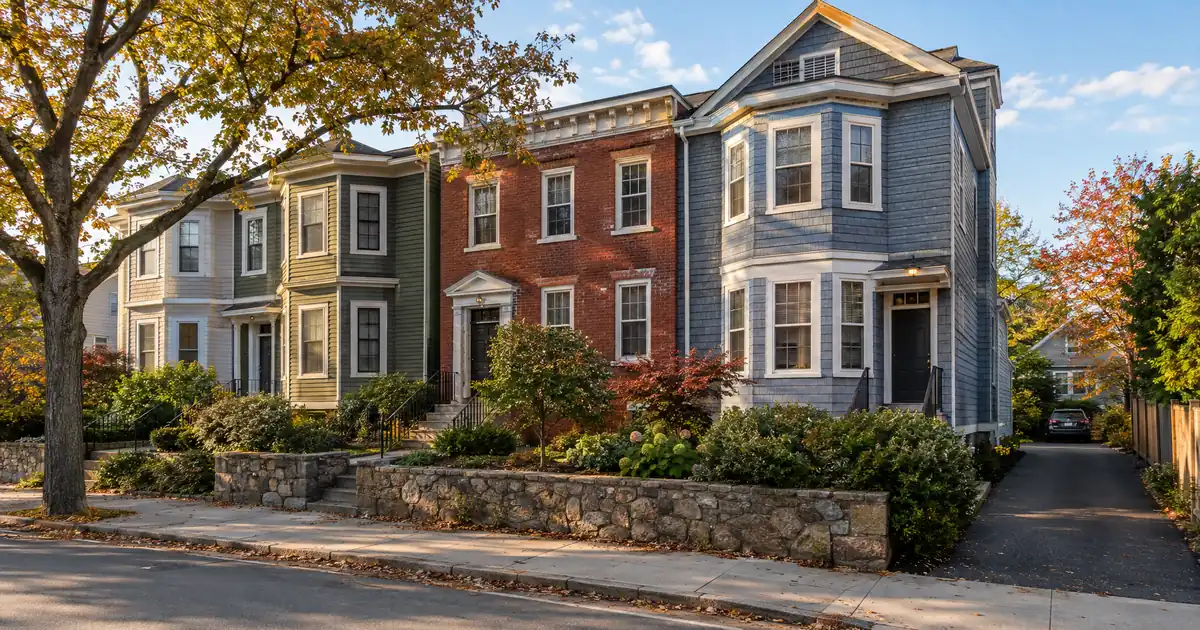
The objection to a Somerville cash-out is easy to state. Prices have drifted down, rents are flat, and the building was probably bought near the top. So where is the equity? It is a fair question. This article answers it with the numbers that decide these files: appraisal variance, multi-unit coverage, the 75 percent ceiling, and what the proceeds are for.
TL;DR: A DSCR cash-out refinance on a Somerville, Massachusetts investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, with equity limited by a loan-to-value ceiling rather than by personal income documents.
DSCR Cash-Out Calculator
Run the cash-out numbers in Somerville, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Median sale price sits near $1.0 million, down 4.6 percent year over year, per Redfin.
- Cash-out LTV tops out at 75 percent, and about six months of ownership is typical.
- Three stacked rents on one deed are what give a triple-decker a chance at coverage.
- Condos and single units in this price band usually fall short of 1.00 on rent alone.
- Qualification is subject to lender guidelines, credit review, and the appraisal.
Where the Equity Actually Comes From
Equity in Somerville is mostly a function of when you bought and what you bought, not of this year’s trend. Redfin puts the three-month median sale price at about $1.0 million, down 4.6 percent year over year, with homes selling in about 21 days. The same page shows price per square foot at $724, up 8.4 percent. Two signals pointing in opposite directions.
Sales volume matters as much as direction. Redfin counted 153 sales in May against 172 a year earlier. That is roughly 150 a month, enough that an appraiser can usually find comps. Thin markets are where cash-out files stall. This is not one of them.
For multi-family, Homes.com showed 63 listings, with asking prices from $849,900 up to $16.95 million. The floor is the point. A duplex or triplex in this city starts near $850,000, so even a modest cash-out lands in jumbo-adjacent territory. Loan size and reserves matter as much as the rent roll.
An owner who bought near the peak should assume the appraisal lands flat to slightly under the purchase price. Underwrite the refinance on today’s rents. Not on hoped-for appreciation.
The Triple-Decker Math (Modeled, Not Quoted)
Stacked rents are the whole argument for small multifamily here. Run the numbers on a modeled triple-decker at the average two- and three-family price of about $1.49 million, per an agent-published summary from Commonwealth Standard Realty Advisors. Assume three units at roughly $3,500 each. That is a modeled rent figure, informed by the Union Square two-bedroom range of $2,950 to $3,700 on Boston Pads, not a quoted schedule.
At 75 percent LTV, coverage on those assumptions, including taxes and insurance, lands around 1.1x. Standard programs are built around a 1.00x benchmark because rent covers the full obligation at that level. A 1.1x file clears it with a little cushion. Not much of one. A vacant unit or a rent that comes in $300 light moves the number toward the line.
Now the contrast. A $921,000 condo, the average condo price in that same summary, renting at the RentCafe two-bedroom average of $4,046 on RentCafe, models well under 1.0x including taxes and insurance, before any HOA dues. Single-unit rent does not carry a price this high.
Below 1.00, the paths a lender may review include a sub-1.00 program, an interest-only structure, or lower leverage with more cash left in the deal. Each carries different pricing and requirements, and eligibility depends on lender guidelines, credit profile, reserves, and property review. Some Somerville-type deals simply do not clear on rent alone. That is a fact about the price level, not a flaw in the file.
DSCR files in markets like this one typically look the same on the front end. The rent schedule is the file. Lenders want signed leases or a market-rent opinion for every unit, an entity that matches the deed, and an insurance quote that covers all units. The files that get kicked back are the ones where one unit’s lease is missing, or where the appraiser’s rent schedule and the borrower’s schedule disagree by a wide margin. Reconcile those before submission, not after.
Which Submarkets Hold Up
Winter Hill, East Somerville, and Magoun Square offer the best price-to-rent balance for a refinance. That read is qualitative. Per-neighborhood price data is thin, and sources rank the “more affordable” neighborhoods differently. East Somerville is the one place with a number: Homes.com shows a median of $874,950 for multi-family. Its sample two-bedroom listing was $2,500. That is the lowest rent in the Boston Pads sample, while the price is not proportionally lower. So East Somerville’s rent-to-value may be weaker than its reputation. Honestly, it is a toss-up between East Somerville and Winter Hill. Neither is cheap enough to ignore the appraisal.
Magoun and Ball Square have a better argument. Boston Pads shows a three-bedroom at $3,300 and a four-bedroom at $4,200. Larger units carry more income per building, and that is what coverage needs. Both squares have Green Line Extension stops and sit near Tufts. The MBTA says the extension supports more than 50,000 trips a day.
Tufts adds a demand layer. A market source reports fall enrollment of 13,650, including 6,619 graduate students, with 40 percent of students living off campus. That is roughly 5,500 renters next to Davis, Ball, and Magoun Squares. Graduate students and staff tend to sign twelve-month leases, which helps long-term underwriting.
Davis Square has a rent wrinkle. Zumper lists it at $3,250 a month, down 11.3 percent year over year. Teele Square is $3,425, down 18.4 percent, though that rests on only 18 rentals. Ten Hills is $3,813, up 12.1 percent. Sources disagree on direction, and the city-wide picture is similar: Zumper has the average at $3,550, up 4 percent, while RentCafe has $3,474, down 1.88 percent. Flat is the fair read.
Union Square is where the Green Line Extension hub meets new supply. Patch reported that the 450-unit Prospect Union Square was still filling restricted studios at a reduced rent with a month free. That is one building, not a vacancy rate. But a small landlord with a one- or two-bedroom nearby should stress-test the rent assumption. Concessions next door pull comps down.
Seasoning, the 75 Percent Ceiling, and Reserves
The mechanics are simple. Cash-out LTV is capped at 75 percent, a hard ceiling, and it is lower than the 80 percent purchase figure. Ownership of about six months is typical, measured from title recording, and the settlement statement documents it. Files that assume the seasoning away get returned.
Reserves are the second constraint. Expect about six months of the full obligation in reserves, and about nine when the balance runs above $1,500,000. At Somerville prices, many triple-decker files will sit near that line. Document the reserves with statements, not a promise. Minimum credit is typically 620, with tiers at 660, 680, and 700 that can improve how a file is reviewed. Loan sizes run up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network.
Equity available is not a fixed number. It depends on the rent used for lender review, the full obligation, reserves, and the 75 percent ceiling. If coverage is the binding constraint, the allowable loan shrinks before LTV does. Title held in an LLC is generally workable, subject to lender program eligibility, but the entity documents must match the deed.
Through Lendmire’s DSCR program footprint — 41 markets, including Washington, D.C. — lenders may review qualifying rental income subject to program guidelines for Somerville, Massachusetts investors. For the structure itself, the guide “What Is a DSCR Loan” covers the basics, and the comparison shows how DSCR differs from a conventional refinance. State-level context sits in the DSCR loan options for Massachusetts investors page, and Lendmire’s DSCR cash-out refinance page lays out the product. The refinance side covers rate-and-term options if cash-out math does not clear.
What the Proceeds Are For
Cash-out only makes sense if the next deal clears on its own. In Somerville, that usually means the proceeds go outside the city. The entry price here is about $850,000, and the demand picture is rents that are flat, not rising. Reinvesting into another Somerville building with the same coverage profile compounds the same constraint.
An owner pulling equity from a paid-down triple-decker may do better with a smaller-balance property elsewhere where rent-to-price runs higher. Or leave the building alone and refinance only if the coverage number improves. Pulling cash to chase a thinner deal is how a sound asset becomes two marginal ones.
For a file already in progress, you can ask Lendmire to review the file or call 828-256-2183.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Somerville, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
Can a Somerville condo support a DSCR cash-out refinance?
Rarely on rent alone. At the average condo price, a typical two-bedroom rent models well under 1.0x once taxes, insurance, and HOA dues are included. A lender may review sub-1.00 programs or lower leverage, but eligibility depends on guidelines, credit, and reserves.
Why do triple-deckers work better than single-family homes here?
Three rents sit on one deed against one loan. A modeled triple-decker at the average multi-family price and about $3,500 per unit lands near 1.1x including taxes and insurance. A single unit does not generate that ratio at Somerville prices.
Will the appraisal come in above my purchase price?
Do not assume it. Median prices are down 4.6 percent year over year, though price per square foot is up. A building bought near the peak may appraise flat or lower. Plan the refinance on current rent, and a reconsideration packet with recent in-neighborhood sales can address a light value.
Does the Green Line Extension change the rent math?
It adds demand near the Union Square, Ball Square, and Magoun Square stops. But sources disagree on rent direction across the city, and new supply in Union Square is using concessions. Treat the transit access as support for occupancy, not a reason to assume rent growth.
How much cash can I pull out?
There is no fixed figure. Proceeds depend on the 75 percent LTV ceiling, the rent used for lender review against full obligations, and reserves. If coverage binds first, the allowable loan is smaller than the LTV cap would permit.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income documentation, subject to lender guidelines, and serves LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Lendmire was recognized by Scotsman Guide in 2025 and named a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Somerville housing market
2. Homes.com: Somerville multi-family listings
3. Commonwealth Standard Realty Advisors
4. Boston Pads
5. RentCafe: Somerville rent trends
6. Homes.com: East Somerville multi-family
8. Zumper: Somerville rent research
9. Patch: Prospect Union Square applications
10. recognized by Scotsman Guide in 2025
11. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Somerville, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.