
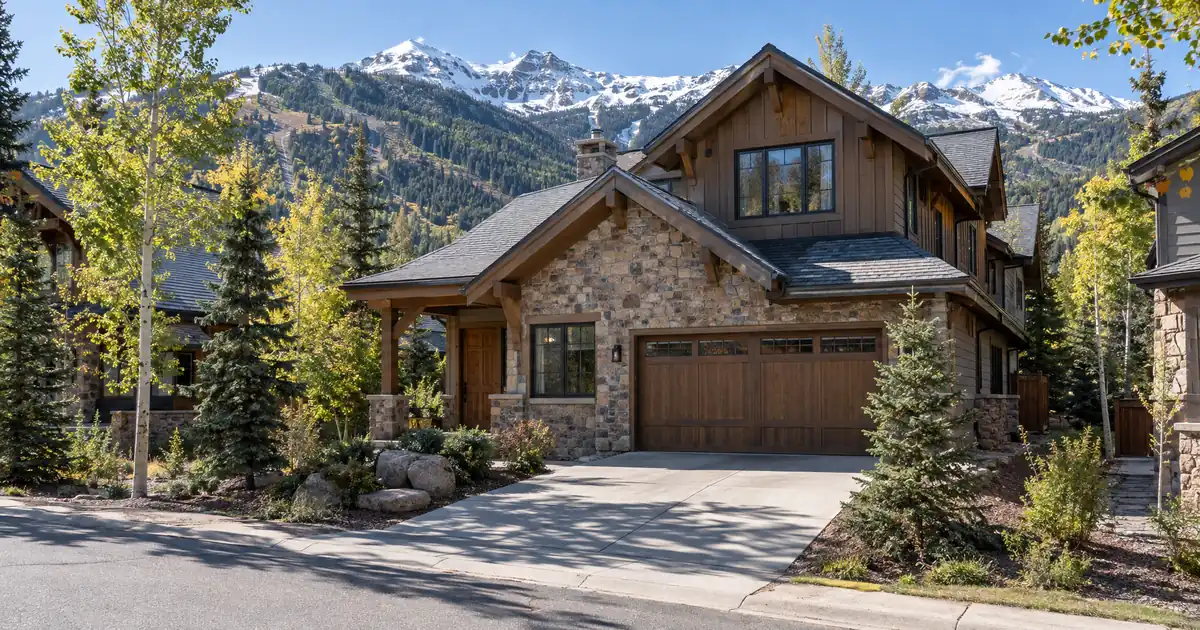
The 75 percent LTV ceiling is rarely what limits a cash-out on a Vail rental. The coverage number is. Two-bedroom rents run roughly $2,200 to $3,500, per Apartments.com at about $2,220, ApartmentFinder at $2,288, and ApartmentHomeLiving at $3,490. That income has to cover a full monthly obligation on a property priced well into seven figures. Equity is not the constraint here. Rent-to-debt is.
The Quick Read: A DSCR cash-out refinance in Vail, Colorado fits investors holding workforce-oriented rentals with real equity and modest leverage targets. It is underwritten primarily on the property’s rental income measured against its full monthly obligation, so lower loan-to-value, not maximum proceeds, usually decides whether a file works, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Vail, CO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow puts the average Vail home value at $1,762,792, up 4.4 percent over the past year.
- Cash-out caps at 75 percent LTV, with about 6 months of seasoning from title recording.
- Reserves run about 6 months PITIA, and about 9 months above $1,500,000.
- In-town Vail has a thin long-term rental comp base, so appraisals lean on valley comps.
- Deed-restricted units change who can rent and how an appraiser values the property.
Vail, Colorado is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, places DSCR loans for investment-property borrowers. This article covers the equity-extraction side of that work: what a Vail owner can realistically pull out, what stops the file, and how to use the proceeds. Purchase mechanics are a separate topic.
Vail Market Snapshot
A quick read on the Vail investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.3M median price (2025 Eagle County Regional) |
| Typical rents | $1,800 median (Eagle County Regional Housing) |
| Recent appreciation | +4.4% yoy (Zillow Home Values) |
The Coverage Problem, Stated Plainly
The debt-coverage ratio is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. Most standard DSCR programs are built around a 1.00x benchmark, since rent covers the payment at that level. Vail pushes the denominator up hard. Census Reporter shows a town of 4,613 residents with a median household income of $98,893, sitting against home values in the millions. The workforce lives mostly elsewhere in the valley.
Run the numbers on a modeled file. Assume a townhome at $1,323,000, the median sale price in Summit Colorado Realty’s brokerage report, refinanced at 75 percent LTV, with a modeled rent of $3,500. Including taxes and insurance, coverage lands under 0.5x. That is not a rounding problem. These are modeled assumptions, not sourced rents, but the gap is structural.
A sub-1.00 file has a few paths a lender may review: a sub-1.00 program with lower leverage, an interest-only structure, or a reduced cash-out request. Each carries tradeoffs in pricing, reserves, and proceeds, and qualification stays subject to lender guidelines, credit approval, and property review. A pure long-term-rent file at high leverage in town is not the file most lenders want to see.
(The honest read is that many Vail cash-outs work as a low-leverage equity pull, not a cash-flow-funded one.)
Where the Equity Comes From
Appreciation is the reason owners consider a cash-out at all. Zillow shows the 4.4 percent one-year gain on that $1,762,792 average. The Eagle County draft housing needs assessment says non-resort prices grew 15.2 percent a year over a recent four-year stretch, with the median staying above $1 million even outside resort and second-home areas. Treat that as a draft figure. It still points one way: the valley is appreciation-led, not cash-flow-led.
The sale-price data conflicts, and investors should know why. Movoto reports a median sale price of $3,050,000 with 102 days on market versus 88 a year earlier. Summit Colorado Realty shows a $1,323,000 median, 207 active listings, and 5.1 months of supply. The Mountain Views Team report shows 163 residential listings with a median near $2,995,000 and average time on market near 160 days. The spread comes from property mix. Condos and townhomes sit far below the single-family medians. Pick the comp set that matches the subject property, not the headline.
Longer days on market matter for a cash-out. They tell the appraiser the market is not running hot, and they feed into value conclusions.
West Vail, East Vail, and the Valley: Where the Files Pencil
West Vail is the most workforce-oriented in-town area, and the most plausible long-term-rental fit inside town limits. Tenants are resort, hospital, town, and school employees. An agent blog, Beatriz Martinez’s market write-up, puts East and West Vail at $950 to $1,200 per square foot, against up to $1,700 in Vail Village and Lionshead. Directional only. No reliable neighborhood rent source exists.
Vail Village and Lionshead are a poor fit for DSCR cash-out on long-term rent. Luxury second homes and condo-heavy, hotel-style demand dominate, and the entry prices swamp any rent.
East Vail has single-family and duplex-style stock in the same per-foot band as West Vail. Small properties there can work if the owner holds real equity and keeps leverage low.
Eagle-Vail and Edwards sit outside town limits, and this is where many Vail workers actually live. Wikipedia’s Eagle-Vail entry describes 1,400-plus homes with a mix of year-round residents and second homeowners. Edwards hosts the Colorado Mountain College Vail Valley campus, which Wikipedia lists at 2,490 students in its most recent reported count, the largest CMC campus. The same page cites a 4.0 percent rental vacancy from the last full Census count, which supports a roughly 5 percent underwriting vacancy as a rough guide. Dated data, so use it loosely.
Demand anchors are real. The Vail Health careers page calls it one of the town’s largest employers, and Vail Resorts advertises a $20 per hour starting wage. Data USA shows accommodation and food services at 485 residents, arts and recreation at 334, and educational services at 317.
Why Does the Appraisal Decide How Much Comes Out?
In-town Vail has few long-term rental comps, and that is the most common stall point on files like this. The draft county assessment says only one-third of Vail housing units are occupied by year-round households. Appraisers and underwriters often pull rent comps from Edwards, Avon, or Eagle-Vail instead. That can cap the rent used for lender review, which caps the cash-out.
Working DSCR brokers see a recurring pattern in resort markets: owners quote rents from listing sites, and the appraisal’s market rent (Form 1007) or the signed lease comes in lower. Listing averages skew toward luxury and seasonal units, so they overstate what a workforce tenant pays. The county’s housing needs analysis, using Census survey data, shows an average rent of $1,924 and a median of $1,800 countywide. Underwrite to signed leases and local workforce rents, not aggregator averages.
Here’s the catch on price. Eagle County’s median home price was above $1.3 million in that analysis, against that $1,800 rent. Only lower-priced workforce stock, or rent-by-the-room setups in the $1,500 to $2,000 per bedroom range from county focus groups, is likely to approach coverage. Those are countywide figures, not Vail-specific.
If the subject is a condo or townhome, the HOA questionnaire and condo certification come into play. Incomplete questionnaires stall files. Request them early.
Deed-Restricted Units (Check Before You Appraise)
Vail runs a town-operated buy-down program, Vail InDEED, with a stated goal of 1,000 net new deed restrictions and 175 homes restricted at the time of the town’s about page. The town also reports 72 new rental homes, all deed restricted. The Timber Ridge plan would grow deed-restricted homes from 98 to 284.
The program has no appreciation cap and no income cap, but it limits occupancy. Per HUD USER, the household must include a qualified resident who works at least 30 hours per week in an Eagle County business. The owner may be that person or rent to one, and the agreement runs in perpetuity with the property.
For a cash-out file, this matters in two places: clearing title needs to surface any restriction, and the appraiser has to value the property as restricted. A restricted unit rented to a local worker is a clean long-term-rental story. It also has a narrower buyer pool. Confirm status before you order anything.
Seasoning, Reserves, and Sizing
Seasoning runs about 6 months of ownership, measured from title recording, and the settlement statement documents it. Files that assume seasoning away get kicked back. Credit tiers start at a 620 floor, with tiers at 660, 680, and 700 improving the file.
Reserves deserve attention in Vail. They run about 6 months of PITIA, and about 9 months above $1,500,000. Many Vail properties sit above that line, so reserves documentation (liquid statements, sourced and seasoned) becomes a real workload. Standard programs go up to $3,000,000 in loan amount. Proceeds are not a guaranteed figure: they depend on rent used for lender review, PITIA, reserves, and the 75 percent ceiling. Borrowers holding the property in an LLC should expect entity documents to be reviewed, subject to lender program eligibility.
The cleanest file from a documentation standpoint has complete leases, entity docs, title, insurance binder, and property details ready for lender review. See the equity-extraction mechanics and the investment property refinance options for the broader structure. Verify current local rental rules, taxes, and insurance with qualified local professionals.
Where the Proceeds Go
The 4,500-unit workforce housing shortfall cited by the Vail Valley Partnership supports tenant demand across the valley. The figure comes from an older county assessment, and the page says employers rate workforce housing availability as a critical or major problem. That undersupply lowers extended-vacancy risk on long-term rentals.
One counterweight: Eagle County Housing lists a 102-unit CMC-linked development in Edwards with rent tiers at 60 and 80 percent of area median income. Subsidized supply can compete with private rentals at the low end.
So the logical redeployment is into valley workforce stock, not more in-town resort product. A Vail equity pull funding an Edwards or Eagle-Vail duplex or townhome is the pattern that pencils better on coverage, since those properties price lower against similar rent demand. For a side-by-side of how these loans differ from bank financing, see the guide “Where DSCR and Conventional Diverge”. The guide “What Is a DSCR Loan” covers the ratio itself, and DSCR loan options for Colorado investors lays out the state hub.
Frequently Asked Questions
How do you qualify for a DSCR loan in Vail, Colorado?
Qualification centers on the property’s rent against its full monthly obligation, typically measured against a 1.00x benchmark, plus credit (a 620 floor, better tiers at 660, 680, and 700) and reserves of about 6 months PITIA. Vail’s high prices mean coverage is the hard part, so lower leverage often decides the file. Final eligibility depends on lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Vail, CO, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for a cash-out refinance on a Vail investment property?
Expect about 6 months of ownership measured from title recording, a maximum of 75 percent LTV, and reserves of about 6 months PITIA (about 9 months above $1,500,000). Loan amounts go up to $3,000,000 on standard programs. Cash-out proceeds are not guaranteed and depend on rent used for program review, PITIA, and reserves.
Will in-town Vail comps support the rent I’m quoting?
Often not. In-town long-term-rental comps are thin, since only about one-third of Vail units are occupied by year-round households per the draft county assessment. Appraisers may use Edwards, Avon, or Eagle-Vail rents, and the appraisal’s market rent or a signed lease controls, not listing-site averages.
Does a deed-restricted Vail property work for a cash-out refinance?
It can, but the restriction limits occupancy to a qualified resident working at least 30 hours per week in Eagle County, and it runs with the property. The appraiser must value it as restricted, and title review should surface the agreement. Confirm status before ordering the appraisal.
What documents matter most for a Vail DSCR cash-out review?
Signed leases, entity documents, title, insurance, and reserves statements lead the list. Lendmire arranges DSCR investor loans, and one program feature that matters here is cash-out up to 75 percent LTV after about 6 months of seasoning. Condo or townhome files also need a complete HOA questionnaire.
The Real Choice on a Vail Equity Pull
Two honest options face an owner with equity in a Vail property. Pull a smaller, lower-leverage cash-out that keeps the coverage number defensible, and accept that less capital comes out. Or pursue a larger draw through a sub-1.00 structure, and accept tighter reserves, different pricing, and a thinner margin for error. Both can fund a valley workforce purchase. Vail’s rents are not going to close the gap between the two.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The lender evaluates DSCR loans mainly on rental income rather than personal income, subject to lender guidelines. That suits LLC-owned portfolios, self-employed investors, and operators scaling beyond conventional loan caps. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and is a 2025 Scotsman Guide Top Workplace. To discuss a file, call 828-256-2183 or get a rental-income loan quote.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
4. $1,762,792
5. static1.squarespace.com — 2025 Eagle County Regional Housing Needs Assessment
6. Eagle County Regional Housing
7. Summit Colorado Realty’s brokerage report
8. Movoto
10. Beatriz Martinez’s market write-up
11. Wikipedia’s Eagle-Vail entry
12. Wikipedia
14. Vail Resorts
17. vail.gov — Housing Vailindeed
18. Vail Valley Partnership: Workforce Housing
19. Eagle County Housing: Rentals
20. recognized by Scotsman Guide as a 2026 Top Workplace
21. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Vail, CO · Investment Property Cash-Out Refinance in Colorado
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.