
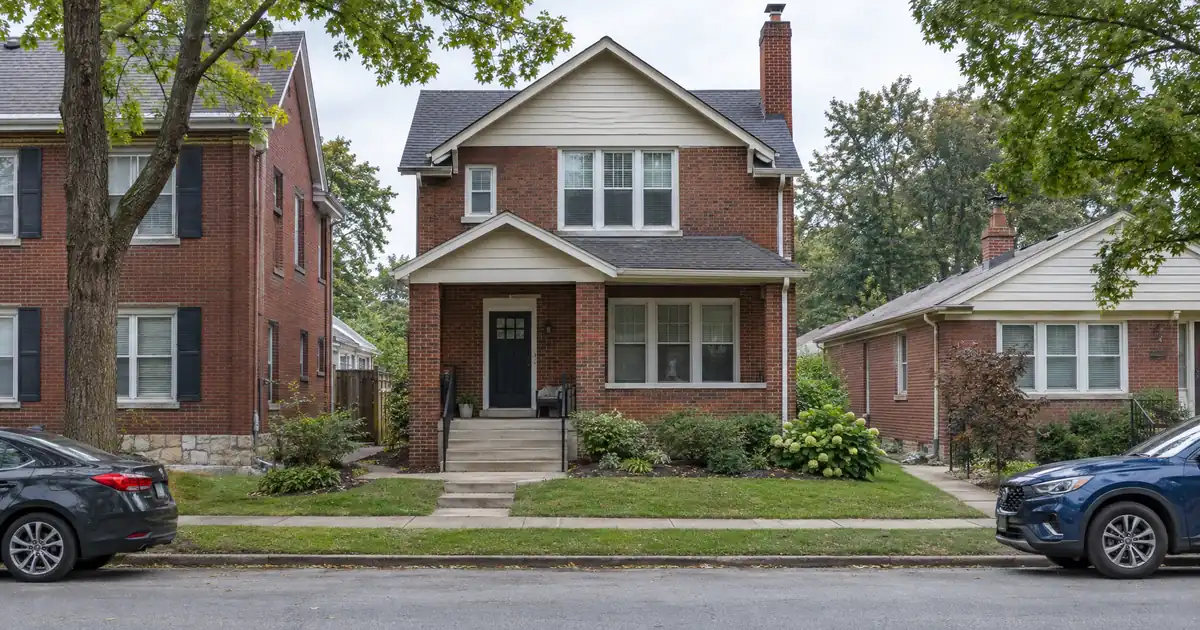
Picture an investor holding a duplex in the Webster Park area, bought years ago. The mortgage balance has shrunk, the tenants have stayed, and the building now carries far more equity than its rent roll would suggest. A second building is sitting on the market, and the down payment is the only thing missing. The equity exists. The real question is whether the income can carry a larger loan and put that equity to work.
DSCR Cash-Out Calculator
Run the cash-out numbers in Webster Groves, MO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash out refinance on a Webster Groves, Missouri investment property is underwritten primarily on the rental income the building produces measured against its full monthly obligation, rather than on the owner’s traditional personal-income documentation, which lets an existing landlord convert equity into capital, subject to a 75 percent LTV ceiling and lender review.
- Small 2–4 unit buildings are about 2.91 percent of housing units, per NeighborhoodScout.
- Cash-out LTV tops out at 75 percent, with about 6 months of seasoning from title recording.
- Single-family rent-to-value runs thin, so coverage depends on lower leverage or multi-unit rents.
- Rent estimates span $1,450 (Zumper) to $2,374 (Redfin) depending on source.
- Webster Groves is appreciation-led, so treat cash-out as equity extraction on an existing hold.
Webster Groves, Missouri is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire places DSCR loans for investment-property borrowers (NMLS# 2371349). The brokerage arranges these files through wholesale lending channels, and the lenders review eligibility and make credit decisions. In this market, a DSCR cash out refinance suits an owner who already holds the asset. How rental-income qualification works matters more here than in most suburbs, because the entry basis makes buying for cash flow difficult.
Webster Groves Market Snapshot
A quick read on the Webster Groves investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 32 sales (Redfin) |
| University enrollment | 4,000+ students (Webster Groves School District) |
| Employment | 700+ employees (Webster Groves School District) |
Why This Is an Equity Play, Not a Cash-Flow Play
Webster Groves rewards holders rather than buyers. Values are high relative to rents, inventory is thin, and appreciation is steady rather than spectacular. That profile suits cash-out refinancing on assets bought earlier.
The value figures depend heavily on the source. NeighborhoodScout puts the median house value at $486,477 and says annual appreciation trails 60 percent of Missouri cities. That figure is the anchor used throughout this article. Redfin reports a higher median sale price of $561K, while Niche, which draws on Census-based data, puts median value at $387,600. Those gaps reflect different methods and different housing mixes, not a market in disarray.
Supply is tight. Redfin shows homes selling after 4 days on market and scores the city 95 out of 100 for competitiveness. A local brokerage’s market update describes a similarly constrained picture, with relatively few active listings at any one time. Tight supply tends to support value stability on a refinance appraisal. It also makes buying in at a low basis hard, which is why this is a market where the cash-out beats the acquisition.
Where Most Investors Misread the Appraisal Picture
The headline appreciation number in the Redfin data is not a trend. Redfin’s median sale price jumped 40.1 percent year over year in the month cited, yet the median price per square foot slipped 1.1 percent to $233, and only 32 homes sold that month (Redfin). Mix explains the gap: larger, pricier homes happened to sell.
An owner who assumes that 40 percent gain will show up in an appraisal is setting up a disappointment. Thin monthly volume also means shallow comp depth, so an appraiser has fewer closed sales to lean on. Size the refinance to conservative value, not to the best-looking headline.
Rent-to-Value: Where Single-Family Runs Out of Room
Single-family rentals in Webster Groves struggle to cover a cash-out loan at high leverage. Rent estimates for the same city vary widely by source, but none of them fix the arithmetic.
Zillow’s rental tracker puts the all-property average rent at $1,900, with one-bedrooms at $1,250, two-bedrooms at $1,895, and three-bedrooms at $2,385. Zumper reports an average of $1,450, and Redfin’s rental page shows $2,374. Niche pairs a $1,650 median rent with that $387,600 median value, which works out to roughly 0.43 percent monthly rent-to-value. That is a calculation from two numbers, not a published ratio. A $2,385 three-bedroom against Redfin’s $561K median lands at nearly the same place.
Run the numbers on a modeled case. Assume a single-family home valued at the NeighborhoodScout median of $486,477, rented at Zillow’s three-bedroom average. Coverage on full PITIA, meaning taxes and insurance included, lands around 0.75 at 75 percent LTV. Cut leverage to 60 percent and the number approaches 1.00 without clearing it. Those inputs are modeled assumptions, not sourced market facts.
A sub-1.00 file is not necessarily dead, but it changes the conversation. A lender may review a sub-1.00 program, an interest-only structure, or a lower LTV with stronger reserves. Each carries trade-offs in pricing, leverage, or cash required, and eligibility depends on lender guidelines, credit profile, and property review.
Small Buildings Carry the Math
Duplexes, triplexes, and fourplexes are the best DSCR fit in Webster Groves, and they are scarce. NeighborhoodScout reports that single-family detached homes make up 78.81 percent of housing units, large apartment complexes 17.19 percent, and duplexes, converted homes, and small apartment buildings just 2.91 percent. That puts the asset class in a single-digit sliver of roughly 9,641 housing units.
Scarcity cuts two ways. A cash-out on a long-held small building is realistic because the owner already controls the asset. A new purchase of one is a different, harder problem, since a point-in-time look at duplex and triplex listings showed little or nothing for sale.
Here is a modeled duplex. Assume two-bedroom units at the Zillow average of $1,895 each, a building valued at $520,000, and 75 percent LTV. Coverage on full PITIA comes out around 1.15 after rounding down. Haircut rents by 10 percent and the number slides to about 1.05. That sensitivity matters because Zillow shows rents up just $5 year over year and tags the rental market “COOL.” Underwrite flat rents, not growth. A refinance that only works if rents rise is a risk, not a plan.
Newer product sets a high ceiling but not a benchmark. Compass listings at The Elle on Lockwood showed a one-bedroom asking $1,999 and two-bedrooms asking roughly $2,999 to $3,160. Those are asking rents on new construction, not achieved rents on older buildings, but they show room for renovated units to push higher.
Four Pockets Worth Knowing
The city formed in 1896 when five communities merged, and the old village centers still anchor distinct submarkets. No reliable neighborhood-level rent or price data surfaced, so these profiles are qualitative.
Old Webster and Central Webster. This is the historic core. Ryan Patton Group says the Central Webster Historic District, Tuxedo Park, and Glendale Heights routinely draw competing offers. That signals high basis, which means high appraised values for an existing holder but thin coverage for anyone buying in now.
Webster Park and Old Westbury. Duplex and small-building rentals show up here, per Homes.com, including a two-bedroom duplex in the heart of the city. No rent figure was captured, but this is where income stacking is most plausible.
Lockwood corridor and the Webster University area. Demand here comes from faculty, graduate students, and young professionals. Webster University reported 13,448 total students, of whom 7,719 were on U.S. campuses and online, and the main campus spans 47 acres. Only a fraction of those students live in the city, so treat the university as a demand anchor, not a guarantee. Eden Theological Seminary adds a small graduate base.
Old Orchard. Retail and dining along Big Bend Boulevard near Lockwood make this a walkable pocket, which supports renter demand. No pricing was captured.
Employment support is modest but steady. The Webster Groves School District employs more than 700 people. The city has about 23,525 residents per NeighborhoodScout and sits within St. Louis commuting range, so tenant demand leans on the broader metro’s jobs. No major corporate or hospital employer data was verified, and this article does not guess at one.
What the 75 Percent Ceiling Actually Leaves You
The cash-out LTV ceiling is 75 percent, a hard cap that sits below purchase LTV, and the equity an owner can actually pull depends on more than that cap. Think of it as three gates.
First, seasoning. About 6 months of ownership, measured from title recording, is typical before a cash-out is eligible. Second, coverage. The standard baseline is a 1.00 DSCR using rent used for lender review against PITIA, and some lenders review lower-ratio files only with stronger compensating factors. Third, reserves and credit: about 6 months of PITIA in reserves is typical, rising to about 9 months above $1,500,000, with a credit floor of 620 and tiers at 660, 680, and 700. Loan amounts run up to $3,000,000 on standard programs, though smaller balances route through select lenders in the network.
Run through the equity logic. An investor whose existing balance sits at 55 percent of appraised value has about 20 points of LTV room before reserves and coverage tests. The proceeds are not guaranteed, and the 75 percent figure is a ceiling, not a target. Where title is held in an LLC, eligibility is subject to lender program eligibility.
Most owners use proceeds as down payment capital for the next acquisition. They either buy in a lower-basis market or add a second small building. For the full mechanics, see pulling equity with a DSCR cash-out and refinance details. If you’re weighing this against a bank product, Lendmire’s DSCR-versus-conventional breakdown explains why rental income, not traditional personal-income documentation, drives the file. Investors can also run the numbers with Lendmire when comparing structures.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Webster Groves, MO, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
On files from inner-ring suburbs with high values and thin rent-to-value, Lendmire’s deal desk tends to see the same friction point. The owner expects the appraisal to settle the question, and the coverage number turns out to be the binding constraint instead. The cleaner files usually arrive with a current rent roll, leases that match the rent schedule, and a clear view of the existing payoff. Owners who plan for the lender’s rent figure rather than their own asking rent avoid most surprises. Investors with Missouri holdings beyond Webster Groves can see DSCR loans in Missouri for state-level context. Before committing, verify current local rental rules, taxes, and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR loan in Webster Groves?
Qualification centers on the property’s rental income measured against its full monthly obligation, with credit, reserves, and LTV also in play. A 1.00 baseline is common, a credit floor near 620 applies, and reserves of about 6 months PITIA are typical. Final eligibility depends on lender guidelines, borrower profile, and property review.
What are the requirements for an investment property cash-out refinance in Webster Groves, Missouri?
Expect about 6 months of ownership from title recording, a maximum 75 percent LTV, and rent used for lender review that meets the lender’s coverage test. Reserves of about 6 months PITIA are typical. Properties like manufactured homes, log homes, and barndominiums fall outside these programs.
Do duplexes and fourplexes make cash-out easier in Webster Groves?
Generally yes, because per-unit rents stack against one payment. A duplex at modeled values can sit near 1.15 coverage including taxes and insurance, while a single-family home at median value runs well below 1.00. The catch is scarcity, since small buildings are only about 2.91 percent of housing units.
Can Lendmire help arrange DSCR financing for an investment property in Webster Groves?
Yes. Lendmire is a DSCR-focused mortgage broker with investor loan programs. A key program feature is that rental income, rather than traditional personal-income documentation, is central to program review. Terms and eligibility remain subject to lender guidelines.
Which rent figure should I use when sizing a Webster Groves cash-out?
Use the lender’s appraisal rent schedule, or the lowest defensible figure, not a portal average. Sources range from $1,450 to $2,374 for the same city, and asking rents at new buildings run far higher than rents on older small buildings. Flat rents are the safer underwriting assumption.
The Diligence Step Before Any Application
Pull the rent roll and leases for each unit, then set them beside Zillow’s bedroom averages and current listings in the same pocket. Whatever number comes out lowest and holds up is the one to size the cash-out on. In a city where fewer than three in a hundred housing units are small multifamily, the rent roll on the building you already own is the most valuable document in the file.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. Eligibility review centers on the property’s rental income rather than the borrower’s traditional income documentation, which suits self-employed operators and portfolios beyond four financed properties. The brokerage was recognized by Scotsman Guide as a 2026 Top Workplace and recognized by Scotsman Guide in 2025. Investors can reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. NeighborhoodScout, Webster Groves
2. Zumper
3. Redfin
4. Redfin, Webster Groves Housing Market
5. Webster Groves School District
6. Remaxbestchoice.com — Webster Groves, MO Housing Market Update: Summer
7. Zillow Rental Manager, Webster Groves
9. City of Webster Groves, Area History
11. Homes.com
14. recognized by Scotsman Guide as a 2026 Top Workplace
15. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Missouri
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.