
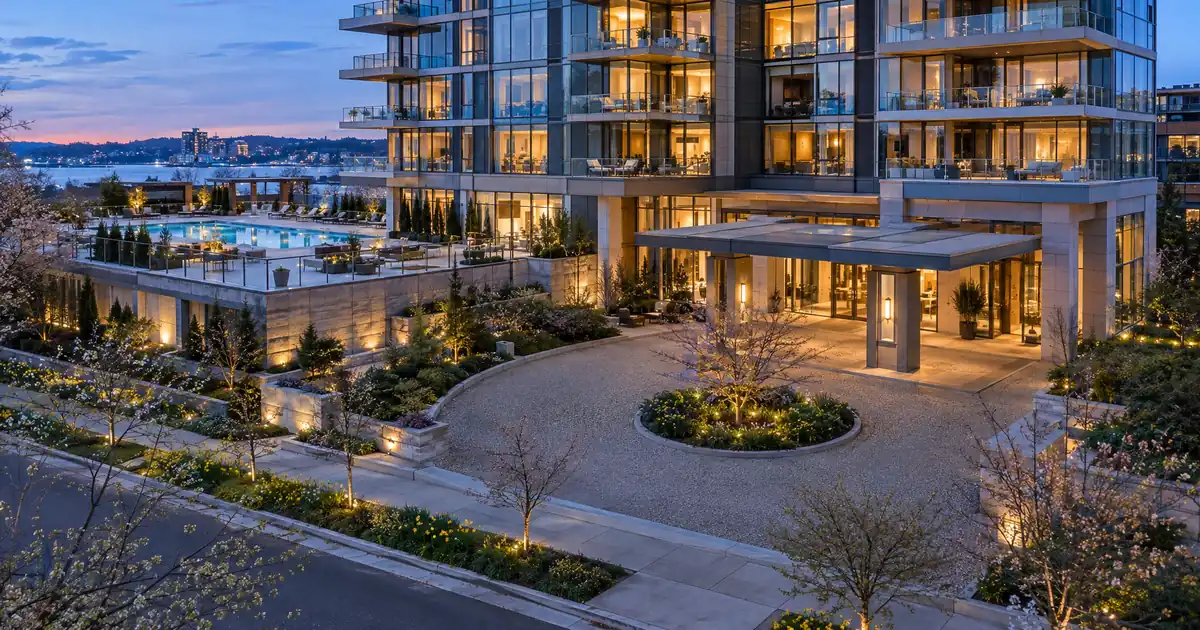
The Quick Read: A luxury condo suits a landlord who wants a low-maintenance, well-located unit and can live with association control, while a fourplex suits one who wants four rent streams under one roof and can handle the management work that comes with it. Both can be financed on a jumbo DSCR loan. DSCR, short for debt service coverage ratio, compares the property’s rent to its full monthly payment, known as PITIA (principal, interest, taxes, insurance, and association dues). The condo adds dues and a building review, and the fourplex adds management load and a single building’s taxes and insurance.
- Both property types can qualify primarily on property-level rental income covering the payment, subject to lender guidelines.
- A condo faces two tests: the rent math and a separate review of the building and association.
- A fourplex faces the rent math plus a review of each unit’s rent, condition, and occupancy.
- Purchase leverage on an investment property typically runs 75%–80% LTV (loan-to-value, the loan as a share of the price) on most files.
- Clearing the coverage threshold is not the same as positive cash flow.
Side-by-Side
Here is how the two assets compare on the points a lender and a landlord both care about. The column entries reflect how files in a wholesale network typically behave, and exact treatment varies by lender, loan size, and property.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 29, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 29, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
| Factor | Luxury Condo | Fourplex |
|---|---|---|
| Review basis | Rent vs. PITIA incl. Dues | Combined unit rents vs. PITIA |
| Rent evidence | One-unit market rent schedule | Per-unit rents on a 2–4 unit report |
| Dues in the payment | Yes, monthly association dues | Only if an association exists |
| Second review | Building and association | Rent roll, condition, occupancy |
| Vacancy impact | All-or-nothing on one unit | One empty unit removes a quarter of rent |
| Entity vesting | LLC possible, if program allows | LLC possible, if program allows |
| Reserves | Scale with loan size and leverage | Scale with loan size and leverage |
| Owner control | Association sets rules and costs | Owner sets rents, repairs, tenants |
Nothing in this table compares pricing, because pricing depends on the individual file. The calculator on this site gives an illustrative estimate once you have a scenario.
Key Terms Defined
DSCR (debt service coverage ratio): Monthly rent divided by the full monthly payment on the property. A result of 1.00 means rent equals the payment.
PITIA: Principal, interest, taxes, insurance, and association dues, added together as one monthly figure.
Warrantable condo: A condo project that meets the standard project tests used for conventional loans, such as owner-occupancy mix, finances, and litigation history. A project that fails those tests is called non-warrantable.
Jumbo: A loan larger than the conventional limit. In DSCR lending, it simply means a larger-balance tier inside the program.
Non-owner-occupied: You do not live in the property. It exists to produce rent.
Seasoning and reserves: Seasoning is how long you have owned a property before refinancing it. Reserves are liquid savings the lender wants left over after closing.
How a Jumbo DSCR Loan Reads Each Property
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
The lender asks one core question: does the rent cover the payment? The answer comes from the appraisal, which does two jobs. It sets the value, which drives LTV, and it reports market rent, which drives coverage.
The loan sizes matter here. Standard programs in the network run up to $3,000,000, and above $2,500,000 the network generally holds to 30-year fixed structures. A luxury condo and a luxury fourplex both land in jumbo territory more often than a typical rental does, so both face the larger-loan expectations: stronger credit, more leverage discipline, and more reserves.
A Modeled Side-by-Side on Coverage
Run the numbers on this modeled scenario. These are assumptions for illustration, not market data. Say a condo and a fourplex sell at the same price, and each produces rent that covers the loan’s principal and interest alone at roughly 1.3x.
On the fourplex, you add one tax bill and one insurance policy for the building. Coverage might settle near 1.15x. On the condo, you add taxes, insurance, and monthly dues. Coverage might settle nearer 1.05x.
The dues are the swing factor. A modest dues increase on the condo can pull the ratio toward 1.00 quickly in modeled terms, while the same increase never touches the fourplex. That is the central tradeoff: the condo’s costs are partly set by someone else, and the fourplex’s costs are set by you.
If the condo lands under 1.00, there is a path. Many select programs start at 1.00, and a separate select-lender path goes below 1.00 with leverage and terms adjusted. Eligibility stays subject to lender guidelines, credit approval, and property review.
Where the Ratio Misleads
DSCR compares rent to PITIA and nothing else. Repairs, vacancy, management, utilities, and capital expenses sit outside the calculation.
That gap hits each asset differently. A fourplex carries real operating costs: a roof, boilers, turnover, and the days one unit sits empty. A condo carries a quieter risk. The association can levy a special assessment that never appears in PITIA but still takes cash out of your pocket.
A loan that clears the coverage test is a loan the lender is comfortable with. It is not a promise the property makes money. Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
When the Luxury Condo Is the Better Fit
The condo fits a landlord who values location and low operating involvement over control. The association handles exterior upkeep, common areas, and the building’s master insurance. You manage one unit and one tenant.
It also fits when scaling matters less than quality. A well-run building in a strong rental location can hold tenants longer, and a single-unit appraisal is simpler to read than a four-door income report.
The risks come with the building. Three things deserve attention before you write an offer:
- Dues: They sit inside PITIA, so every dues increase lowers your coverage.
- Rental rules: Some buildings cap how many units can be rented or restrict leases. No loan structure fixes a rental ban, so read the association documents first.
- Project review: The lender reviews the building as well as your unit. Typical documents include the association questionnaire, budget, insurance, and reserves.
Warrantability is where programs split. Some lenders place condos only in warrantable projects, while others review non-warrantable projects on their own terms. The trade press notes that investors adding rental condos often turn to DSCR for non-warrantable units. Lendmire’s piece on how a super jumbo DSCR loan handles a non-warrantable luxury condo goes deeper on that case.
Hotel-style condo units are a separate question, and program eligibility there varies, so ask before you commit to one.
Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. In a condo building, the association’s documents must allow it as well.
When the Fourplex Is the Better Fit
A fourplex fits a landlord who wants income diversification and control in a single purchase. Four rent streams sit under one roof, so one vacancy does not zero out the property. It also stays in residential-style DSCR underwriting, while five or more units generally move to commercial underwriting.
The appraisal reads differently, too. The appraisal form for two- to four-unit properties is Form 1025, the Small Residential Income Property Appraisal Report. It captures rent unit by unit. The one-unit rent schedule (Form 1007) belongs to single-unit investment properties, so it does not apply to a fourplex. DSCR lenders borrow these form names for their own reviews.
There is no building review in the condo sense. But there is a different diligence load:
- Rent support: Each unit needs market rent evidence, and existing leases help.
- Vacancy: One empty unit in four removes 25% of rent.
- Condition: Four kitchens, four sets of systems, and one roof mean larger capital items.
- Concentration: Everything rides on one building.
Lendmire’s piece Super Jumbo DSCR vs Commercial Loan on a Luxury Triplex or Fourplex covers the commercial boundary in more detail.
What Jumbo and Luxury Change for Each
Jumbo sizing changes the file more than the property type does. On an investment-property purchase, most files across the network land at 75%–80% LTV, which means 20%–25% down. Select high-leverage programs reach 85% LTV on a purchase with roughly a 700+ score. A cash-out refinance on a standard rental tops out around 75% LTV, with about six months of seasoning as the common expectation.
Credit tiers follow the same pattern. A 620 floor exists in parts of the network, most programs want around 660, and 700+ unlocks the strongest leverage tiers. Reserves vary by lender, leverage, loan size, and transaction type. They commonly run around six months of PITIA, and loans above $1,500,000 typically step up to about nine months. Conservative rate-and-term files at modest leverage under $1,500,000 can see reserves waived.
A bigger down payment can lower the payment and lift the ratio. It never erases leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear both tests: enough equity and enough rental coverage.
“Jumbo” also means something different here than on a conventional loan. FHFA sets the baseline conforming limit for a one-unit property at $832,750, with a higher ceiling in high-cost areas. A multi-unit limit applies only when you buy the whole building, so a single condo is measured against the one-unit limit. The same dollar loan can therefore be jumbo on a condo and still sit under the multi-unit limit on a fourplex. That matters only if you are weighing a conventional alternative, because a DSCR loan has no conforming limit.
Luxury pricing adds two quieter effects. High-end condos and luxury fourplexes often have few true comparable sales, which can mean closer appraisal scrutiny. And at higher prices, association dues tend to be larger, which weighs on the condo’s ratio.
Entity, Exit, and Portfolio Fit
Both properties can be vested in an LLC, subject to lender program eligibility. Ask early, because entity and guarantor requirements vary by lender.
Exit is where the two diverge. A luxury condo typically sells to a mix of owner-occupants and investors, and buyers will read the building’s finances. A luxury fourplex sells mostly to investors, which can mean a smaller buyer pool. Neither is always faster or slower to sell, since market and price tier matter more than the asset label.
Portfolio logic matters as well. One fourplex counts as one financed property, while four condos mean four project reviews and four dues streams. Spreading across buildings reduces concentration, though it multiplies the paperwork. DSCR financing also sidesteps the conventional cap on how many financed properties one borrower may hold, as the trade press notes in its discussion of non-warrantable condos and portfolio growth.
What Lenders Ask to See
| Item | Luxury Condo | Fourplex |
|---|---|---|
| Appraisal | Condo unit report with rent schedule | 2–4 unit report with per-unit rent |
| Rent proof | Lease or market rent | Leases or market rent, each unit |
| Building file | Questionnaire, budget, insurance | Building insurance, rent roll |
| Dues | Current statement and history | Only if an association exists |
| Reserves | Per loan size and leverage | Per loan size and leverage |
The Verdict
Choose the condo if you value location, limited maintenance, and a simple single-tenant setup, and you can accept that the association controls dues, rules, and special assessments. Choose the fourplex if you want control, four rent streams, and a stronger buffer against a single vacancy, and you are ready to manage repairs and tenants.
This one is a genuine toss-up on paper, because the coverage math often favors the fourplex while the condo wins on effort. The honest test is to model both with the building’s actual dues or the fourplex’s actual operating costs, then ask which risk you would rather carry. The condo’s risk is outside your control, and the fourplex’s risk is inside it.
Frequently Asked Questions
Can a non-warrantable luxury condo qualify for a DSCR loan?
Sometimes, depending on the program. Many lenders in the network review the project on its own terms rather than by conventional standards, while some place only warrantable condos. Eligibility depends on the building, the loan size, and lender guidelines.
Is a fourplex treated as a commercial property?
No. A fourplex stays in residential-style DSCR underwriting. Five or more units generally move to commercial underwriting, which uses a different method based on net operating income.
How do HOA dues affect the ratio on a condo?
Dues sit inside PITIA, so higher dues lower coverage dollar for dollar against the same rent. A rising association budget can turn a comfortable ratio into a thin one, so ask for the current dues statement before you make an offer.
Does a ratio above 1.00 mean the property cash flows?
No. The ratio tests rent against PITIA only, so repairs, vacancy, management, utilities, and capital items sit outside it. Treat a passing ratio as a lender test, not an income forecast.
Can I buy either property in an LLC?
Often, subject to lender program eligibility.
Next Step
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Lendmire is a broker arranging financing through select lenders in its wholesale network, across 41 markets, including Washington, D.C. For the full picture of how these loans work, read the complete DSCR loans guide. Programs change, every file is underwritten individually, and nothing here is a commitment to lend.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed by the lender around a property’s rental income rather than personal income documentation, which fits LLC-held rentals, self-employed investors, and portfolios scaling past conventional financed-property limits.
Scotsman Guide named Lendmire a Top Mortgage Workplace in 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Scotsman Guide, Invest in Your Future
2. Fannie Mae Selling Guide B4-1.2-01
3. FHFA conforming loan limit announcement
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can You Get a Jumbo DSCR Loan on a Rental Worth Millions? · Does a DSCR Loan Need a 1007 Rent Schedule? · Can You Get a DSCR Loan on a Surfside Beach Rental?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.