
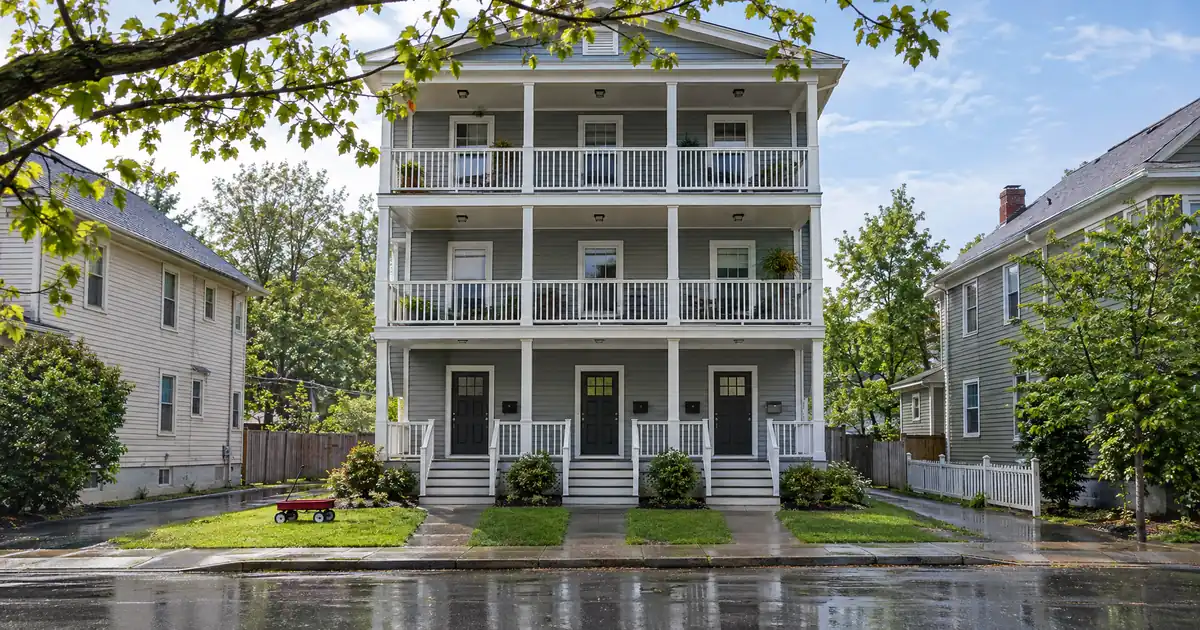
The Quick Read: A self-employed buyer finances a 2-4 unit on bank statements by having the lender average 12 months of deposits, apply an expense factor, and treat the result as qualifying income instead of the net figure on a tax return. The path fits best when the buyer will live in one unit, because occupancy decides which lane applies.
- Twelve months of business or personal statements usually replace traditional personal-income documentation, and the lender sets the expense factor.
- On a primary residence, select lenders in Lendmire’s wholesale network go up to 90% LTV on a purchase.
- Owner-occupied cash-out tops out at 80% LTV, and investment cash-out at about 75%.
- A rental with no owner living in it often fits a DSCR loan better, since that loan tests the property instead of the person.
- Clean, consistent deposits matter more than almost anything else in the file.
Traditional personal-income documentation can punish self-employed buyers. Deductions cut taxable income, and a conventional debt-to-income ratio can look too high even when the business throws off plenty of cash. Bank statement lending exists to fix that mismatch. The rest of this piece walks through how the mechanics work, where they break, and when another loan fits better. For the broader product family, see Lendmire’s complete DSCR loans guide.
What your deposits qualify you for.
Alt-doc programs read 12 months of business or personal bank deposits instead of tax returns. Enter your average monthly deposits and see the income a lender would credit you.
The expense factor is set by the lender from your business type and profit-and-loss statement; it is not a number you choose. This widget quotes no rate and no payment.
Program parameters shown update from Lendmire’s centralized guideline source.
Estimate
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Deposit average, expense factor, and housing ratio are editable assumptions; the expense factor a lender applies is set from your business type and documentation. No interest rate or monthly payment is quoted here. Purchase capacity is a simplified illustration and does not account for taxes, insurance, HOA dues, or other debts. Alt-doc income documentation is available on consumer mortgages in the states where Lendmire is licensed for consumer lending; actual terms vary by lender, borrower, and property.
What Is a Bank Statement Loan, Exactly?
A bank statement loan is a non-QM mortgage in which the lender qualifies you on documented income, using your bank deposits under the applicable program and subject to lender guidelines. The lender reads your deposits instead of your tax-return net income. It is not a stated-income loan, and it is not a loophole.
Lenders still have to confirm you can repay. Scotsman Guide notes that non-QM lenders still must verify repayment-capacity but have more flexibility in how they qualify the borrower. That flexibility is the whole product. The income is real and verified. It is simply measured from cash flow.
Across the wholesale network Lendmire works with, the typical file uses 12 months of statements, business or personal. Loan sizes run roughly $125,000 to $3,500,000, and reserves commonly sit near six months of the housing payment. Exact terms vary by lender, borrower, and property.
How Do Bank Statements Become Qualifying Income?
Underwriters total your eligible deposits, remove the ones that aren’t true income, apply an expense factor if the account is a business account, and divide by the number of months. The result is monthly qualifying income. Here is the sequence, step by step.
1. Choose the account type. Business accounts hold gross revenue, so the lender applies an expense factor. Personal accounts may count deposits more directly, depending on the program.
2. Gather consecutive statements. Twelve months is the common window in this lane. Gaps raise questions.
3. Scrub the deposits. Transfers between your own accounts, loan proceeds, refunds, and one-time windfalls come out. Deposits have to look like the business you describe.
4. Apply ownership share and the expense factor. The lender sets the factor, not you. Some lenders accept an expense statement prepared by an accountant in place of a standard factor, as the Scotsman Guide piece describes, and that can help a business with lean costs.
5. Average the result. Eligible deposits after the haircut, divided by the months, give monthly income.
6. Measure it against your debts. The new housing payment plus every other obligation gets compared with that income.
Picture a buyer whose business account shows steady deposits all year. If the lender applies a 50% factor, only half of those deposits count as income. The same buyer with an accountant-prepared ratio showing lower real expenses may qualify on a larger share. That gap is why the expense method deserves a conversation before you apply, not after.
Underwriting also follows the repayment-capacity framework, which looks at income or assets, employment, the loan payment, other debts, debt-to-income, and credit history, per the federal consumer-finance regulator’s repayment-capacity summary. Bank statements are one way to document the income piece.
Key Terms Defined
Expense factor: The percentage of business deposits a lender removes to estimate real take-home income.
Deposit averaging: Totaling eligible deposits over the statement window and dividing by the number of months.
DTI (debt-to-income): Your monthly obligations divided by your qualifying monthly income.
DSCR (debt service coverage ratio): A property’s monthly rent divided by its monthly debt service, used instead of personal income on investor loans.
Occupancy: Whether you live in the property (owner-occupied) or rent it to others (non-owner-occupied).
Asset depletion: A way to qualify from liquid assets rather than monthly income.
Why Does Occupancy Decide Everything?
Occupancy is the biggest fork for a 2-4 unit. If you live in one unit, the loan is a consumer mortgage and bank statements are a natural fit. If you rent every unit, the loan is business-purpose, and a DSCR loan usually fits better.
That distinction changes the disclosure regime too. An owner-occupied file is a consumer mortgage, so TRID disclosures apply. Keep the two straight when you decide how to structure the purchase.
A house hacker, meaning a buyer who lives in one unit and rents the rest, is the classic bank statement candidate. Leverage can reach up to 90% LTV on a primary residence purchase or rate-term refinance through select lenders, with the strongest files earning the top of that range. An asset-depletion alternative, which qualifies from liquid assets, runs to about 80% LTV on a primary residence. Final terms depend on the lender’s guidelines, the property type, and the borrower’s complete credit picture.
A pure investment buyer is different. Investment purchase leverage on bank statement documentation varies by lender, so treat any number you see as lender-specific. Investment cash-out tops out around 75% LTV. For leverage questions on rentals, the DSCR side is where investor-focused guidance lives.
Bank Statements or DSCR: Which Lane Fits?
Bank statements test the person. DSCR tests the property. That single difference drives the choice.
| Factor | Bank statement loan | DSCR loan |
|---|---|---|
| What is tested | Your deposits and DTI | Rent versus property debt |
| Best occupancy | Owner-occupied | Non-owner-occupied |
| Effect of more purchases | Each loan adds to your DTI | Property-by-property |
| Title | Usually personal | LLC often workable |
| Disclosure regime | Consumer (TRID) if owner-occupied | Business-purpose, TRID-exempt |
Choose bank statements when you will occupy a unit, when rent is thin or the building is new and unstabilized, and when your deposits are strong. Choose DSCR when rent comfortably covers the property’s obligations, when title sits in an LLC (subject to lender program eligibility), or when you plan to keep buying. DSCR qualifies primarily on property-level rental income covering the payment, subject to lender guidelines.
Here is the scaling problem. A personally underwritten loan consumes DTI with each purchase. Buy a second and third property on bank statements and your debt load keeps climbing against the same deposit income. DSCR doesn’t carry that ceiling, which is why serial buyers drift toward it.
Some investors still reach for bank statements on a pure rental because the property’s rent is weak or the building isn’t leased yet. That’s a reasonable instinct in a narrow set of cases. It is also a signal worth testing: if rent can’t support the property, check whether the submarket and the purchase price are right before picking a loan type to fit the deal.
How Does a 2-4 Unit Change the File?
More units mean more moving parts: an income-property appraisal, a rent schedule, and a decision about how rent counts against the payment. Duplexes, triplexes, and fourplexes all fit the 2-4 unit category. How rent offsets the payment is program-specific, and lenders differ.
For appraisal, the property is typically valued on the small residential income property form (Form 1025) with a market rent schedule (Form 1007). Those are appraisal tools. They tell the underwriter what the units are worth and what they might rent for.
Whether the lender uses that rent to reduce your obligations, and how much of it, depends on the program and on whether you occupy a unit. Don’t assume full credit. Ask the loan officer how a specific program treats projected rent on the units you won’t occupy, and whether leases are required. Here is the sequence of questions that usually matters:
- Does the program count rent from the other units, and at what share?
- Is a signed lease required, or does the appraiser’s rent schedule suffice?
- Does the unit count change reserves or leverage?
- Is the property stabilized, or is it newly built or partly vacant?
Three- and four-unit buildings often get a closer look than duplexes. Five or more units generally moves into commercial lending, outside this lane entirely.
Edge Cases Where the Rule Bends
The general rule is twelve clean months and an owner-occupant. Real files rarely look that tidy. These are the situations that most often change the answer.
A business younger than 24 months. Time in business is program-specific. Some underwriters weigh strong liquid assets and credit quality alongside a shorter history. A buyer a year or so into self-employment may still have options, though leverage and pricing can adjust.
Choppy statements. Deposits that swing wildly, or mix personal and business money, are the usual problem. Lenders want deposits that line up with the type of business. If your statements are messy, an accountant-prepared expense statement is an alternative path to explore.
Multiple accounts or entities. A business owner’s income can span several accounts, and each one has to be documented and tied to the borrower. This takes more skill and more paperwork. Scotsman Guide notes that bank statement loans help self-employed borrowers qualify on their actual income rather than the number that appears on their returns, and the multi-account case is where that “actual income” has to be proven carefully.
Partners and co-borrowers. Ownership share affects how much of a business’s deposits count as yours. If you own part of the company, expect the lender to count only your share. Treatment is program-specific.
Entity title. Bank statement loans underwrite the person. If you want an LLC to hold a rental, DSCR is often the cleaner route, subject to program terms.
Short-term rentals. If the plan is a short-term rental, short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
What Gets a File Flagged or Declined?
Most declines trace back to deposit quality, not the loan type. The fixes are usually available months before you apply.
- Commingled funds. Personal spending run through the business account blurs the picture. Separate them early.
- Large one-time deposits. A sale of equipment or a loan inflow that you can’t source gets stripped out.
- Transfers between your own accounts. These look like income at a glance and don’t count.
- Inconsistent months. Gaps and spikes force the lender to explain them, or to average more conservatively.
- Thin reserves. Reserves commonly run near six months of the housing payment, so empty accounts can sink an otherwise sound file.
- Weak credit. Credit tier affects leverage. Stronger scores earn the top of the range.
For contrast, the older tax-return model required the lender to establish an earnings trend from the prior two years of returns, as CFPB Appendix Q described. Bank statement programs sidestep that single-source trend, but they replace it with their own scrutiny of cash flow. Neither path is a shortcut.
Practitioner pattern worth knowing: files that get approved smoothly almost always arrive with deposits that tell one coherent story. A lender reading the statements should be able to guess your business from the deposit pattern. If they can’t, expect questions.
The Step-by-Step Path From Idea to Closing
The process is straightforward once the account work is done. The hard part is the preparation that comes before the application.
1. Decide on occupancy. Will you live in one unit or rent them all? 2. Pull 12 months of statements and review them for transfers, one-offs, and gaps. 3. Ask whether a standard expense factor or an accountant-prepared expense statement gives you the better income number. 4. Check credit and reserves against the program you’re considering. 5. Compare the bank statement route with DSCR if any part of the plan is pure rental. 6. Get the property appraised on the income-property form, and confirm how its rent will be treated. 7. Assemble the standard file items: the loan application, title and escrow, and proof of reserves.
For a deeper look at the low-down-payment angle for newer business owners, Lendmire’s piece How a Newly Self-Employed Buyer Purchases a 2-4 Unit Home With Low Down covers that situation directly.
Does the Decision Come Down to Occupancy and Scale?
Yes, for most buyers. If you’ll live in one unit, bank statements give you a lane that treats your real cash flow fairly and can reach high leverage on a primary residence. If you’re buying a rental to hold, DSCR usually pencils better and scales better. The flip point is the third or fourth purchase, where DTI starts to cap a personally underwritten strategy.
There’s honest uncertainty here too. Program terms shift across lenders, and what works for one file may not work for another. Tax treatment varies; consult a qualified professional. The cleanest way to avoid surprises is to run both lanes against your actual deposits and the actual property before choosing.
Reach the team at 828-256-2183 or through the quote request page. Bank statement lending is available through Lendmire’s consumer mortgage licensing in 16 states, and all qualification is subject to lender guidelines and credit approval.
Frequently Asked Questions
Can I use bank statements for a 2-4 unit if I won’t live in it?
Sometimes, but it is usually the weaker fit. A non-owner-occupied rental is business-purpose, and a DSCR loan, which tests the property’s rent against its debt, tends to match that situation better. Investment purchase leverage on bank statement documentation varies by lender, and investment cash-out tops out around 75% LTV.
How many months of statements do I need?
Twelve months is the common window in this lane, using business or personal statements. Some programs elsewhere in the market look at 24 months, as Scotsman Guide describes. The lender decides which account type and window it accepts.
Does every deposit count as income?
No. Transfers between your own accounts, loan proceeds, refunds, and one-time windfalls are removed. On business accounts the lender also applies an expense factor, so only a portion of gross deposits becomes qualifying income.
Can I buy a fourplex the same way I’d buy a duplex?
The mechanics are similar, but larger buildings get closer review of the rent schedule, reserves, and stabilization. Five or more units generally moves into commercial lending. Ask how a specific program treats three- and four-unit properties.
What if my business is less than two years old?
Time in business is program-specific. Strong credit and liquid assets can offset a shorter history with some lenders, though leverage and terms may adjust. The best move is to share your timeline early so the right program can be matched.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender around the property’s rental income rather than personal income documentation, subject to lender guidelines — which works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Scotsman Guide, “Rev Up the Engine for Non-QM Lending”
2. CFPB Ability-to-Repay Rule Summary
3. Scotsman Guide, “Don’t Shut the Door on Quality Borrowers”
4. CFPB Regulation Z Appendix Q
This article is part of Lendmire’s bank statement loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can You Use Personal Bank Statements for a Mortgage? · How to Buy Your First Home on Bank Statements When Newly Self-Employed · How Much Down Payment Does a Self-Employed Buyer Need?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.