
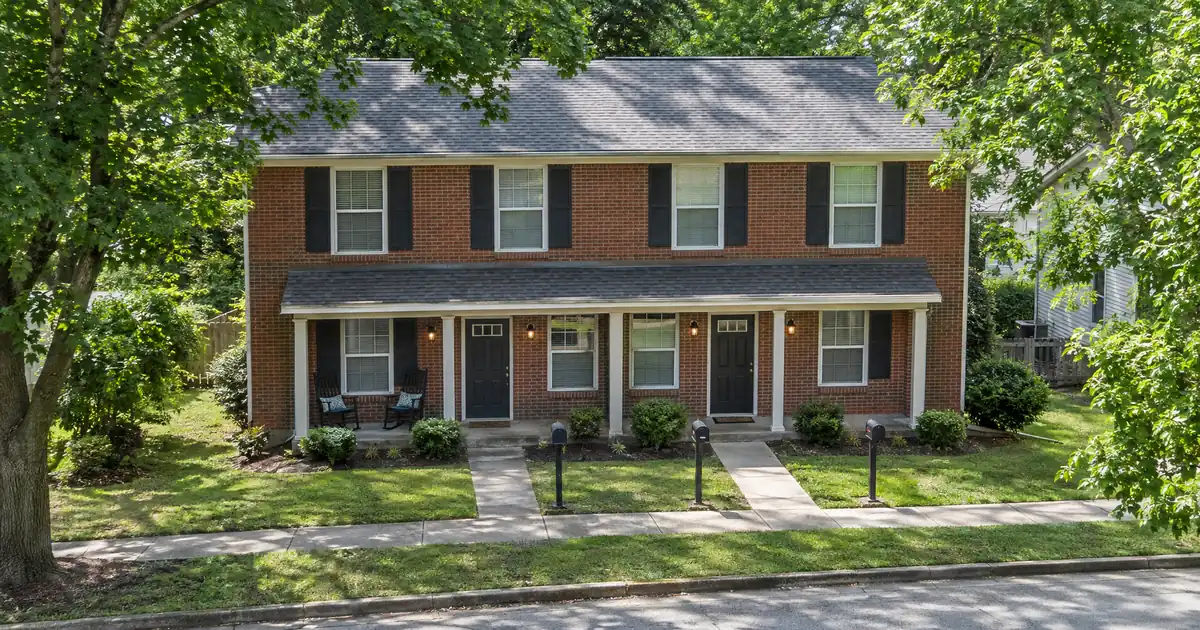
The Quick Read: Usually, yes. A revocable living trust is commonly accepted as the titleholder on a DSCR loan for a four-unit rental, though acceptance varies by program, and irrevocable, land, or layered trusts meet more friction. The trustee signs the loan documents, a real person still signs a personal guaranty, and the lender tests the building’s combined rent against its payment, not the trust itself.
- A revocable trust is the easiest trust type to place across the network.
- Rent from all four units is combined and compared with one payment.
- A trust is not a liability shield, so many investors add an LLC.
- Vesting at closing is cleaner than retitling a financed building later.
- Select programs in the network typically want 1.00 coverage or better, with leverage and credit tiers set by the program.
A fourplex is the largest building that still counts as residential for investor lending. Five units or more moves into commercial underwriting. That is why four units is a sweet spot, and why the trust question comes up so often with this property type.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 29, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 29, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Can a Trust Hold Title to a Fourplex?
Yes. Owning real estate in a trust is a legal-ownership question, and nothing stops a trust from holding a four-unit building. The harder question is whether a given loan program will lend to that trust.
Many investors set up a revocable living trust for estate planning. Nolo explains that a living trust lets property pass without probate while you keep control during your life. It also keeps the details of what you own out of the public probate file.
One catch applies before any lender gets involved. A trust only holds what you actually put into it. NCOA’s review of a Nolo trust product notes you must transfer assets into the trust after creating it. An unfunded trust is just paperwork.
How Does a DSCR Loan Treat a Trust-Owned Fourplex?
The lender looks at the property, not at the trust’s finances. DSCR stands for debt service coverage ratio. It compares the building’s monthly rent to its full monthly obligation: principal, interest, taxes, insurance, and any HOA dues (together, PITIA). The loan is reviewed primarily on property-level rental income covering the payment, subject to lender guidelines.
Trust vesting changes the paperwork and who signs. It does not change the math. On a fourplex, rent from all four units counts against one payment. That often gives a multi-unit building more cushion than a single-family rental in the same price range, though a vacant unit still bites.
Here is a picture. Say a trust-owned fourplex has rent that covers its full monthly obligation at around 1.2x. The lender runs the same test whether title sits in your name, a trust, or an LLC. The difference shows up in the document checklist.
Clearing 1.00 does not mean the building throws off positive cash flow. DSCR compares rent to PITIA only. Repairs, vacancy, management, utilities, and capital expenses sit outside the calculation. Budget for them separately.
Across the wholesale network, 1.00 is where many select programs start. A separate select-lender path takes coverage below 1.00, with leverage and terms adjusted. Stronger ratios generally open better pricing and leverage.
Who is underwritten? Typically the property is tested for rent, and the guarantor’s credit is pulled. Most programs want a score around 660, a 620 floor exists in parts of the network, and 700 or higher unlocks the strongest leverage tiers. DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
Which Trust Types Work?
The type of trust drives how much friction you meet. This table summarizes how most programs in the network tend to treat each one, subject to lender guidelines.
| Trust type | Who signs | Typical friction | First step |
|---|---|---|---|
| Revocable living | Trustee (often you) | Lowest | Certification of trust |
| Irrevocable | Independent trustee | Higher; some programs exclude | Confirm program acceptance first |
| Land trust | Trustee | Higher; extra document review | Ask before choosing a program |
| Trust owning an LLC | LLC manager | Varies; layers get scrutiny | Confirm the structure in advance |
Irrevocable and land trusts are not a flat no everywhere. Some programs accept them with more review, and others exclude them. Layered structures, where a trust owns a holding LLC that owns a property LLC, are commonly excluded. Check the structure before you commit to a program.
If you are also the trustee, the signing is simple. If there are co-trustees or a successor trustee, the certification must show who has authority to borrow and encumber the property.
Trust, LLC, or Personal Name?
Each form solves a different problem. The trust handles inheritance. The LLC handles liability. Neither one does the other’s job.
| Factor | Revocable trust | LLC | Personal name |
|---|---|---|---|
| Probate avoidance | Yes | Not by itself | No |
| Liability separation | None | Potentially | None |
| Privacy | Good | Good | Public deed |
| Lender paperwork | Certification of trust | Operating docs | Lightest |
A revocable trust offers no creditor protection. Nolo’s guide to living trusts and creditors explains that for liability purposes you are treated as the owner of the trust assets. On a fourplex, that matters more than on a single house. Four households live there, which means more potential tenant claims.
This is why a common approach is a trust that owns an LLC, and the LLC holds the building. That works with some programs and not others, so it is a question to ask before you apply. Loans to LLC-titled entities are subject to program eligibility. For a deeper look at the single-property version of this question, Lendmire’s piece Can a Trust Hold Title on a DSCR Rental Loan? covers it.
What Documents Will the Lender Ask For?
Expect a short, specific list. Lenders vary, but these are the usual items:
- A certification of trust, or in some cases the full trust agreement.
- Proof the trustee can borrow against and sign for the property.
- Matching names on the deed, note, insurance policy, and title commitment.
- A personal guaranty from a real individual.
- The standard property file: leases or market rent, insurance, and an appraisal.
An appraisal form only describes how the appraiser documents the building. It is not a loan-program rule.
Most failed trust files stall on the same three things: the trust was never funded, the trustee lacks borrowing power on paper, or a name on the insurance does not match the deed. Fix those before you submit.
The guaranty trips up a lot of new investors. A trust does not replace the guarantor. A real person stands behind the loan.
Should You Retitle Before or After the Loan?
Close in the final form you intend to keep. Buying a fourplex directly into your trust, or refinancing one into your trust, is the cleanest path. The refinance pays off the old loan, so there is nothing to trigger.
Moving a financed building into a trust later is where the risk lives. Most mortgages carry a due-on-sale clause, which lets the lender demand payment in full when title transfers. A federal law, the Garn-St Germain Act, carves out exceptions, including certain transfers into a living trust. But those protections were written around homes. The OCC regulation implementing the Act is the rule in question, and its specific limitations apply to a home occupied or to be occupied by the borrower.
A pure investor-owned fourplex may fall outside that framing. A law firm’s analysis says the statute and the regulation conflict on occupancy, so the protection is unclear. Another firm adds that transfers into an LLC get no protection at all.
So do not assume a deed into a trust is safe. Either get the lender’s consent, or wait for a refinance and vest title at that closing. That is often the easier route.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What If You Live in One of the Units?
Then it is not a DSCR deal. DSCR loans are for non-owner-occupied investment properties. Living in one unit of a fourplex is house hacking, and owner-occupied financing follows different rules and documentation. If you plan to move out later, that is a separate conversation. Settle your occupancy plan before choosing a program.
Which Structure Fits You?
Match the structure to the problem you are solving.
- Estate planning is the goal: a revocable trust holding title directly is the usual fit.
- Liability protection is the goal: an LLC, with the program confirmed first.
- Both matter: a trust that owns an LLC, if the program accepts the layer.
- Simplicity matters most: personal name now, with a plan to revisit at a later refinance.
Larger loans bring more guidelines. Standard programs run up to $3,000,000. Above $2,500,000 the network generally holds to 30-year fixed structures. Reserves commonly sit around 6 months of PITIA, stepping up to about 9 months above $1,500,000.
Leverage matters too. Most purchases land at 75% to 80% LTV on an investment property, and cash-out refinances top out around 75% LTV on a standard rental. Credit, reserves, and property eligibility still apply however much you put down. The full picture is in Lendmire’s complete DSCR loans guide. Every figure here varies by lender and program, since guidelines, property type, leverage, and credit profile all apply.
This article is general information, not legal or tax advice. Trust, deed, and liability questions depend on your state and your facts, so talk to a qualified attorney or CPA about your own situation. Tax treatment varies; consult a qualified professional.
Frequently Asked Questions
Can a trust be the borrower on a DSCR loan?
Often yes, especially a revocable trust, though it depends on the program. The trustee signs for the trust, and a real person usually signs a personal guaranty. Irrevocable and land trusts get more review.
Does putting the fourplex in a trust change my DSCR?
No. The ratio is the building’s combined rent against its payment, regardless of how title is held. Vesting affects paperwork, not the math.
Can I transfer my fourplex into a trust after closing?
You can, but it may trigger the due-on-sale clause on the existing loan. The federal exceptions were written around owner-occupied homes. Get lender consent, or vest title at a refinance instead.
Does a trust protect me from tenant lawsuits?
A revocable trust does not. You are treated as the owner for liability purposes. An LLC is the usual tool for separation, and an attorney should advise on the structure.
Is a fourplex treated differently from a larger building?
Yes. Four units is the residential ceiling. Five or more units is commercial multifamily, with different underwriting.
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire, a mortgage broker arranging DSCR investor loans through select lenders in its wholesale network across 41 markets, including Washington, D.C., can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets — 40 states plus Washington, D.C. — with DSCR eligibility generally reviewed by the lender on property cash flow instead of tax returns, subject to lender guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. NCOA’s review of a Nolo trust product
3. Nolo’s guide to living trusts and creditors
6. Johnson Legal: Transferring Title of Mortgaged Property
7. Wealth Counsel: Transferring Title of Mortgaged Real Property
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Plan and Use a Super Jumbo DSCR Cash-Out Refinance to Pay Off a Bridge Loan · How Lenders Underwrite a DSCR Cash-Out Refinance on a Condotel
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.