
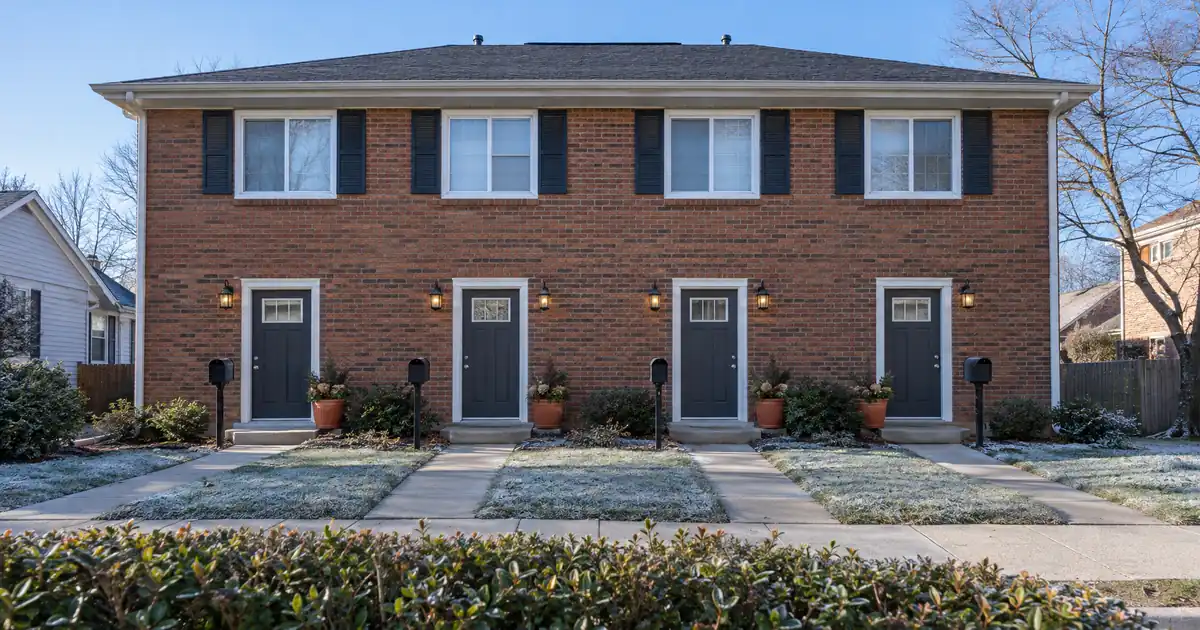
The Quick Read: A veteran can use a VA loan on a duplex, triplex, or fourplex only by certifying that they will live in one of the units as their home. The other units can be rented, and that rent can help the file, but the VA does not allow a pure rental purchase. The certification is a signed statement of intent, so it has to match your real plan. Plan on moving in within a reasonable time after closing, and on holding the paperwork that backs up the plan.
House hacking means living in one unit and renting the others. A VA loan is one of the strongest tools for it, because the program allows up to four units with 100% financing and no mortgage insurance. The tradeoff is the occupancy promise. This article walks through what that promise means, how rent counts, where the rules bend, and what a veteran’s decision looks like in practice.
VA payment estimate
Starting assumptions reflect an example price with no down payment and a first-use funding fee. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a VA loan quote.
Illustrative starting assumptions: a $350,000 price, no down payment with full entitlement, a first-use funding fee financed into the loan, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a VA loan quote; your rate is set by the lender at lock. The funding fee follows VA’s published table for the use and down payment entered; the residual-income figure is VA’s guideline for the region and family size, and the rough residual shown subtracts only the housing payment and the debts entered, while VA also deducts taxes, maintenance and utilities. Taxes, insurance and dues are editable estimates; closing costs are not included. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of the Department of Veterans Affairs.
Key Terms Defined
- Occupancy certification: a signed statement that you intend to live in the property as your home.
- Reasonable time: the window after closing in which you must move in.
- Reserves: your own cash, left over after closing, set aside to cover housing payments.
- Residual income: what is left of your monthly income after taxes, debts, and basic living costs. It is the controlling VA test.
- Entitlement: the amount of VA backing you have available, shown on your certificate of eligibility (COE).
- Overlay: a stricter rule a lender adds on top of the VA’s baseline.
What Counts as a Qualifying 2-4 Unit Property?
A VA-eligible dwelling is a building designed mainly as a home with no more than four family units. That comes from 38 CFR 36.4301 on eCFR, which also allows one added unit for each additional eligible veteran who co-owns. Cornell’s Legal Information Institute carries the same text.
| Property type | Fits the VA 2-4 unit lane? |
|---|---|
| Duplex | Yes |
| Triplex | Yes |
| Fourplex | Yes |
| Five or more units | Not on the standard dwelling definition |
| Residential building with one small business unit | Possibly, if primarily residential |
Mixed-use buildings get extra scrutiny. In general, the building must be primarily residential, and the nonresidential area has to stay small. Lenders look at this closely, so confirm the details for your specific property early.
Condos are a separate case. A condo project approved by the VA is limited to one single-family unit, so a condo purchase is not a way to buy a multiunit.
How Does the Occupancy Rule Work?
The rule is simple to state. By law, the veteran certifies an intent to personally occupy the property as a home. You either already live there, or you intend to move in and use it as your home within a reasonable time after closing.
The certification is made on VA Form 26-1820 at closing. According to the VA Lenders Handbook, Chapter 3, a lender may accept the certification at face value unless specific information shows you will not occupy in a reasonable time. If doubt does arise, the test is whether there is a reasonable basis to believe you can and will occupy as certified. A lender that cannot resolve the question goes to the VA.
Here is how that plays out in the file:
1. You sign the certification at closing.
2. The lender takes it at face value unless something in the file contradicts it.
3. The file stays consistent. Your address history, job location, and stated plans should all point to the same place.
4. You move in within a reasonable time.
What “Reasonable Time” Means
In the ordinary case, the handbook treats about 60 days after closing as reasonable. A longer window can work if you certify a specific move-in date and a particular future event makes earlier occupancy impossible. Even then, occupancy more than 12 months after closing generally cannot be treated as reasonable.
Two points tend to surprise buyers. First, 60 days is the ordinary standard, not a rigid cutoff. Second, the 12-month ceiling is an outer limit for special situations, not a normal planning window.
Rule, Overlay, or Folklore?
Most confusion about VA occupancy comes from mixing three different things. The table separates them.
| Topic | What the VA text says | What lenders often add | Where folklore creeps in |
|---|---|---|---|
| Move-in timing | Reasonable time; about 60 days is ordinary | Some want a signed move-in date | “It’s a hard 60-day deadline” |
| Minimum stay | The handbook text sets when you must move in; no minimum stay found | Some lenders expect a stay of about a year | “The VA requires one year” |
| 3-4 unit income test | Reserves and landlord capability | Some use a self-sufficiency ratio | “The VA requires a self-sufficiency test” |
| Credit floor | VA sets no minimum score | Lenders set their own | “The VA needs a 620” |
The “one year” idea deserves a careful word. The handbook language covers when a veteran must move in. It does not set a minimum stay. A lender, though, may have its own policy, and any move-out raises the question of whether your original intent was genuine. That is why timing and the reason for a move matter more than a fixed number of months.
The same applies to credit. The VA itself sets no minimum credit score. Across the wholesale programs Lendmire places VA loans with, the decision-score floor starts at 580, and some lenders set a higher floor. Treat the floor as a lender matter, subject to lender guidelines.
What Does Living There Look Like in Practice?
Because intent is judged from the file, the practical move is to make your plan easy to believe. Think of it as a short checklist:
- Pick your unit before you write the offer. Know which one you will live in and why.
- Align your address records. Driver’s license, voter registration, mail, and bank statements should shift to the property.
- Keep your plan realistic. If your job is 90 minutes away, expect questions.
- Set a move-in date. Even when it is not required, it helps.
- Put your own name on the utilities for your unit.
- Keep a copy of the certification and any move-in documentation.
None of this is a formal VA proof list. It is what a careful file looks like. If the file raises doubt, the lender has to resolve it, so the cleaner the story, the smoother the review.
Renting the Other Units: Can Rent Count Toward Qualifying?
Yes, in many cases, and this is where the loan gets powerful for house hackers. Per the VA’s underwriting chapter, prospective rent from the other units can be counted as income on a multiunit property where you occupy one unit, but only if two conditions are met:
1. You have a reasonable likelihood of success as a landlord.
2. You have cash reserves of at least six months of your housing payment (principal, interest, taxes, and insurance).
Those reserves must be your own funds. Gifts do not count, equity does not count, and cash-out refinance proceeds do not count. If each unit is separate and not under one mortgage, the six-month reserve applies per unit.
How Much Rent Counts
Not all of it. In general, only a portion of the rent counts, because vacancy, repairs, and turnover are real. Treat 75% of documented rent as the working figure, a number lenders commonly apply, and confirm the exact factor for your file. Rent from the unit you live in never counts. Only the other units’ rent does.
That means the loan’s value is real but not unlimited. Rent can raise your qualifying income. It cannot replace the need for cash behind it.
The Self-Sufficiency Question
Many sites say the VA requires a self-sufficiency test on triplexes and fourplexes. That is a familiar idea from FHA lending. In the VA handbook text reviewed for this article, the requirements are the reserves and the landlord-capability standard, not a stated self-sufficiency ratio. Some lenders do apply their own version as an overlay. Ask the lender up front which standard applies, because it can change how a 3-4 unit file is built.
Appraisal and Tenants
The VA appraisal produces the Notice of Value, which sets the reasonable value and caps the loan. If tenants are already in the building, the appraiser will need access to the units, and market rent for each unit is part of the picture. The standard minimum property requirements apply to every unit, not only yours. A tired unit you plan to rent can hold up the file.
Occupied units also mean leases. Get copies early. Leases help support the rent figure when a lender wants documentation.
Where the General Rule Bends
Occupancy has real exceptions. These are the edge cases most worth knowing.
Delayed occupancy. If a specific future event keeps you from moving in right away, a longer window can be reasonable with a certified move-in date. The 12-month outer limit still applies.
A spouse or dependent child. In specified circumstances, such as an active-duty absence, a spouse or dependent child can satisfy the occupancy rule. The details live in Chapter 3 of the handbook, so a lender should confirm how it applies to your situation.
Repairs and improvements. If substantial work prevents you from living there at first, you may certify in writing to occupy after completion. Confirm the handling with your lender before you rely on it.
Two eligible veterans. Co-owners can add a unit to the dwelling limit, up to the regulation’s cap. Joint loans carry their own file requirements, so raise this at the start.
The IRRRL. A VA interest rate reduction refinance only requires you to certify that you previously occupied the home. That matters if you moved out of an earlier house hack and later want to refinance it.
A home you already occupied. If you lived in a property before the new loan, the rent from it can offset that property’s payment but cannot be added to your income. The reserve requirement drops to three months per rental, and a two-year rental history is expected. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Pure rentals. Not allowed. A building bought for investment does not fit the program.
Moving Out Later: How to Think About It
This is the question every house hacker eventually faces. A VA multiunit does not force you to refinance if you move, and the handbook text found does not set a minimum stay. But the certification was a statement of intent at closing, so the reason and timing of a move out matter.
| Timing | Typical reason | How it tends to be viewed |
|---|---|---|
| Within the first few months | Unexpected orders, family emergency | Documented, unexpected events usually read as genuine |
| Mid-first-year | Job change, relocation | Depends on the file and your original plan |
| After the first year | New station, new city | Generally the easiest to explain |
An early move-out with no clear cause raises the question of whether you ever planned to live there. If you already knew you would move soon, such as a known upcoming move to a new duty station, say so at the start and talk through it with the loan officer before you sign. Hiding it is the real danger.
Moving out can also affect your entitlement. Buying a 2-4 unit uses some of it. Whether you can buy again with VA backing, and with what down payment, depends on what entitlement remains, so speak with a loan officer about your specific numbers.
A Few Scenarios Without the Math
The veteran separating from service. She buys a duplex near her new job, moves into one unit within weeks, and rents the other. Occupancy is straightforward. The question mark is reserves, since she must show six months of her own cash if she wants the rent to count.
The veteran with known orders in a few months. He wants a fourplex but expects to leave soon. Here the honest conversation matters more than anything. If his intent to occupy is genuine, the file can reflect that. If he already plans to rent every unit, this program is not the right fit.
The deployed servicemember. His spouse will live in the property while he is away. In specified circumstances a spouse can satisfy the rule, so this is a question to raise with the lender before the contract, not after.
What Can Go Wrong
- Signing an untrue certification. The statement is binding. Signing it with no intent to occupy is a serious problem.
- Thin reserves. Without six months of your own funds, the rent may not count. Gifts and cash-out proceeds do not fill the gap.
- Assuming 100% of rent counts. Only part of it does, and the unit you occupy contributes nothing.
- Skipping the overlay conversation. A lender’s own rules on 3-4 units or credit can differ from the VA baseline.
- Weak units. Property condition standards apply to the whole building.
What the Loan Itself Looks Like
For a purchase, VA lending allows 100% financing with no down payment as long as the price is not above the appraised value. It also carries no mortgage insurance and, for borrowers with full entitlement, no VA loan limit. With remaining entitlement, a down payment may be required, so speak with a loan officer rather than guess.
There is a VA funding fee, which can be financed. On a first-use purchase it is 2.15% with less than five percent down, 1.5% with five to under ten percent down, and 1.25% with ten percent or more down. For subsequent use with less than five percent down, it is 3.3%. Veterans receiving compensation for a service-connected disability, and other exempt groups, do not pay it.
On underwriting, residual income is the controlling test. The 41% debt-to-income figure is a guideline, not a cap, and a higher ratio simply needs residual income well above the table. Your certificate of eligibility decides eligibility, and service requirements are the VA’s rules. All of this is subject to lender guidelines and full file review.
Across the wholesale programs Lendmire works with, the files that move smoothly on a multiunit are the ones where the veteran’s story, reserves, and documents all line up before the appraisal is ordered. Lenders can handle a house hack comfortably. What slows them down is a file where the occupancy plan, the rent assumptions, and the cash on hand do not match.
For readers whose next question is about equity later on, Lendmire’s piece VA Cash-Out Occupancy Rules for a 2-4 Unit Primary Home picks up where this one ends. And if you want the program basics, Lendmire’s VA loan programs page covers eligibility and structure in more detail.
Your Pre-Closing Checklist
- Confirm your certificate of eligibility and remaining entitlement.
- Decide which unit you will live in.
- Know your planned move-in date.
- Gather six months of your own-funds reserves, documented.
- Collect leases for any occupied units.
- Ask the lender whether it applies a self-sufficiency overlay on 3-4 units.
- Ask how it treats rental income and which percentage it uses.
- Ask what it would want to see if your plans change after closing.
- Check that the whole property meets minimum standards.
If you are buying a home and want to see whether a VA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Lendmire is a mortgage broker, not a lender, and every program figure here is subject to lender guidelines and full file review. Nothing here is a commitment to lend.
Frequently Asked Questions
How soon do I have to move in after closing?
About 60 days is the ordinary standard in the VA handbook. A longer period can be reasonable only if you certify a specific move-in date and a particular future event makes earlier occupancy impossible. Occupancy more than 12 months after closing generally cannot be considered reasonable.
Can I rent the other units from day one?
Yes. House hacking assumes you will rent the other units, and that rent can count toward qualifying if you meet the landlord-capability and six-month reserve conditions. Only a portion of the rent counts, and the unit you live in adds nothing to income.
Is there a one-year minimum stay required by the VA?
The handbook text reviewed sets when you must move in but does not state a minimum stay. Some lenders expect about a year as their own policy, and any early move-out invites questions about your original intent. Ask your lender what its policy is before you sign.
Does the VA require a self-sufficiency test on a triplex or fourplex?
The handbook text reviewed requires reserves and landlord capability, not a stated self-sufficiency ratio. Some lenders add their own version as an overlay. Ask which standard your lender applies before you choose a 3-4 unit building.
Can my spouse satisfy the occupancy requirement for me?
In specified circumstances, yes, such as when a servicemember is away on active duty. The details are in Chapter 3 of the VA Lenders Handbook, and the lender decides how they apply to your file. Raise it before you write an offer.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire is a mortgage brokerage (NMLS# 2371349) licensed for consumer mortgage lending in 16 states, arranging FHA, VA, conventional and jumbo purchase and refinance loans through a wholesale lending network. Eligibility is determined by the lender on each file. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. 38 CFR 36.4301 (Cornell Legal Information Institute)
3. VA Lenders Handbook, Chapter 3: The VA Loan and Guaranty
This article is part of Lendmire’s VA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: VA Cash-Out COE and Entitlement Rules for a VA Jumbo Loan · VA Cash-Out vs Conventional Cash-Out: Which Gives a Veteran More? · Type I vs Type II VA Cash-Out Definitions and Recoupment Rules
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.