
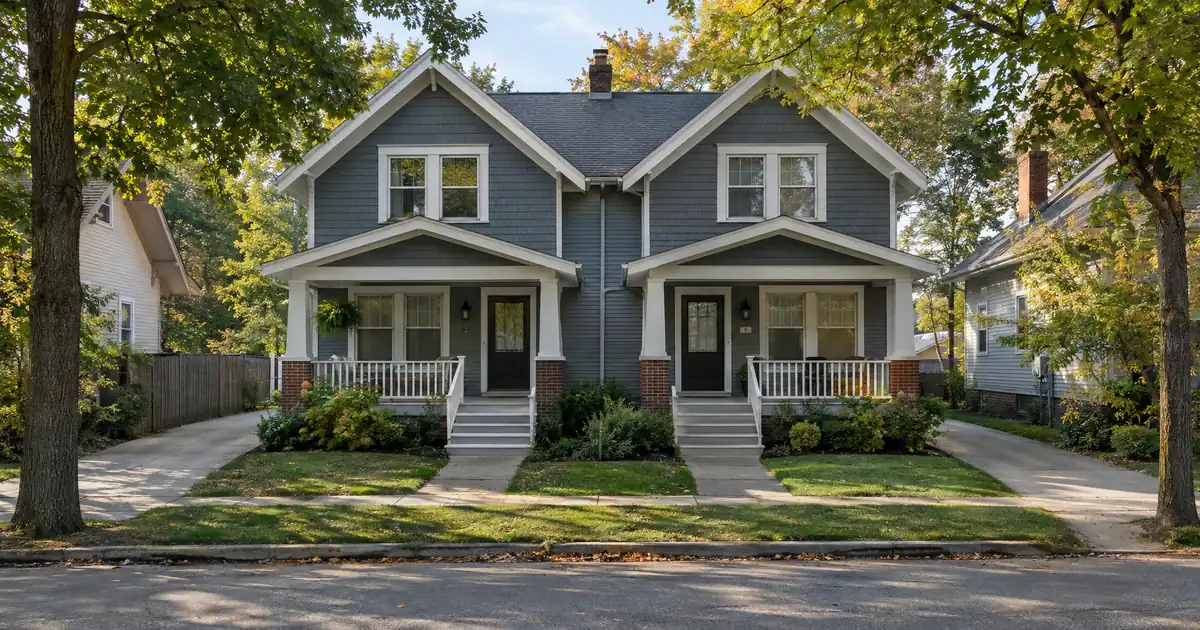
The objection comes up on almost every Brunswick file: the rent doesn’t cover the debt on a single-family house at this price. The objection is half right. A 3-bedroom at the median price is a thin DSCR cash-out candidate. A small multi-unit building is a different story, and that gap is where the equity in this market gets unlocked.
DSCR Cash-Out Calculator
Run the cash-out numbers in Brunswick, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance in Brunswick, Ohio is underwritten primarily on the property’s rental income measured against its full monthly obligation (principal, interest, taxes, insurance), with the file built around seasoning, a 75 percent leverage ceiling and lender-reviewed rent. Redfin puts the median sale price near $325,000, so the equity case depends on property type.
- Median-priced 3-bedroom rents sit near 1.0x coverage at the full 75 percent ceiling.
- Dropping leverage to 65 percent lifts the same house toward roughly 1.1x.
- Two-bedroom units are about 64 percent of apartment rentals.
- Population is flat, so the thesis rests on rent and equity.
What the Brunswick Numbers Say
Brunswick is the largest city in Medina County, with a Census-estimated population of 35,166, down 0.7 percent from the 2020 count of 35,426. Nobody should underwrite this market on population growth. It’s a stable Cleveland-Akron commuter suburb on I-71, and the case rests on how much equity an owner has built and what the rent supports.
On prices, the sources disagree, and the gap matters. Redfin shows a $325,000 median, up 7.4 percent year over year, with homes taking 40 days to sell against 23 the prior year. Zillow shows a lower $278,950 average home value, up 3.0 percent, which reflects a different methodology. This article uses the Redfin figure for modeling. Either way, owners who bought a few years back are sitting on real appreciation, and the slower days-on-market is a reminder that the equity is paper until it’s refinanced.
Rents are messier. Zumper reports an average of $1,899, while Apartments.com shows $1,168, Rentcafe $1,345 and Redfin $1,435. No vacancy or cap-rate source turned up, so none gets quoted here. The spread tells its own story: Brunswick has a thin, poorly covered rent market, and an appraiser may land well below an asking-rent listing. Build a cushion.
The Coverage Math (Modeled, Not Sourced)
The workable cash-out candidates here are duplexes and lower-leverage single-family houses. Run the numbers on a median 3-bedroom: using the $2,100 rent that Prop-Metrics reports from Rentcast for ZIP 44212, against a modeled $325,000 value, monthly rent is about 0.65 percent of value.
Those are modeled inputs. Take full PITIA, meaning 30-year principal and interest at an assumed rate in the high-6s plus Ohio-average taxes and insurance, at the 75 percent cash-out ceiling. Coverage lands just under 1.0x. Cut the leverage to 65 percent and the same house moves to roughly 1.1x including taxes and insurance. Not exciting. Workable.
Now a duplex, with an assumed $400,000 value and two 2-bedroom units at $1,500 each, conservatively below the $1,550 Rentcast 2-bedroom median. That’s $3,000 in gross rent on one loan. At 75 percent leverage with taxes and insurance in the stack, coverage runs around 1.1x. The duplex clears where the house doesn’t, because rent stacks faster than debt does.
Most standard DSCR programs are built around a 1.00x benchmark, since rent covers the obligation at that level. Some lenders will review sub-1.00 files, but those typically mean lower leverage, different pricing, more reserves or stronger compensating factors. A house that models just under 1.0x isn’t dead. The options a lender may review include a lower-leverage structure, an interest-only feature on some programs, or a rent figure supported by a stronger appraisal. Eligibility depends on lender guidelines, credit approval and property review.
Seasoning, Leverage and Where the Proceeds Go
The equity-extraction mechanics are simple. Cash-out refinances on this platform generally cap at 75 percent LTV, with roughly six months of ownership measured from title recording. Credit tiers typically start at a 620 floor and step up through 660, 680 and 700, and reserves run about six months of PITIA. Loan sizes go up to $3,000,000 on standard programs. Program details are subject to change and to lender overlays, so confirm them before planning a draw.
One thing gets lost in the math: the 75 percent ceiling is a cap, not a cash figure. Available proceeds depend on rent used for lender review, PITIA, reserves and that ceiling working together. A house that models at 1.0x at 75 percent may only support a smaller draw at 65. The capital then funds the next acquisition, a down payment or a rehab on the existing building. For the broader mechanics, the cash-out refinance walkthrough covers the structure, and refinancing options lays out the alternatives. LLC-titled properties are possible, subject to lender program eligibility.
Why Duplexes Fit the Tenant Base
Rentcafe reports that 2-bedroom floorplans are about 64 percent of Brunswick’s apartment rentals and 1-bedrooms 28 percent. Roughly 94 percent of rental communities are low-rise, garden-style, and about a quarter of housing is renter-occupied. A duplex built from two 2-bedroom units sells tenants exactly what they already rent. The income stack is realistic.
Large 3-plus-bedroom rentals serve a thinner slice. That’s the whole reason single-family cash-out math runs tight here.
Side-by-side duplexes do exist and get renovated for rent. A fully remodeled 3-bedroom, 1.5-bath side-by-side with a walkout basement and new mechanicals showed up in recent rental listings on Homes.com. No source gives a count of 2-4 unit properties in the city, so assume inventory is limited and confirm with MLS data. Triplexes and fourplexes are likely scarce.
Competition matters too. Newer build-to-rent product with attached garages is pulling in renters, and about a third of rental communities were built since 2000. That sets a rent ceiling. An older duplex with dated interiors won’t hold the same rent as a new build, so underwrite to appraised market rent rather than asking rent.
Where the Tenants Work
Demand here is employment-driven. Data USA shows health care and social assistance as the top resident sector at 3,039 people, followed by manufacturing at 2,602 and retail at 2,398. Cleveland Clinic runs the Brunswick Family Health Center in the city with a 24-hour emergency department, and Medina Hospital, a 148-bed acute care facility, is the nearby inpatient anchor.
On the industrial side, the Medina County Economic Development Corporation notes three fully developed industrial parks off State Route 303 next to I-71, including about 38 acres designated a Foreign Trade Zone. Clinical staff and plant workers are documentable W-2 tenants. That supports long holds and clean lease files. It does not raise coverage by itself.
No four-year college sits in the city, so student demand is not a driver. Skip that angle.
Where the Equity Sits
No submarket-level price or rent source turned up, so this section stays qualitative.
Pearl Road and Center Road corridors. The likeliest home of older duplex-type inventory, with Pearl Road carrying over 16,000 vehicles a day. The large named apartment communities here are professionally managed and not DSCR targets. The small buildings are.
Southlake at Brunswick Town Center. A New Urbanist townhome district described by the City of Brunswick as the residential portion of the town center. Attached product raises lender questions about HOA rules and eligibility, so check guidelines before counting on a draw here.
SR 303 and I-71 industrial edge. Close to warehouse and manufacturing jobs and suited to workforce rentals. No pricing data found.
Newer subdivisions. Ridgeline Chase and Meadows View skew owner-occupant, and rent-to-value is probably weaker. Skip them for cash-out math.
What a Clean File Looks Like
Lendmire’s deal desk tends to see the same friction in suburban markets like this one: the owner’s rent assumption runs well ahead of the appraiser’s. The cleaner files come in with complete leases, entity documents, title and property details ready for lender review, and with a rent figure that already sits near the conservative end of the local range. Files that arrive with a fresh insurance quote and a realistic reserve plan tend to move through lender review with fewer revisions.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Brunswick, OH, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Investors can reach Lendmire at 828-256-2183, or review the state hub for Ohio DSCR investor loans. For the general framework, Lendmire’s primer on DSCR loans covers the basics, and the program-to-program comparison shows how this differs from conventional underwriting. Verify current local rental rules, taxes and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Brunswick, Ohio?
Qualification centers on the property’s rent against its full obligation, with a 1.00x coverage benchmark common across standard programs. Expect about six months of seasoning from title recording, credit starting around a 620 floor, and reserves near six months of PITIA. Lender guidelines, credit approval and property review decide the outcome.
What are the requirements for an investment property loan in Brunswick, Ohio?
Typical files need a rentable property, a lease or appraiser-supported market rent, entity documents if titled in an LLC, and reserves. Manufactured homes, log homes and barndominiums fall outside these programs. Loan sizes run up to $3,000,000 on standard programs, subject to lender program requirements.
Is a flat population a problem for a Brunswick cash-out refinance?
It limits upside, but it doesn’t break the file. The population is down 0.7 percent since 2020, so coverage depends on in-place rent and appraised value, not growth. Health care, manufacturing and retail employment anchor the tenant base. The risk is overestimating rent in a market where listing averages range from $1,168 to $1,899.
How much cash can a Brunswick owner actually pull out?
It depends on rent used for program review, PITIA, reserves and the 75 percent ceiling working together. A house near 1.0x at full leverage may support a smaller draw at lower leverage. A duplex with two 2-bedroom units generally has more room. It is never a guaranteed figure.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C., with DSCR eligibility generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025.
The underpriced piece of Brunswick is the older side-by-side duplex near the Pearl Road and Center Road corridors. Its two 2-bedroom units match the dominant renter demand, while the median-priced single-family house gets the attention and thins the coverage.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin — Brunswick Housing Market
2. Census-estimated population of 35,166
3. Zillow
4. Zumper
5. Prop-Metrics
6. RentCafe — Apartments for Rent Brunswick OH
7. Homes.com
8. Data USA
9. Brunswick Family Health Center
10. Medina Hospital
11. Medina County Economic Development Corporation
13. a 2026 Scotsman Guide Top Mortgage Workplace
14. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Parma, Ohio: Can Your Parma Rent Cover the New Loan Payment? · DSCR Cash Out Refinance in Elyria, Ohio: The 2026 DSCR Financing Guide to the LCCC Corridor · DSCR Cash Out Refinance in Newark, Ohio: Pulling Equity from Small Multifamily
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.