
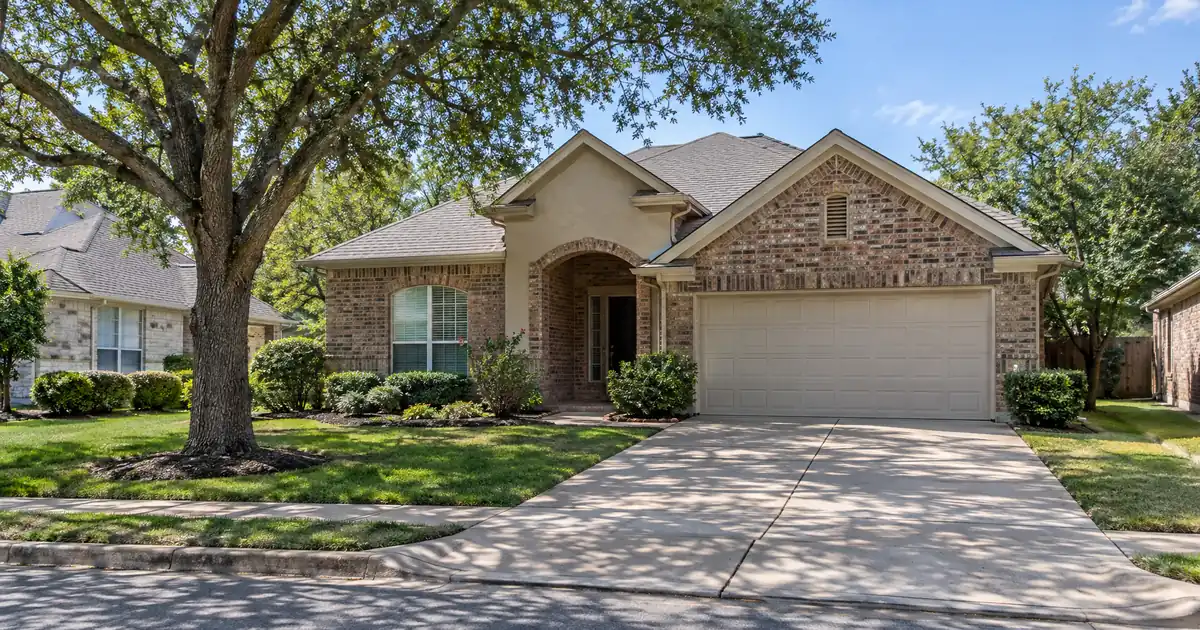
Flower Mound investors holding a rental bought a few years back are sitting on appreciated equity. The median sale price is $640K, up 4.0% year over year, per Redfin. Rents have not kept pace. Portal data shows them roughly flat over the past year, so the next 6-18 months will reward investors who size a cash-out refinance on coverage rather than on the equity headline.
Lendmire is a DSCR-focused mortgage broker, and its DSCR program footprint covers Flower Mound, Texas as part of a 41-market reach that includes Washington, D.C. This report looks at how equity extraction pencils in a town where renters are a small minority and almost everything is a large single-family house.
DSCR Cash-Out Calculator
Run the cash-out numbers in Flower Mound, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A cash-out refinance on a Flower Mound rental is underwritten primarily on the property’s rent measured against its full monthly obligation, and in a town where the median sale price is $640K per Redfin, the coverage ratio, not the equity, sets how much can come out.
- Renters are only 18% of households, per RentCafe.
- Wellington is the most plausible SFR submarket by price.
- Lakeside DFW is an appreciation story, not a coverage story.
- Two-to-four-unit stacking is scarce, so single-family rent carries the file.
- Cash-out requires about six months of title seasoning and a 75% LTV ceiling.
- Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Flower Mound Market Snapshot
A quick read on the Flower Mound investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $640K median (Redfin) |
| Employment | 29,000+ employees (Texas Health Careers) |
| Vacancy | 3.2% (NeighborhoodScout) |
Why the 75% Cap Is Not the Binding Number
The cap is 75% LTV, but in Flower Mound coverage will usually bind first. Modeled on full principal, interest, taxes, and insurance, a median-priced house renting at typical portal figures covers well below 1.00x at the maximum leverage. Getting near the baseline takes a much smaller loan against the value.
The 1.00x DSCR benchmark is common because at that level the rent covers the property’s payment. Some lenders review lower ratios with compensating factors such as lower leverage, stronger reserves, or different pricing. Others review no-ratio scenarios. Eligibility depends on lender guidelines, credit, reserves, and property review. The mechanics of how DSCR coverage is calculated are straightforward: monthly rent divided by the full monthly obligation, including taxes and insurance.
Here is the modeled picture. The inputs are assumptions, not sourced market facts: a 30-year amortization, taxes and insurance at Texas-average loads, and a $640K value. Rent is the $2,575 RentHop 3-bedroom average. At 75% LTV, coverage lands around 0.6x including taxes and insurance. At roughly 50% LTV it moves to the low 0.9s. Substitute the $3,100 four-bedroom figure and 50% leverage gets close to 1.10x. Better, not generous. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Nobody should read that as a verdict against the market. It is arithmetic about price level. Flower Mound is priced like an owner-occupied suburb with an average household income of $189,356, per the Flower Mound Chamber of Commerce. Landlords there are paid in appreciation first and rent second.
What Does the Rent Evidence Actually Say?
Rent sources disagree, so the useful move is to treat them as a range. RentHop shows averages of $2,225 for two bedrooms, $2,575 for three, and $3,100 for four, with a current-listing median of $2,895. RentCafe puts the all-unit average at $1,965, but that measures large apartment buildings, not houses. Zillow shows a house median near $3,000, though that data is older.
The gap matters. A house earns roughly 50% more than the average apartment, which supports a single-family thesis. It also means apartment concessions set the market-rate ceiling. Apartment List reports a median rent of $1,959, down 3.4% year over year, while RentCafe reports a 1.2% rise. The two conflict, and underwriting should assume flat rents rather than growth. A conservative rent in the qualifying calculation is the right habit here.
No city-wide vacancy figure was found. The only vacancy number is 3.2% for Lakeside DFW, from NeighborhoodScout, and it covers one neighborhood.
Where Equity Can Come Out: Submarkets in Order of Fit
Wellington is the submarket most likely to clear coverage at moderate leverage, and Lakeside is the one least likely. Neighborhood rent sources are thin, so the ranking leans on price, tenure, and sourced rent snapshots rather than a full rent roll.
Wellington: The Plausible SFR Pocket
Movoto shows a median list price of $680K. Blue Fuse Realty calls it the largest community in town, at 2,400+ homes, with deep resale inventory. Depth matters for a refinance because appraisers have comparable sales to work with, and an investor who needs to exit has a market to sell into.
Redfin’s rental snapshot shows median rents of $3,100 in Wellington and $3,295 in Wellington Estates. Against the $680K list median, that is about 0.46% of price per month. That figure is Lendmire Research’s calculation from two portals with different dates, so read it as directional. It is the best ratio sourced in town, and it is still thin. Modeled with taxes and insurance, Wellington coverage sits below 0.7x at the 75% ceiling. The realistic routes for an owner there are a low-leverage cash-out, a lender program that reviews sub-1.00 coverage, or an interest-only structure. Each is a path a lender would review, not a promise. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Lakeside DFW: Priced for Appreciation
The town describes Lakeside DFW and Lakeside Village as a 160-acre mixed-use development on Lake Grapevine. It sits beside the Lakeside Business District, a 1,500-acre district with more than 100 businesses. Movoto’s median list price for the neighborhood is $1.32M.
A house at that basis would need rent far above local norms to reach coverage. The neighborhood’s actual rental supply is apartment complexes, where one-bedroom asking rents run roughly $1,500-$1,735 per Redfin listings. The math is blunt. A cash-out at Lakeside is a bet on price growth, and it suits only low-leverage refinances where the investor is comfortable that coverage will be the lender’s hardest question.
Tenant demand is real. The adjacent business district supplies corporate relocations and professionals. Demand is not the problem. Price is.
River Walk at Central Park: The Healthcare Node
Texas Health Presbyterian Hospital Flower Mound has 99 beds and more than 500 physicians on its medical staff, and its parent system employs 29,000+ people, per Texas Health Careers. The hospital was built in the River Walk at Central Park development, which is surrounded by medical office projects. It is the best fit in town for healthcare-worker tenancy. No price or rent data was found for the area, so no coverage figure is offered. It is a demand anchor, not a modeled submarket.
Bridlewood, Canyon Falls, and the Spillover
Bridlewood is a golf community that skews owner-occupied and high-end, and sourced prices are inconsistent, so no figure is cited. Canyon Falls is newer construction with final phases still to open. New supply tends to matter more for future buyers than for current rental owners. Redfin shows only a handful of Flower Mound listings under $300K, and those results are mostly Lewisville and Argyle addresses. Adjacent Lewisville is the realistic workforce-rental spillover market, though it was not researched here.
The Employer Base Behind the Tenant Pool
Employment here is about as stable as suburban Texas gets. The Town of Flower Mound reports 44,454 employed residents, 97.3% of those 16 and older, and 32.7% work in management, business, or finance. The town’s workforce page reports more than 85% of adults with post-secondary education.
The largest employers in the 500+ band include CTDI, Lewisville ISD, MI Windows & Doors, and Texas Health Presbyterian Hospital Flower Mound. Stryker Communications, the Town itself, and Likewize fall in the 300-499 band. CTDI has roughly doubled in size over the last several years per local press, though that figure is dated and is treated here qualitatively. DFW Airport sits three miles away and is the largest regional job center, but no headcount was found.
Incomes here favor owning over renting, which explains the 18% renter share. The rental pool is small, and mostly people who can afford a three- or four-bedroom house by choice. That is a thin-but-stable tenant base, not a deep one. Where vacancy would hurt is the stretch between leases on a $3,000 house.
The Property-Type Problem: No Small Multifamily
Anyone hoping to stack income across a duplex or fourplex will not find it in Flower Mound. RentCafe says 74% of apartment buildings were built since 2000, and nearly all rental communities are low-rise garden-style complexes, with no mid-rises or high-rises. Renters number only about 4,932 households. No sourced evidence of a meaningful two-to-four-unit supply turned up. ADUs are a niche add-on at best.
So the coverage case rests on single-family rent. That is the structural reason cash-out leverage here is lower than in markets where a fourplex spreads the payment across four leases. Multi-unit investors typically look at Lewisville or Denton instead, neither of which was researched for this report.
Compare the two property types by the ratio that matters:
| Factor | Flower Mound SFR | Small multifamily |
|---|---|---|
| Sourced supply | Dominant | Scarce |
| Rent-to-value | Thin (about 0.46%-0.54%) | No data |
| Income streams | One lease | Multiple |
| Cash-out fit | Low leverage | Not evidenced |
A Worked Scenario: Seasoned House, Low-Leverage Extraction
Run the numbers on a hypothetical three-bedroom in Wellington that an investor has owned for over a year, with modeled rent of $3,100. Assume the appraisal supports a value near the $680K neighborhood median. Nothing here is a sourced transaction. It is a structure illustration.
At the 75% ceiling, modeled coverage including taxes and insurance comes in under 0.7x. Step the request down to around 50% LTV and it rises to roughly 0.85-0.9x. Drop to 40% LTV and coverage crosses 1.00x. Whether the cash produced at 40% is worth the trouble depends on the original balance. A low-basis owner may still extract a meaningful sum. An owner who bought near peak will not. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
If the file lands below 1.00x, the options a lender would review include a sub-1.00 program, an interest-only structure, or a lower loan amount. Qualification remains subject to lender guidelines, credit approval, and property review. Loans to an LLC are reviewed per lender program requirements, and title vesting is worth settling before the refinance begins. The cash-out qualification details cover seasoning, which runs about six months from title recording, along with reserves of about six months of PITIA. Credit tiers run from a 620 floor up through 660, 680, and 700. Loan amounts go up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network.
DSCR files in markets like this one typically look the same from the broker’s desk. The appraisal is rarely the problem, because a house at this price point has recent comparable sales nearby. The rent schedule is. Files tend to arrive with an optimistic lease figure, and the coverage ratio on a conservative rent comes out a full notch lower. The stronger files run the numbers at two leverage points before submitting, so the borrower already knows which loan amount clears coverage.
Appreciation Versus Cash Flow
This is the central tension in town. Sources differ on where prices sit, and the gap comes down to methodology: Redfin’s price-per-square-foot and sales-volume readings show a market that is still appreciating and actively trading, while NeighborhoodScout and U.S. News report median home values that land noticeably apart from one another. Because of those differences, this report leans on Redfin’s sale-price median throughout for consistency, and it treats the other figures as context rather than as competing answers.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Flower Mound, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Appreciation is what creates the extractable equity. Rent is what limits how much of it comes out. An investor can refinance the gain, but only at a loan size the rent can carry. Growth of a few percent a year on a $640K house adds more equity than a year of net rent does. The refinance converts that into capital, at a leverage the rent supports.
The stronger play might be a smaller cash-out now, left to season further, rather than a maximum-leverage pull. The alternative view is to extract as much as coverage allows and redeploy it into a higher-yield market. That is a genuine toss-up, and it depends on where the next purchase pencils. For a version of that approach across assets, investor refinance options are worth a look, and the guide “Where DSCR and Conventional Diverge” applies when a borrower’s personal income is the alternative.
Investors should verify current local rental rules, taxes, and insurance with qualified local professionals before sizing any refinance. For statewide context, see Lendmire’s overview of DSCR loans in Texas.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Flower Mound?
Qualification centers on the property’s rent relative to its full monthly obligation, with a 1.00x baseline common across programs. Other factors include at least six months of ownership from title recording, a credit score at or above the 620 floor, reserves of about six months of PITIA, and leverage capped at 75% LTV. Final eligibility depends on lender guidelines, credit, and property review.
What are the requirements for an investment property loan in Flower Mound, Texas?
Expect a single-family or similar eligible property, documented rent, a minimum credit score of 620, and reserves around six months of PITIA. Manufactured homes, log homes, and barndominiums fall outside these programs. Since the town is almost entirely large single-family houses, most Flower Mound rentals sit squarely within eligible property types. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Why does coverage run so thin on a Flower Mound house?
Price outruns rent. A $640K median sale price, paired with portal rents of roughly $2,575-$3,100 for three- and four-bedroom houses, produces a rent-to-value ratio around half a percent a month. With taxes and insurance included, coverage at the 75% ceiling lands well below 1.00x. Lower leverage is the usual fix.
What credit score ranges may DSCR lenders review for a Flower Mound rental property?
Lenders in the network generally review tiers at 620, 660, 680, and 700, with 620 as the floor. Lendmire, NMLS# 2371349, arranges DSCR investor loans, and the property’s rental income is central to review. Higher scores tend to open up higher leverage, subject to lender guidelines.
Is Lakeside DFW a realistic cash-out market?
Only at low leverage. A $1.32M median list price per Movoto means coverage on a long-term lease is very unlikely to clear at typical leverage. The neighborhood’s rental supply is mostly apartments, with one-bedroom asking rents around $1,500-$1,735. Lakeside suits owners refinancing for appreciation reasons who accept a small loan amount.
The Next Step
Pull rent comparables for the exact house, not the town. The spread between RentHop’s $2,575 and $3,100 figures is the spread between a file that works and one that does not. Build a rent range from current listings of similar size within the same neighborhood, run coverage at both 50% and 60% LTV including taxes and insurance, and only then decide whether the equity is worth pulling. Review my scenario for a preliminary read, or call 828-256-2183. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Flower Mound rewards owners who treat the house as a long-term hold and the refinance as a modest withdrawal. The limit is the rent, not the equity.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. Lender review centers on the property’s rental income rather than the borrower’s traditional personal-income documentation, which suits self-employed operators and portfolios beyond four financed properties. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and is also a 2025 Scotsman Guide Top Workplace. Details appear in Lendmire’s 2026 Top Workplace announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Flower Mound Housing Market
2. RentCafe, Flower Mound Rent Trends
5. Flower Mound Chamber of Commerce, Living in Flower Mound
6. RentHop
7. Movoto
9. Lakeside DFW and Lakeside Village
10. Town of Flower Mound, Lakeside Business District
11. Texas Health Presbyterian Hospital Flower Mound
12. recognized by Scotsman Guide as a 2026 Top Workplace
13. a 2025 Scotsman Guide Top Workplace
14. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Flower Mound, Texas: The 2026 DSCR Financing Guide to Wellington · DSCR Cash Out Refinance in Texas City, Texas: Refinery Tenants and a 75 Percent Ceiling · DSCR Cash Out Refinance in Lufkin, Texas: The 2026 DSCR Financing Guide to the Timberland Rental Belt
Guides: Investment Property Cash-Out Refinance in Flower Mound, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.