
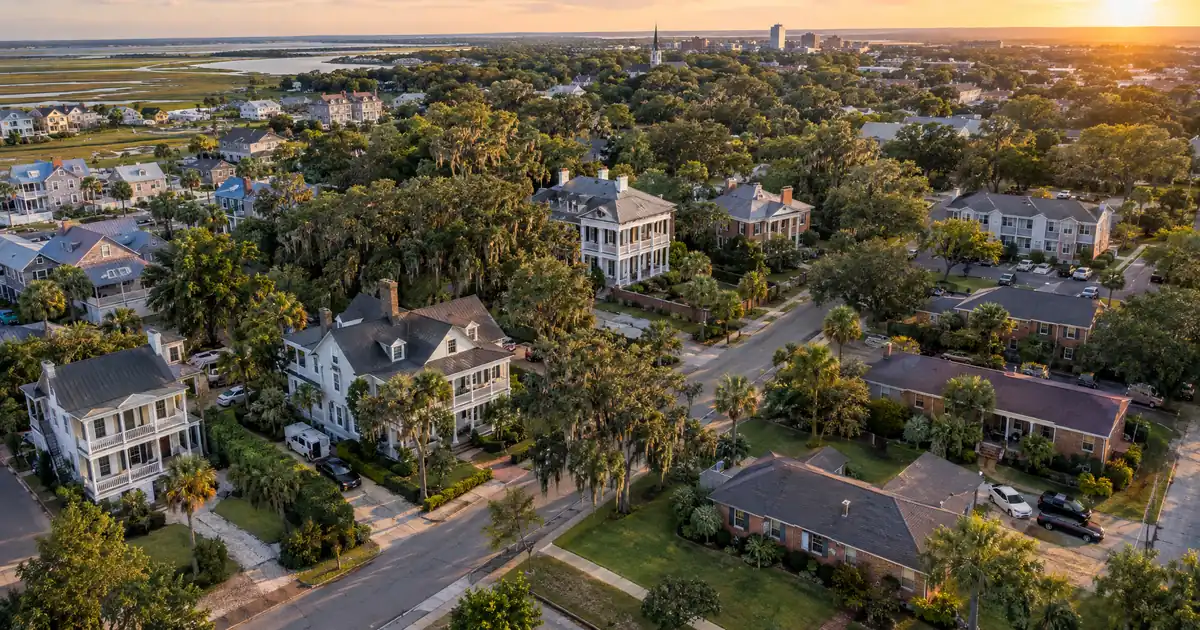
The Spartanburg metro added residents at a pace of 39 percent between 2010 and 2024, against 9.9 percent for the US overall, according to USAFacts. That growth has not turned into fast price gains inside the city itself. Zillow puts the typical Spartanburg home value at $236,395, up just 2.2 percent over the past year (Zillow). For a landlord who already owns here, that gap defines the strategy: demand is deep, but drift will not build the equity for you.
The Quick Read: A cash-out refinance in Spartanburg, South Carolina fits investors holding small-unit rentals or older workforce houses, and it is underwritten primarily on the property’s rental income measured against its full monthly obligation, typically capped at 75 percent loan-to-value, so the equity available depends on rent coverage rather than on how much the house has appreciated.
DSCR Cash-Out Calculator
Run the cash-out numbers in Spartanburg, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow shows a $236,395 city home value, up 2.2 percent, so equity comes from basis and improvements (Zillow).
- BMW Manufacturing employs more than 11,000 people in the county.
- Average apartment rent is $1,240, up only 0.38 percent year over year (RentCafe).
- A Converse Heights four-unit listing showed $3,885 a month in leases (Homes.com).
Spartanburg Market Snapshot
A quick read on the Spartanburg investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 142 sales (Redfin) |
| Typical rents | $900/unit prior (Redfin) |
| Recent appreciation | +2.2% (Zillow Home Values, Spartanburg) |
| Employment | 200 jobs (SC Governor’s Office, BMW press) |
How the Equity Gets Extracted
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Lendmire structures DSCR scenarios for investors targeting Spartanburg, South Carolina and places them with wholesale lenders across 41 markets, including D.C. The mechanics of a cash-out here follow the standard investor pattern, and the equity-extraction mechanics page covers the full process.
Four parameters matter most on a Spartanburg file, all subject to lender guidelines and varying by borrower and property:
- Leverage ceiling. Cash-out refinances typically cap at 75 percent LTV. That is lower than the purchase-side ceiling, so an investor who bought at 80 percent should not assume the same number applies on the way out.
- Seasoning. Most programs look for roughly six months of ownership, measured from title recording.
- Coverage. The baseline benchmark is 1.00x: qualifying monthly rent divided by principal, interest, taxes, insurance, and any HOA dues. Some lenders review lower ratios, but usually with lower leverage, stronger reserves, or different pricing.
- Reserves and credit. Reserves of about six months of that full obligation are typical, and credit tiers generally start at a 620 floor.
The cash you actually receive is the residual after the 75 percent cap, the payoff of the existing loan, and reserves. It is never a fixed figure. (Titling the property in an LLC is common, subject to lender program eligibility.) Investors new to the product can start with Lendmire’s primer on DSCR loans.
Appreciation Won’t Do the Work
Spartanburg’s headline price numbers point in different directions, and the spread is instructive. Zillow’s index shows the city value at $236,395, up 2.2 percent. Houzeo reports a median sale price of $266,500, up 6.6 percent year over year, with 1.16 months of inventory (Houzeo). Redfin’s three-month city median comes in lower, at $230K, up 0.4 percent, though price per square foot rose 9.3 percent to $153 (Redfin). Different methodologies explain the spread: an index of values versus medians of closed sales.
Read together, that is a range of roughly flat to mid-single-digit growth. Redfin’s data distributed through Greenville Business Magazine describes price growth as slowed.
The implication is blunt. A landlord who bought a few years ago at a fair price should not count on market drift to create a large appraisal gap. Cash-out capacity here comes from three places: a below-market purchase basis, a renovation that lifts value and rent, or a lease-up of units that were underpriced. Recent sale volume helps on the appraisal side, since Redfin counted 142 homes sold in May, up from 129 a year earlier. Appraisers have fresh comps. Flat medians alongside rising price per square foot is a mixed signal, and the more honest read is that quality product is repricing while the average is not.
Worked Math: House Versus Small Multifamily
The three scenarios below use modeled assumptions, not sourced deal data. Each divides monthly rent by full monthly obligation, including taxes and insurance, on a 30-year amortization at 75 percent LTV.
The single-family case. Run the numbers on a three-bedroom house appraising at the Zillow city average of $236,395. Apartment Finder’s three-bedroom average rent is $1,423, and 2-bedrooms average $1,217 (Apartment Finder). On those inputs the coverage ratio lands right around 1.0x, barely clearing the benchmark. Not much cushion. If insurance reprices upward or the appraisal lands light, the number slips under 1.00. At that point a lender may review a sub-1.00 program or an interest-only structure, subject to credit approval and property review.
A four-bedroom changes the picture. Apartment Finder shows a four-bedroom average of $1,733, and a local property manager listed a four-bedroom house at $1,900 (SPM & Investments). At the same modeled value, that rent produces coverage near 1.3x. The three-bedroom premium over a two-bedroom is only about $200, while the fourth bedroom adds much more. Thinking out loud: the smarter refinance candidate is often the four-bedroom at a lower basis, not the three-bedroom at the average.
The small-multifamily case. Picture an investor holding a four-unit building in Converse Heights. One listing there showed all four units leased for $3,885 a month combined, or $46,620 a year, roughly $971 per unit (Homes.com). The research brief carries no sale price, so assume a modeled $450,000 appraised value. At 75 percent LTV, coverage runs about 1.4x. Lose one unit to vacancy and it still holds near 1.1x. Four leases share one obligation, so a vacancy is a partial loss, not a cliff. A single house at a similar total price offers no such buffer.
In markets like this one, DSCR files typically show a split. Single-family workforce rentals arrive with coverage hovering near the benchmark and depend heavily on the appraiser’s rent schedule and the insurance quote. Small multifamily files usually carry stronger coverage but need in-place leases documented cleanly, because the appraisal leans on them. The stronger submissions tend to include a fresh insurance quote and lease copies before the file reaches the lender.
Where the Equity Sits
Property-type fit matters more than neighborhood label here, because Spartanburg County’s stock is heavily single-family. A state housing agency infographic built on American Community Survey data shows single-family detached homes at 70.6 percent of county units (SC Housing). Mobile homes make up another 13.8 percent, and manufactured housing falls outside these DSCR programs. Duplexes through fourplexes are scarce, which means thin comps and little negotiating room at purchase, but also a real premium on stabilized small-unit rent rolls at refinance.
Converse Heights. The historic, tree-lined single-family district is the city’s priciest area, and published median figures conflict, so treat prices there qualitatively. Its value for cash-out is the small-unit product. A nearby fourplex listing showed prior rents of $900 per unit on some units against total potential income of $3,550 a month (Redfin). That is a value-add gap between in-place and potential rent. A refinance on the stabilized roll may appraise above the purchase basis, but only if the renovation and lease-up actually happen.
Northside, Park Hills, Hillbrook. These are the lowest-rent submarkets. Rent.com puts one-bedroom averages at $737 in Hillbrook and $887 in Park Hills, against a $1,004 city average (Rent.com). Low basis, thin rent ceilings. A listing there bundled three duplexes into a six-unit package, the kind of multi-unit product that can carry coverage even when individual rents are modest. Underwrite from the actual rent schedule, not the neighborhood label.
East Pearl and the Wofford area. RentCafe shows $1,555 a month here, the top of its neighborhood list. Student and staff demand supports the rent, but basis runs higher, so coverage is not automatically better than on the northside.
Downtown, Grain District, Hampton Heights. Revitalizing and walkable, with lofts and townhomes. Rent.com shows a downtown one-bedroom at $1,110. These are appreciation-leaning submarkets where a cash-out depends on the appraiser crediting recent improvement.
Mill-village housing such as Fernwood. Older stock with a wide price range. Rents and prices vary block by block, which rewards investors who can identify the underpriced unit.
Demand Anchors Behind the Rent Rolls
Rent growth is weak, so tenant demand has to be judged on employment stability instead. Spartanburg’s anchors are unusually concentrated and unusually steady.
BMW Manufacturing employs more than 11,000 people at its Spartanburg plant, and the plant sits in the county with the largest BMW manufacturing operation in the world. The South Carolina governor’s office confirmed a $200 million press shop investment creating 200 new jobs. Roth Capital, a commercial real estate investor, estimates 30,000 to 40,000 supply-chain jobs tied to the plant (Roth Capital); that is a buyer’s estimate, so treat it as directional. The state’s largest-employers list also names Michelin North America, Optum Services, Plastic Omnium Auto Exteriors, Siemens Industry, and Walmart.
Healthcare and education add a second layer. Spartanburg Regional Healthcare System operates the 231-bed Mary Black Campus and the 125-bed Cherokee Medical Center, with more than 1,000 providers on staff. A regional fact sheet from a few years back counted 9,648 employees in the system and 6,063 in the county school districts. Then there are the colleges: USC Upstate says Spartanburg has seven colleges and universities with nearly 15,000 students, including a medical school whose trainees rotate through the health system.
Census Reporter’s ACS profile counts 38,910 residents in the city (Census Bureau QuickFacts), inside a metro of 395,900. RentCafe shows 47 percent of households renting. A small city, a large employment base, and a renter pool that does not depend on any one landlord’s tenant quality.
What Could Compress the Refinance
Rents are essentially flat. RentCafe’s $1,240 average is up 0.38 percent from $1,235, and Roth Capital reports Spartanburg multifamily rents near $1,333 versus $1,400-plus in Greenville, which supports the commuter-value story but not rent growth. Underwrite at current rents with no increase assumed.
Supply is the other watch item. Colliers data summarized by Catalyst Capital Partners put the Greenville-Spartanburg multifamily pipeline at 2,188 units, under one year of supply at recent absorption. New apartments compete with small landlords for the same tenants, and that pressure appears to be fading, but it is a metro figure, not a city vacancy rate. The brief found no reliable city-level vacancy or cap rate, so none is claimed here. Investors should verify current local rental rules, taxes, and insurance with qualified local professionals.
Putting the Proceeds to Work
A cash-out refinance is only as good as the next deal it funds. In Spartanburg, the cleaner sequence is to pull equity from a stabilized small-unit property and redeploy it into a lower-basis house or another multi-unit building. Owners weighing the alternatives can compare conventional vs DSCR on investor loans and consider refinance paths for investor properties beyond cash-out. Statewide program context sits on the South Carolina DSCR investor loans page. Investors can reach Lendmire at 828-256-2183 to model a specific property.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Spartanburg?
Qualification centers on the property’s rent relative to its full monthly obligation, with a 1.00x benchmark common on standard programs. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Exact eligibility depends on lender guidelines and property review.
What are the requirements for an investment property loan refinance in Spartanburg, South Carolina?
Expect an appraisal with a rent schedule, proof of insurance, lease copies where units are occupied, and reserves. Eligible types include single-family and small multifamily; manufactured homes are not reviewable through these programs, which matters given that mobile homes are 13.8 percent of county units. Standard programs generally reach up to $3,000,000.
DSCR vs. conventional financing
Two common ways to finance an investment property in Spartanburg, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Does a flat Spartanburg market still support a cash-out?
Sometimes, but the equity has to be created rather than inherited. With Zillow showing 2.2 percent annual growth, cash-out capacity typically comes from a low purchase basis, a renovation, or lifting below-market rents, as in the Converse-area fourplex where prior rents sat near $900 per unit.
Which Spartanburg property types tend to produce the strongest coverage?
Four-bedroom houses and small multifamily. A $1,900 four-bedroom listing and a $3,885 four-unit rent roll both outperform a typical three-bedroom rented near $1,423 at city-average value. Duplexes and fourplexes are scarce, so comps require care.
How does DSCR lender review differ from a bank’s approach in Spartanburg?
Lendmire places DSCR loans and the file rests on the property’s rental income instead of the borrower’s traditional personal-income documentation and DTI, subject to lender guidelines. That structure helps investors whose income is complex but whose rent roll is clean.
The Number Appraisers Will Lean On
Spartanburg’s median may sit flat, but Redfin counted 142 homes sold in a single month, up from 129, and that comp volume is what turns a renovated rental into a cash-out file.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income instead of personal income paperwork, subject to lender guidelines. Recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2026, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. USAFacts, Spartanburg metro population
2. Zillow Home Values, Spartanburg
3. RentCafe, Spartanburg rent trends
4. Homes.com
5. Redfin, Spartanburg housing market
6. Redfin
7. South Carolina governor’s office
8. Houzeo, Spartanburg housing market
9. Greenville Business Magazine
10. Apartment Finder
12. SC Housing
13. Rent.com
14. Roth Capital
15. lmi.sc.gov — Community Profiles Spartanburg
16. Spartanburg Regional Healthcare System
20. a 2025 Scotsman Guide Top Mortgage Workplace
21. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Spartanburg, South Carolina: Converse Heights Equity Extraction · Cash Out Refinance Investment Property in Greer, South Carolina: BMW Workforce Equity Play · DSCR Cash Out Refinance in Greer, South Carolina: Equity Extraction on Workforce Rentals
Guides: Investment Property Cash-Out Refinance in Spartanburg, SC · Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.