
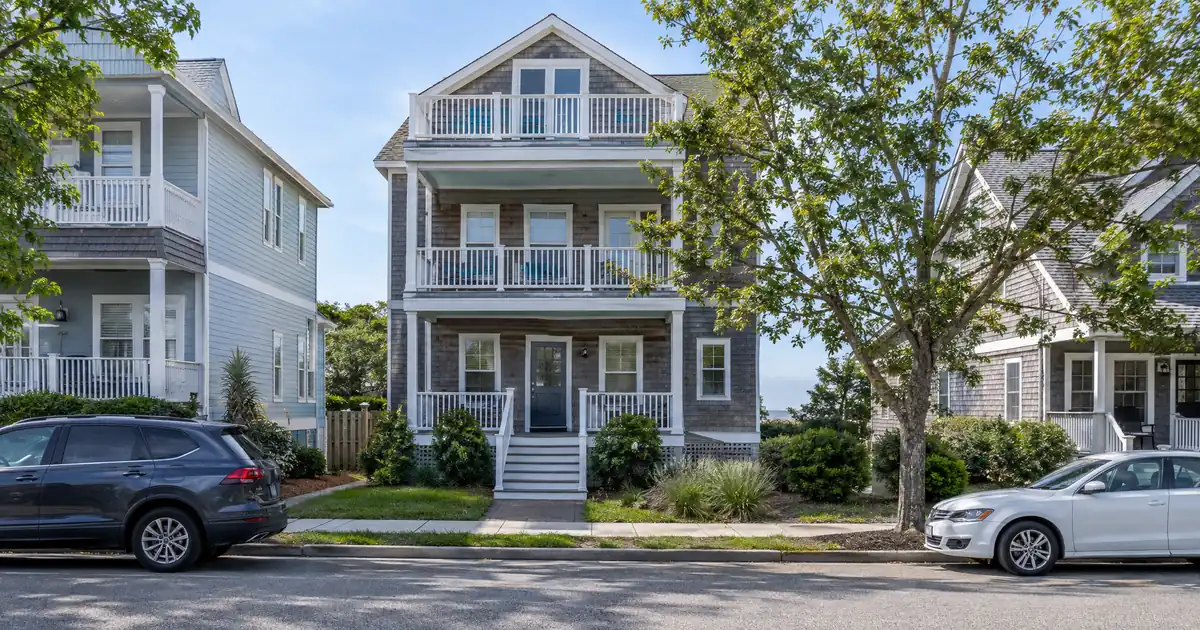
Your Nags Head house probably has real equity in it. The rent to support borrowing against that equity probably doesn’t. Zillow puts the median rent in Nags Head at $2,650, while its average home value sits at $719,037. That gap is the whole story of cash-out refinancing here. The equity is easy to see, but the coverage ratio is where the file gets decided.
Investors underwriting deals in Nags Head, North Carolina can use DSCR programs Lendmire arranges, available across 41 markets, including D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, which means it places these files with lenders rather than lending itself. This article skips purchase mechanics. It covers pulling equity out of a beach-market rental you already own and whether the math supports it.
DSCR Cash-Out Calculator
Run the cash-out numbers in Nags Head, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A cash-out refinance in Nags Head, North Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the rent has to carry taxes and insurance as well as the loan. The equity is the easy part. Coverage is the hard part.
- Median rent against average home value is thin for a single unit, so leverage usually needs to come down.
- Cash-out caps at 75% LTV, with about six months of seasoning from title recording.
- Sales volume is shallow, so appraised value can swing and comps matter more than headlines.
- The Outer Banks hospital’s staffing gap points to durable long-term tenant demand.
- Inland and workforce-priced cottages pencil better than oceanfront or golf-resort product.
Nags Head Market Snapshot
A quick read on the Nags Head investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $730,000 median (Homes.com – Nags Head houses) |
| Typical rents | $2,650 median (Zillow Rental Manager – Nags Head) |
| University enrollment | ~2,100 students systemwide (College of The Albemarle) |
| Employment | ~800 full/part-time employees (Dare County HR) |
The Rent-to-Value Problem Nobody Mentions
Nags Head single-family rent runs about 4.4% of value per year at the median, which is thin for a cash-out file. That figure comes from the $2,650 median rent and the $719,037 average value above. Plenty of DSCR markets clear the benchmark comfortably. This one mostly doesn’t, unless you choose the asset carefully.
The Zillow rent range runs from $1,500 to $5,950, and the spread tells you something. Rent scales with bedroom count and finish level, but the asset price scales faster. Homes.com shows listings from $79,000 to $4,750,000, and its median sale price is $730,000. That is a different methodology from Zillow’s value index, so treat the two as a range rather than one figure. The Zillow rent snapshot is also dated (it reflects an earlier period, with rent up $850 over the prior year at the time), so read it as directional.
Here is the modeled math, using assumptions rather than market data. Take a cottage valued at $500,000 and rented at a modeled $2,650. The DSCR ratio is monthly rent divided by the full monthly obligation: principal, interest, taxes, and insurance. That ratio, modeled on a standard 30-year amortization with North Carolina average taxes and insurance included, looks like this:
| Cash-out LTV | Modeled coverage | Read |
|---|---|---|
| 75% | About 0.85x | Below the 1.00x benchmark |
| 65% | Borderline, near 1.0x | Tight, no cushion |
| 55% | About 1.1x | Clears with room |
Run the numbers this way and a median-rent cottage at max leverage falls short. Sub-1.00 files aren’t dead, but they get harder. Select lenders may review a sub-1.00 program, an interest-only structure, or reduced leverage with stronger credit and more reserves, subject to lender guidelines and credit approval. None of that is a given, and each option changes the pricing and the proceeds.
Flood and wind coverage matter on a barrier island. Verify current local rules, taxes, and insurance with qualified local professionals before you underwrite.
Thin Volume Makes Appraisals a Coin Flip
Nags Head sells few houses in any given month, so one appraisal can land far from where you expect. Redfin recorded a median sale price of $1.1 million, up 50.9% year over year, but that rested on only nine homes sold in the month, versus 24 a year earlier. Zillow’s index, by contrast, shows values down 0.1% over the past year. Same town, opposite signals.
The Village at Nags Head shows the same volatility. Redfin’s neighborhood page logged a $510,000 median, down 37.2% year over year, on a sample of one sale. One sale. Nobody should underwrite a refinance thesis on that number in either direction.
Here is the practical takeaway. Don’t build a cash-out plan around a single month’s median. Pull a long trailing window, gather comps that match your bedroom count and proximity to the water, and assume the appraiser will do the same. Days on market, at 56 on Redfin and 57 on Homes.com, say the town is liquid enough. They don’t say comp depth is deep.
(An appraiser working a market this thin has to reach for comps, and a reach can cut either way.)
The Cash-Out Mechanics at 75%
Cash-out on a DSCR file tops out at 75% LTV, with about six months of ownership measured from title recording. Those are the two constraints that shape equity extraction here. Typical guideline figures on most files:
- Seasoning: about six months from title recording. If you bought recently, the clock matters more than the market.
- Minimum coverage: the standard benchmark is 1.00x, measured on rent used for lender review against PITIA.
- Credit: a 620 floor, with better tiers at 660, 680, and 700 generally earning more flexibility.
- Reserves: about six months of PITIA, and about nine months on balances above $1,500,000.
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network.
Proceeds are not a guaranteed figure. They depend on rent used for lender review, PITIA, reserves, and the 75% ceiling, all subject to lender guidelines. Lendmire’s DSCR cash-out refinance page covers the structure in more depth, and the refinance side explains how it differs from rate-and-term.
Consider a scenario where an investor owns a cottage free and clear and wants maximum proceeds. At 75% the coverage likely falls under 1.00x on median rent, so the real decision is whether to take less cash at lower leverage, or find a qualifying structure at higher leverage. Lower leverage often wins. The smaller draw still funds a down payment elsewhere, and the file actually clears.
Where DSCR and conventional diverge matters here too. A retiree-heavy owner base, with a median age of 58.4, often holds seasonal or rental income that conventional underwriting can’t easily count.
Where It Pencils (and Where It Doesn’t)
South Nags Head and Old Nags Head Cove are the submarkets where large single-family rentals carry a cash-flow case. The Village at Nags Head is where the appreciation story lives and the coverage story dies. Nags Head housing is mostly single-family “beach box” and cottage stock, with bedroom count driving income far more than unit count.
South Nags Head is entirely residential, with no commercial strip, and runs along the oceanside south of Whalebone Junction. Local brokerage commentary flags it for strong rental histories. It works best for larger-bedroom homes with documented year-round or seasonal income. Underwrite it on a lease or a documented rent schedule, not on a wish.
Old Nags Head Cove sits on the westside of Highway 158, with canal and soundfront homes, a community soundfront beach access area, and boater-friendly appeal. It tends to price below oceanfront product. That lower basis is exactly why the coverage ratio looks better than it does at the beach.
Bonnet Street and the Gallery Row area gets flagged locally for newer rental homes with good cash flow. There is no verified price or rent breakdown for it, so treat it as a place to go comp, not a conclusion.
Skip the Village at Nags Head for cash flow. Average sale prices there run $748,813, up 3%, but the golf-resort basis overwhelms any long-term rent, and the Redfin volume problem above applies. Hold it for appreciation, not coverage.
Old Nags Head Place is a newer cottage-style subdivision near Jockey’s Ridge. It appeals to design-minded buyers, but nothing in the research shows it pencils on rent. The Nags Head Beach Cottages Historic District has 41 contributing buildings and historic-property constraints that limit its DSCR relevance.
One property-type note. Duplexes and triplexes do trade in Nags Head, but they are a minority of inventory. A small multifamily asset can cover its obligation with more cushion than a single-family beach house, and scarcity cuts both ways. Good ones are hard to find, and owners rarely refinance them. Manufactured homes, log homes, and barndominiums fall outside these programs entirely.
The Hospital Is the Tenant Story
Nags Head has no large university, military base, or manufacturer, so long-term tenant demand rests on healthcare, government, and hospitality. The town has about 3,160 residents and a median household income of $91,264. The township, which is closer to the real labor pool, holds 12,376 residents. Tourism is the engine: the Outer Banks Visitors Bureau reports 12,260 tourism jobs in Dare County, about 45.5% of all jobs. Dare County recorded $2.1 billion in visitor spending, fourth-highest among North Carolina counties.
The long-term rental signal comes from Outer Banks Health. It lists 630+ team members, 204 licensed beds, and more than 50,000 total visits a year, and it is the only hospital on the Outer Banks. The Coastland Times reported that the hospital had 75 open positions, about 14% of its workforce, with housing cited as a reason candidates turned down offers. The Outer Banks Voice documented the hospital seeking rental units for staff who had lost their long-term rentals.
That points to real, price-inelastic demand for year-round housing from clinical and support staff. It is the tenant profile a DSCR file wants behind a 12-month lease. The caution is that these reports are older, so this is a directional signal rather than a current vacancy figure. No verified vacancy number exists for the town.
Long-term management infrastructure exists too. Village Realty manages over 950 rental properties across the barrier islands, and dedicated long-term rental divisions operate separately from weekly vacation books. That is a practical channel for placing and managing a 12-month tenant.
What the File Looks Like on Barrier-Island Refis
Lendmire’s deal desk sees a consistent pattern on files from resort-driven coastal markets. The rent schedule and appraised value are the two documents that move the file, and they rarely agree on the first pass. The cleaner files usually show a signed lease or a property manager’s rent history, a fresh insurance quote in hand before submission, and leverage set conservatively against a thin comp set. The common friction point is an owner who assumes the top-of-market appraisal and the top-of-range rent will both arrive. Usually only one does.
Cash Out, Then What?
Extracting equity only makes sense if the money goes somewhere that earns more than the carry on the new loan. Nags Head’s own rent-to-value math suggests the next dollar may work harder in a lower-priced market where rent covers the obligation with room to spare. The proceeds can fund a down payment elsewhere without selling the coastal asset, if the coverage works on the refinanced property itself.
The honest version: if the refinanced Nags Head house only covers at reduced leverage, the draw is smaller. A smaller draw with clean coverage beats a larger draw on a file that pends. Sort out what DSCR qualification actually looks like before you price the plan. Anyone holding LLC-titled property should confirm entity eligibility, subject to lender program eligibility. To talk through the numbers, reach Lendmire at 828-256-2183.
Anyone exploring a broader footprint can start with North Carolina DSCR investor loans.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Nags Head, NC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
Can a Nags Head cottage clear 1.00x on a cash-out at 75% LTV?
Usually not at median rent. A modeled $500,000 cottage renting for a modeled $2,650 a month lands near 0.85x once taxes and insurance are included at 75% LTV. Higher-rent, larger-bedroom homes or lower leverage can change that, subject to lender guidelines.
Does the thin sales volume really affect my appraisal?
Yes, it raises the odds of a surprise. Redfin logged just nine sales in one month against 24 a year earlier, so a single comp can swing the value. Pull a longer window and match bedroom count and location.
How long do I have to own before cashing out?
About six months from title recording is the typical seasoning guideline. Recently purchased properties and those held in an entity can have different treatment, so confirm the exact terms for the program.
Is the Village at Nags Head a good refinance candidate?
Better for appreciation than coverage. Its golf-resort basis is high relative to long-term rent, and the neighborhood’s recorded medians swing on very few sales. Cash-out there usually means lower leverage.
Does the hospital really support long-term rental demand?
It supports it directionally. Outer Banks Health has 630+ team members, and local reports tied unfilled positions to housing scarcity. That points to steady demand from year-round staff, though the reporting is older and no vacancy figure is verified.
The Real Choice
Every Nags Head cash-out ends in one of two trades. Take the larger draw at 75% LTV and accept that coverage probably falls short of 1.00x, which means sub-1.00 structures, more reserves, and a harder file. Or take a smaller draw at lower leverage, clear the benchmark comfortably, and accept that less capital comes out of a house that looks richer on paper than its rent supports. Nags Head makes you choose between the equity you can see and the coverage you can prove. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing, arranging DSCR loans in 40 states plus Washington, D.C., which makes 41 markets in total. Qualification rests on the property’s income rather than personal income documentation, subject to lender guidelines, which suits LLC-held rentals and portfolios that are scaling. The firm has been recognized as a top-ranked workplace in 2026 and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Rental Manager: Nags Head
2. Zillow Home Values: Nags Head
3. Homes.com — Nags Head NC Houses for Sale
6. Redfin: Nags Head housing market
8. Census Reporter — Nags Head NC
9. Homes.com — The Village at Nags Head Neighborhood
10. Wikipedia — Nags Head Beach Cottages Historic District
11. Census Reporter — Nags Head Township Dare County NC
12. Outer Banks Visitors Bureau
13. Dare County recorded $2.1 billion in visitor spending
14. Outer Banks Health (ECU Health careers)
15. Coastland Times
17. outerbankschamber.com — Jobs Board
18. Scotsman Guide — Top Workplaces 2026
19. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Nags Head, North Carolina: Thin Comps and Tourism Equity · Investment Property Loans in Nags Head, NC: Can the Rent Carry the Loan on a Beach Cottage? · DSCR Cash Out Refinance in Matthews, North Carolina: Pulling Equity from a Thin-Rent Market
Guides: Investment Property Cash-Out Refinance in Nags Head, NC · Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.