
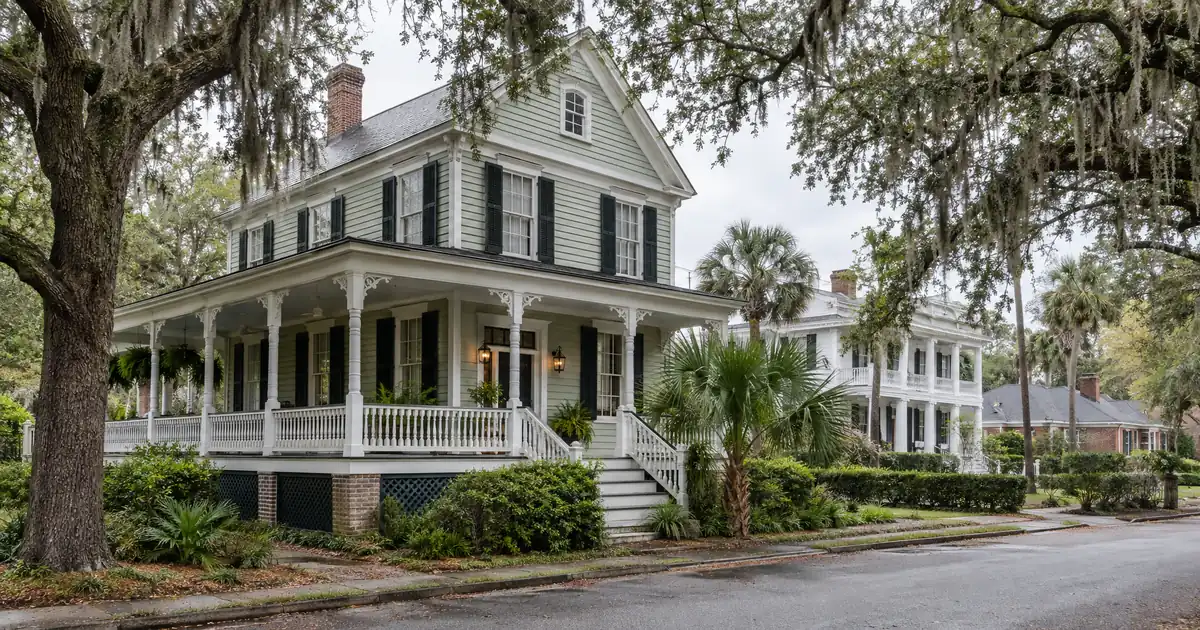
An out-of-state investor scrolling Beaufort listings sees waterfront oaks, a historic downtown, and a city-level home value near $413K. Two things usually get missed. The rent-to-price math on those pretty blocks is thin, and the best coverage ratios sit in the workforce pockets next to three Marine Corps installations. For an investor who already owns here and wants equity out, those two facts decide everything, because a cash-out refinance on a DSCR loan is sized by rent against the full monthly obligation, not by how charming the street looks.
DSCR Cash-Out Calculator
Run the cash-out numbers in Beaufort, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance in Beaufort, South Carolina fits investors who already own workforce single-family rentals near the Marine Corps installations and want to move equity into a next purchase. The file is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds limited by a program-level LTV ceiling and the appraised value.
- Burton-area three-bedroom sales ran about $322,000 to $350,000, per a local brokerage source.
- City-level values rose only about 1.4% over the past year, per Zillow.
- Blended ZIP 29902 rent-to-price math sits near 0.53% monthly, which keeps coverage below 1.0.
- Local military installations employ nearly 20,000 people, per the Beaufort Regional Chamber of Commerce.
Beaufort Market Snapshot
A quick read on the Beaufort investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $2,160 avg (Prop:Metrics, ZIP 29902) |
| Employment | Nearly 20,000 jobs (beaufortchamber.org — Support for Our Military) |
Burton Is Where the Coverage Math Lives
Burton, the entry-level submarket next to Laurel Bay, is the strongest cash-out candidate in the Beaufort market. A local brokerage’s July snapshot shows 3BR sales around $322,000 and 3BR/2BA near $350,000, with 3–4BR homes in the low $400Ks. The same source puts single-family rents between $2,300 and $3,200.
Run the numbers on a $2,300–$2,400 rent against a $322,000–$350,000 house. That is roughly 0.7% a month, Lendmire Research’s own arithmetic rather than a sourced ratio. Modeled at 75% LTV on a 30-year term, with taxes and insurance included in the obligation, coverage lands around 1.10 to 1.20. Those are modeled assumptions, not quotes. The low end sits above the standard 1.00 benchmark, but not by much, so a small insurance or appraisal surprise matters. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The tenant layer holds up this band. At MCAS Beaufort, Garrison Ledger lists the housing allowance for an E-5 with dependents at $2,403 a month, which maps closely onto a $2,300–$2,400 house. Sources disagree on whether the 2026 allowance moved up or slightly down, so underwrite conservatively and check the figure against the DoD table before building a pro forma around it. Don’t underwrite rent above the allowance band of the rank you expect to rent to.
Larger homes also look like the stronger segment. A local property manager reports 4-bedroom demand running high, with owners of smaller units adjusting expectations. That reverses the usual small-units-cash-flow-best pattern. Prop:Metrics’ 4BR median of $2,520 backs the point. The source is a self-interested property manager, so treat it as direction, not proof.
The Blended City Number Hides the Problem
Beaufort’s ZIP-wide numbers put typical coverage below 1.0. Prop:Metrics, drawing on RentCast, shows an average rent of $2,160 against a $409,000 median price in ZIP 29902. That is about 0.53% a month, or roughly 6.3% gross annually (Lendmire Research arithmetic). It sits well below the 1% rule.
At 75% LTV with taxes and insurance included, that blend models near 0.9. Rent also slipped 4.0% year over year in the same dataset, so the trend is soft. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Lady’s Island makes the tension sharper. Redfin shows an average house price of $482K there, up 2.1% year over year, with homes selling in about 57 days. Even the $2,520 4BR median from the ZIP data models around 0.9 at that price. Cash-out there depends on the appraisal more than the rent. Lady’s Island is an equity-hold market, not a coverage market.
This one is a genuine toss-up for some investors. Appreciation-minded owners could argue Lady’s Island’s commute appeal to the air station justifies holding. Investors who need the number to clear 1.00 should look at Burton first.
Skip the Waterfront for Cash-Out Math.
The historic district, Habersham, Distant Island, and Shell Point carry premiums that rents don’t follow. No sourced neighborhood-level rents exist for them, but the direction is clear: expensive stock with ordinary rents produces thin coverage unless the owner has a lot of equity to bring in. Mossy Oaks and the Battery Creek area read as more accessible entry points, though only qualitatively.
A cash-out on premium stock gets squeezed from two sides. The 75% LTV ceiling limits the proceeds, and the rent has to carry the full obligation on whatever balance remains. Owners of waterfront rentals often find the refinance works better as a hold than as an extraction.
What Equity Is Actually Available?
Appreciation credit is thin inside city limits. Zillow’s average value is $413,385, up 1.4%. Data USA’s Census-derived median property value is $345,400, a lagging owner-reported figure. Prop:Metrics’ median is $409,000.
County numbers look better, and they mislead. Redfin reports a Beaufort County median sale price of $608K, up 5.3%. That is skewed upward by Hilton Head, Bluffton, and Fripp. Don’t present it as a city trend.
So a cash-out on a city-limits property should assume little appreciation credit. Available equity depends on original purchase basis and the appraiser’s comps, then gets cut by the 75% LTV ceiling and the reserve requirement. Stabilizing is the right word here. Booming is not. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Why the Tenant Base Doesn’t Track the Housing Cycle
Beaufort’s renters follow Marine Corps staffing, not home prices. The Beaufort Regional Chamber says MCAS Beaufort, MCRD Parris Island, and Naval Hospital Beaufort provide $2.4 billion to the local economy and employ nearly 20,000 people. That is more than the city’s population of about 13.7k. The same Chamber page says Parris Island trains 49 percent of males and 100 percent of females entering the Marine Corps, which keeps a steady rotation of families moving through. Visit Beaufort SC reports 120,000+ guests at Parris Island each year.
On-base housing is the competing supply. A Trulia listing for Laurel Bay housing shows $1,750 for 2BR, $1,775 for 3BR, and $1,800 for 4BR in E1–E5 homes, with basic utilities included. That is a promotional benchmark, not a market median, but off-base landlords price against it.
This is not a college-town thesis. The Technical College of the Lowcountry enrolled 2,349 students per Data USA, too few to move rental demand.
The Plumbing: Seasoning, Rent Schedules, and Lease-Up
The file mechanics matter more than the story in a market this thin. Cash-out on a DSCR loan typically requires about six months of ownership measured from title recording. Leverage generally tops out at 75% of appraised value, and the standard coverage benchmark is 1.00 on rent used for lender review against the full monthly obligation (principal, interest, taxes, insurance, and any dues). Reserves typically run about six months of that obligation. Lenders often price and structure differently for borrowers below the 660–700 credit tiers, and 620 is the floor. Review details are subject to lender overlays, and some lenders review lower coverage with compensating factors, lower leverage, or more cash down.
Working DSCR brokers see a recurring pattern in military-anchored markets like this one: leases signed at peak rents come in above what the appraisal’s market rent schedule supports. When the schedule comes in lower, coverage drops with it, and the shortfall surfaces late in the file. Underwriting on the schedule number from the start prevents rework.
Leasing speed is part of that picture. The same property manager reports average rental days on market across the county stretched to about 99 days, and one portfolio went from 32 days to 79. A vacant unit at refinance time is a documentation problem, since the lender may rely on the appraiser’s rent schedule rather than a lease. As a cross-check, 2026 HUD fair market rents relayed by the local broker put a Beaufort County 3BR at $2,177, below the $2,390 Prop:Metrics median. That is a reasonable floor for stress-testing.
Documentation is the unglamorous part. Expect the lender to request the current lease or rent schedule, proof of title recording date, the insurance declarations page, and entity documents if an LLC holds title, subject to lender program eligibility. Budget for taxes and insurance, and verify current local rules with qualified local professionals.
Where Does the Cash Go Next?
Proceeds are capital for the next deal, and Beaufort’s own math suggests where. Pulling equity from a premium-stock property into a Burton three-bedroom shifts the portfolio toward the submarket with the better rent-to-price ratio. Duplex stacking is less supported: local duplexes exist, and Laurel Bay on-base housing includes duplex-style homes, but no sourced per-unit rents exist, so any multi-unit thesis needs its own sourcing.
Lender-reviewed loan amounts run up to $3,000,000 on standard programs, with smaller balances routed through select lenders. Equity available is not a guaranteed cash figure. Investors who want to see their own file’s math can start a quote or call 828-256-2183.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Beaufort, SC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The investors who underwrite Beaufort’s Marine-driven rents at appraisal value instead of peak-lease value will come out ahead.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Beaufort, South Carolina?
Qualification centers on the property’s rent against its full monthly obligation, typically measured against a 1.00 benchmark, plus a credit score floor of 620 and about six months of reserves. The property usually needs about six months of ownership from title recording. Everything is subject to lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Beaufort, SC?
Typical requirements include a rent schedule from the appraisal, proof of insurance, entity documents for LLC borrowers (subject to lender program eligibility), and reserves. Manufactured homes, log homes, and barndominiums fall outside these DSCR programs. Terms vary by borrower, property, and lender.
Why does Beaufort’s blended coverage run below 1.0?
City-level prices have climbed faster than rents. ZIP 29902 shows roughly 0.53% monthly rent-to-price, and rents there slipped 4.0% year over year per Prop:Metrics. The better coverage clusters in workforce submarkets like Burton, where 3BR rents sit closer to 0.7% of price.
Can a county price trend support my Beaufort cash-out?
No. Redfin’s +5.3% is a county figure, driven by Hilton Head, Bluffton, and Fripp. City-level values rose about 1.4%, so appraisers working city comps may give little appreciation credit.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
A deeper walk-through of investment-property equity extraction lives in cash-out refinance on an investment property.
For broader investor-financing rules and property-type coverage across the state, see South Carolina DSCR loans.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Realestatebeaufortsc.com — Buying OR Renting IN Burton When You
2. Zillow Home Values, Beaufort SC
3. Beaufort Regional Chamber of Commerce, military
6. middleton.rent — Beaufort SC Rental Market Update Spring 2026 Trends Insights
8. Census-derived median property value
9. Redfin, Beaufort County housing market
11. Data USA
12. 2025
13. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Beaufort, North Carolina: The 2026 DSCR Financing Guide to the Historic District · DSCR Loans Beaufort & Port Royal: Investor Financing for MCAS Beaufort, Parris Island, Hunting Island & Real Estate Investors · DSCR Cash Out Refinance in Irmo, South Carolina: Equity Math for Single-Family Rentals
Guides: Investment Property Cash-Out Refinance in Beaufort, SC · Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.