
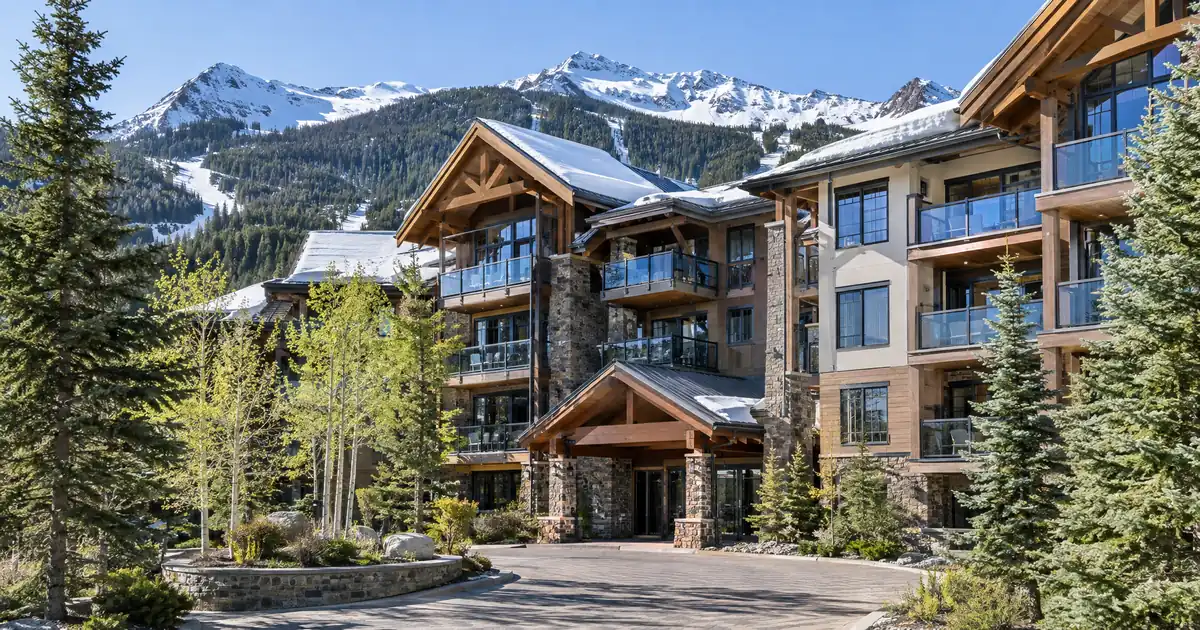
An out-of-state investor scrolling Breckenridge listings sees a ski resort, a preserved gold-rush Main Street and a median sale price near $895K per Redfin. What gets missed is the tenant side. Per High Country News, 68% of Breckenridge’s units are second homes or vacation rentals, and about three-quarters of full-time residences are set aside for the local workforce. The unrestricted long-term rental you own is a scarce product, and pulling equity from it is a paperwork-heavy exercise.
TL;DR: A DSCR cash-out refinance in Breckenridge, Colorado, is underwritten primarily on the property’s rental income measured against its full monthly obligation, which fits investors holding unrestricted condos or townhomes with year-round tenants rather than single-family buyers chasing appreciation.
DSCR Cash-Out Calculator
Run the cash-out numbers in Breckenridge, CO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out is capped at 75% LTV, with about 6 months of seasoning from title recording.
- Zumper puts median rent at $3,703, against a $895K Redfin median sale price.
- Condos and townhomes are the realistic fit; single-family rarely reaches coverage.
- Deed-restricted workforce units generally don’t work as collateral.
- Slow-moving comps can shrink appraised value and the cash-out amount.
Why Coverage Is the Constraint Here
Breckenridge is an appreciation-and-luxury market, not a cash-flow market, and the refinance math reflects it. Zumper reports a median rent of $3,703 across property types, though it flags thin inventory and notes rents moved sharply month to month while slipping about 5% over the year. Against a county condo median of $795,000 reported by High Rockies Homes, that rent implies a gross yield near 5.6% (a modeled calculation, not a sourced figure).
Gross yield isn’t coverage, though. DSCR divides rent used for lender review by full PITIA: principal, interest, taxes, insurance and any HOA dues. Mountain-resort condos often carry meaningful HOA dues, which land directly in the denominator. Modeled on a condo near that $795,000 median at 75% LTV, including taxes and insurance, coverage tends to sit in borderline territory, roughly 0.9x to 1.1x depending on actual rent and dues. Standard programs are built around a 1.00x benchmark, subject to lender guidelines. Some lenders review lower ratios with stronger compensating factors, lower leverage or different pricing.
Single-family is a different story. The Breckenridge single-family median runs $1,941,500 year to date per the same brokerage report, skewed by a small high-end sample of 29 sales. At rents near $3,700, long-term coverage doesn’t get there. Skip it for a long-term-rental refinance.
Where the Cash-Out Math Pencils
Qualitative reads beat invented numbers in a market this thin. Zumper says it lacks enough inventory to publish neighborhood-level rent data, so the submarkets below are described by product type and tenant base.
Town core and Main Street corridor. Dominated by second homes and condos, with tenant demand from hospitality and seasonal staff. Free-market condos here with year-round leases are the cleanest collateral profile.
Peak 8 and Peak 9 base areas. Condo and townhome clusters at the lifts. Buyers here often count on rental income to offset ownership costs, but that is frequently short-term income. A long-term lease schedule is what a DSCR cash-out on these files would be built on.
Blue River and the Highway 9 corridor toward Frisco. More suburban and car-dependent, with a mix of condo and single-family listings under a Breckenridge 80424 ZIP. A townhome here can offer a better price-to-rent relationship than a base-area condo, though rent data is sparse.
Workforce-housing projects (Alta Verde, Vista Verde, Blue 52, Wellington). Generally not typical DSCR collateral because of deed restrictions. Summit Daily describes Alta Verde 1 as an 80-unit complex, and a separate Summit Daily report notes officials worry some town-built workforce units are sitting unoccupied. Confirm any restriction before a file goes anywhere.
The stronger play might be a condo with a second income stream, such as an ADU-style unit, over a single-family home. Honestly, those are rare here, which is the point.
Appreciation Won’t Fund This Deal
Don’t lean on price gains to pull equity. The county condo median is essentially flat year over year, and a brokerage source reports Breckenridge condo average sold prices dipped about 2% in 2025 against roughly 1% growth county-wide. Redfin shows the citywide median down 6.6% year over year, while Summit Colorado Realty reports a higher $1,275,000 median with 3.6 months of supply. Sources disagree because the sales sample is small and skews luxury. This article uses Redfin’s figure as the citywide reference.
The takeaway for equity extraction: size cash-out on flat-to-modest values. Equity comes from purchase basis and paydown, not a rising market. Consider an investor who bought a free-market condo several years ago and holds a lease at current rents. At 75% LTV, the proceeds depend on the appraised value, the rent used for lender review and reserves of about 6 months PITIA (about 9 months above $1,500,000). It is not a guaranteed cash figure. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Seasoning and Comps: The Appraisal Friction
About 6 months of ownership, measured from title recording, is the typical seasoning benchmark. That clock is the easy part. The harder part is the comp set. High Rockies Homes reports an average of 110 days on market for single-family homes and 176 for condos in February, with sellers still getting 96%+ of asking. Slow sales mean few recent, tightly matched comparables.
Appraisers working from thin comps tend to be conservative. Allow for a value haircut when modeling proceeds, and don’t assume the appraisal lands at last year’s list price. The practical mechanics:
- Pull the executed lease and a rent schedule from the appraiser, not a portal estimate.
- Collect HOA dues documentation early; dues move coverage directly.
- Confirm the unit is unrestricted and eligible. Manufactured homes, log homes and barndominiums fall outside these programs.
- Document the reserve account separately from the cash-out proceeds.
Lendmire’s deal desk sees a consistent pattern on files from resort-economy markets like this one. The cleaner files from a documentation standpoint arrive with a signed long-term lease, current HOA statements and a clear ownership timeline. The common friction point is a property with a short-term income history but no long-term lease, which forces a rent-basis conversation at the end of the process instead of the start.
What Tenant Demand Really Looks Like
Demand is real but stretched. Per Summit Daily, county area median income has risen nearly 40% in four years while wages lag, and residents often spend 40-60% of income on housing. High Country News adds that 60% of renters spend more than a third of income on housing. Underwrite current rents. Skip aggressive growth assumptions.
The employment base is hospitality-led. The Town of Breckenridge lists outdoor recreation, real estate and property management, professional services and Vail Resorts as key drivers, and peak-period population swells past 39,000 against 5,078 permanent residents at the 2020 census. St. Anthony Summit Hospital, a Level III trauma center in nearby Frisco, adds a modest healthcare tenant pool.
New supply matters too. More than 400 deed-restricted units have been built since 2022, with about 300 more expected in four years, and some workforce units priced at 100% of area median income sit close to market-rate rents. That works as a mild ceiling on unrestricted rents. Not oversupply, yet.
How the Proceeds Get Used
Capital pulled from a Breckenridge condo rarely stays in Breckenridge. A brokerage source says Frisco, Silverthorne and Dillon offer lower entry prices with comparable county amenities, though no rent data was found for those towns. Investors chasing coverage should compare them. For the mechanics of using refinance proceeds as a down payment elsewhere, see the guide “The Refi Options” and the rate-and-term and cash-out refi details.
Investors can also review what DSCR qualification actually looks like or compare how DSCR stacks up against conventional financing. Loan amounts run up to $3,000,000 on standard programs, with credit tiers starting at a 620 floor, all subject to lender guidelines, credit approval and property review. Titling in an LLC is possible subject to lender program eligibility. Lendmire’s Colorado DSCR loan programs cover the state-level detail, and investors can see what the numbers look like or call 828-256-2183. Investors should also verify current local rental rules, taxes and insurance with qualified local professionals.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Breckenridge, CO, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Breckenridge?
Qualification centers on the property’s rent versus its full PITIA, with 1.00x as the common benchmark, plus a credit score typically 620 or higher and about 6 months of reserves. Lenders review the lease, appraisal rent schedule and HOA dues. Eligibility depends on lender guidelines, credit profile and property review.
What are the requirements for an investment property cash-out refinance in Breckenridge, Colorado?
Expect about 6 months of ownership from title recording, a 75% LTV ceiling, and an eligible unrestricted property. Proceeds depend on appraised value, rent used for lender review and reserves, so the cash figure isn’t guaranteed. Smaller loan balances route through select lenders in the network. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Can a deed-restricted workforce unit be refinanced with a DSCR cash-out?
Generally no. Restrictions limit rents and resale value, which conflicts with typical collateral requirements. Confirm a unit’s status with the seller or HOA before modeling anything.
Why might a Breckenridge appraisal come in low?
Condos averaged 176 days on market in one brokerage report, leaving few recent comparable sales. Thin comps push appraisers conservative, which can shrink the cash-out amount.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Lendmire is a two-time Scotsman Guide Top Mortgage Workplace, recognized as a top-ranked workplace in 2026 and a top-ranked workplace in 2025. Read the full Lendmire news archive.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Breckenridge Housing Market
2. High Country News, Breckenridge Workforce Housing
3. Zumper, Breckenridge Rent Research
4. High Rockies Homes, Market Reports
5. Summit Daily
8. Summit Daily, Affordability
9. Town of Breckenridge, Community Demographics
10. St. Anthony Summit Hospital
11. Scotsman Guide — Top Workplaces 2026
12. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Breckenridge, CO · Investment Property Cash-Out Refinance in Colorado
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.