
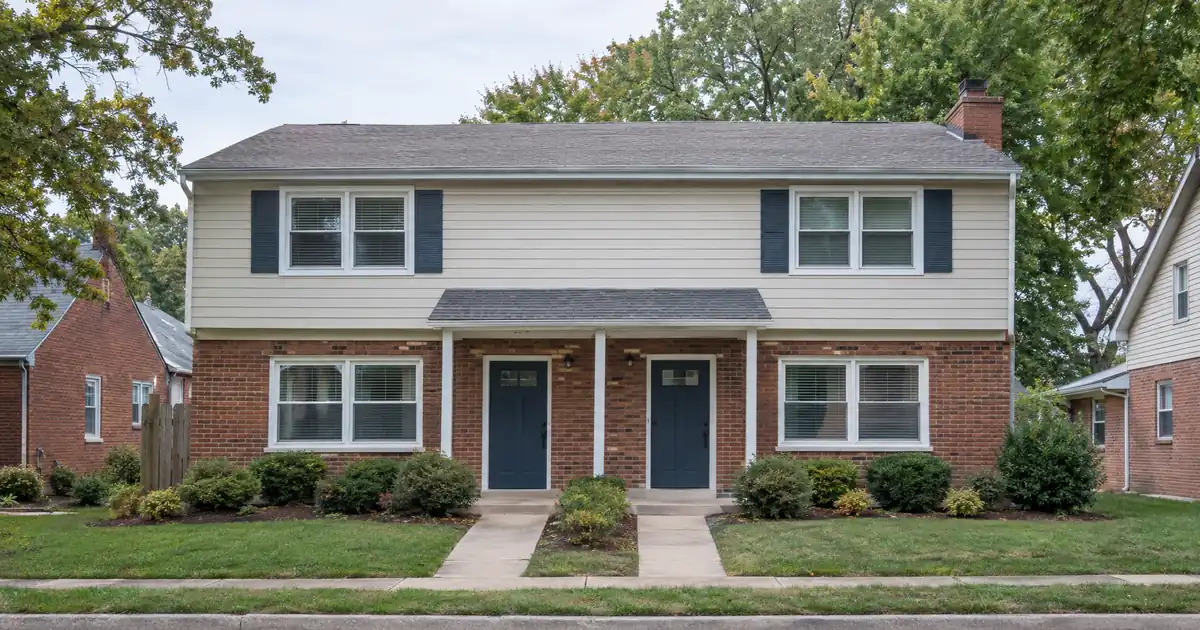
Two Ballwin landlords walk in with the same request. One owns a townhome-style condo in a community like Hickory Sound or Treetop. The other owns a three-bedroom brick ranch in the 63011 ZIP. The math favors the condo on rent-to-value, and the ranch on sheer equity. Those are different things, and confusing them is how cash-out files stall. Lendmire, a DSCR-focused mortgage broker, sees that split constantly in second-ring suburbs like this one.
The Short Version: A DSCR cash-out refinance in Ballwin, Missouri is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the deal works from seasoned ownership and a lease-backed rent figure through appraisal and reserve review, with proceeds capped by the 75 percent LTV ceiling and subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Ballwin, MO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Condo listings near $252,500 beat 63011 house pricing near $450,000 on rent-to-value, per Ryan Patton Group.
- Gross rent-to-value runs near 0.43 percent on ACS medians.
- Coverage, not the 75 percent cap, usually sets the proceeds here.
- Seasoning is about six months from title recording.
Condos First, Ranches Second
Townhome and condo rentals are where Ballwin’s rent-to-value runs best, because the purchase price is low against rents that sit close to house rents. Ryan Patton Group, one agent’s summary, puts condo-neighborhood median listings around $252,500. The same source shows ZIP medians near $377,450 in 63021 and $450,000 in 63011.
Don’t get too excited, though. HOA dues sit in the PITIA denominator, and in a condo community they can eat the advantage. Run the file with the actual dues, not a guess.
Ranches and workforce single-family are the dominant product. Ballwin is about 80 percent detached homes, and most of the stock dates to the sixties and seventies. That matters on a cash-out because the appraiser will look at condition, and a dated kitchen or roof can trim value before coverage even enters the conversation.
The market itself is low-density and owner-heavy. RentCafe counts 1,914 renter households against 10,165 owner households, roughly 16 percent renters. That’s a shallow rental pool. Tenants are there, but you won’t find a duplex block to stack income on.
A Modeled Ranch Refi
Run the numbers on a hypothetical 3BR ranch in 63021 appraising near the $377,450 ZIP median, with a modeled rent of $2,000 a month. These are assumptions, not sourced market figures. Coverage here means rent divided by full PITIA, taxes and insurance included.
At 75 percent LTV, coverage lands in the mid-0.80s. Sub-1.00 is the standard 1.00 benchmark’s weak side. Dropping leverage into the 60 percent range pulls the ratio to roughly the 1.00 baseline.
Sub-1.00 files aren’t dead, but they get harder. A lender may review a sub-1.00 program, reduced leverage, or an interest-only structure, all subject to lender guidelines, credit approval, and property review. The trade is usually lower proceeds or stronger credit and reserves.
Seasoning is about six months from title recording, reserves run about six months of PITIA, and credit tiers start at a 620 floor. Treat all of those as typical guidance rather than promises. The guide “What Is a DSCR Loan” covers how the ratio works.
Here’s the pattern worth absorbing. Working DSCR brokers see a recurring pattern in high-income, owner-occupied suburbs: the borrower anchors on appraised value and assumes the LTV cap sets the check. In a thin-yield market the coverage ratio sets it, and leverage gets dialed back until the ratio clears. The cleanest files show up with complete leases, entity docs, title, and property details ready for lender review.
Don’t Underwrite Off Apartment Rents
Apartment comps flatter Ballwin. RentCafe shows an average of $1,470 across larger buildings, with three-bedroom units at $2,080. Its data covers only 50-plus-unit buildings. Apartments.com shows a lower average of $1,246, and ACS puts average renter-paid rent at $1,493.
That spread is the point. Quote a range, name the source, and don’t assume your ranch rents like a garden-style unit. Zumper has Ballwin house rents flat year over year, per its Ballwin listings page. Asking rents at named communities like Retreat at Seven Trails (two-bedrooms from $1,245) and Forest Lake Apartments (from $1,218) are useful ceilings, per Apartments.com.
Values are not running away either. Zillow puts the average home value at $417,520, up 2.1 percent over the past year. Movoto reports a lower median sold price of $375,000, a different method, and says days on market roughly doubled. Against the Zillow figure, the gross rent-to-value ratio (derived, using ACS rent) is closer to 0.36 percent. Don’t underwrite aggressive appreciation. Skip it.
Where the Proceeds Go (Hint: Not Ballwin)
Ballwin itself has no sourced duplex, triplex, or fourplex inventory, and nothing on ADUs. An investor who wants multi-unit income stacking has to look elsewhere. A local investor blog, treat it as directional, says four-unit buildings in South County and South City can still be bought for roughly $350,000 to $550,000, with units renting around $900 to $1,200. It names Fenton, Affton, Lemay, and parts of Webster Groves and Crestwood as the better southern submarkets.
That’s the equity-extraction loop. A low-leverage cash-out on a Ballwin single-family rental becomes the down payment on a higher-yield building in the southern county. The cash-out cuts Ballwin’s coverage thinness down to size, and the next asset supplies the rent-to-value the first one lacks. One caution: the blog’s figures come from an owner-occupant house-hack view. A non-owner-occupied DSCR file carries higher PITIA, so pressure-test each building before you count on the cash.
Investors weighing this should read pulling equity with a DSCR cash-out before picking a structure. Entity-owned properties are common, subject to lender program eligibility.
Who Rents Here, and Why They Stay
Ballwin is a bedroom suburb roughly 20 miles southwest of downtown St. Louis, with a median household income near $124,626 per Point2Homes. The jobs base is regional: healthcare, aerospace, education, and corporate offices. St. Louis Magazine, drawing on an older Regional Chamber ranking, lists BJC HealthCare at 28,351 employees, Boeing at 14,000, and Mercy at 14,195.
Nothing sourced shows how many of those workers live in Ballwin. The plausible anchors are nearby hospitals. Missouri Baptist Medical Center is a 489-bed acute care hospital near I-270 and I-64, and Mercy Hospital St. Louis is the county’s only Level 1 trauma center. Maryville University, in west county, reports over 9,000 students in total per its own release. Treat student demand as a small tenant pool, not a thesis.
Metro data helps the hold case. Colliers reports effective multifamily rents rising from $1,330 to $1,398 over roughly five quarters, with suburban occupancy stabilized while the urban core is mixed. Northmarq expects vacancy to improve modestly as new deliveries fall, and expects Mid County to see heavy transaction activity, which helps with comparable sales next door. Ballwin’s own vacancy rate wasn’t found, so don’t cite one.
Can a Thin-Yield Suburb Still Support a Cash-Out?
Yes, but the honest answer is: at lower leverage than you hoped. Northmarq expects metro multifamily cap rates to hold in a 5.0 to 7.0 percent range. Ballwin single-family sits at the thin end of any such yield picture, so coverage, not the 75 percent LTV ceiling, is the binding constraint. Equity available is never a guaranteed figure.
The appraisal side is steadier than the yield side. A regional inventory blog citing MARIS data says metro active inventory rose about 15 percent and months of supply moved from 2.2 to 2.8. That’s a cooling trend, not a cliff. Verify against St. Louis REALTORS® data, and confirm current local rules, taxes, and insurance with qualified local professionals. Missouri DSCR financing details the statewide program picture, and the guide “Where DSCR and Conventional Diverge” explains why investors use it for entity-held rentals. Investors can also reach Lendmire at 828-256-2183.
So which sounds more like your file: a ranch that clears 1.00 only at lower leverage, or a condo where HOA dues decide the whole ratio?
Frequently Asked Questions
How do you qualify for a DSCR loan in Ballwin?
Qualification rests mainly on the property’s rent against its full PITIA, with a typical 1.00 benchmark, plus credit (a 620 floor, with better tiers at 660, 680, and 700) and reserves around six months. Lenders also review title, leases, and appraisal. Ballwin’s thin rent-to-value means many files clear only at reduced leverage, subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Ballwin, MO. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Ballwin, Missouri?
Expect a cash-out refinance to need about six months of ownership from title recording, leverage capped at 75 percent LTV, and a documented rent figure. Eligible property types include single-family, condos, and townhomes. Manufactured homes, log homes, and barndominiums fall outside these programs. Exact terms vary by lender, property, and borrower.
Do Ballwin’s older homes complicate a cash-out appraisal?
Older homes can complicate an appraisal. Most of the stock dates to the sixties and seventies, so condition and updates drive appraised value, which in turn drives proceeds. A recent roof, HVAC, or kitchen refresh tends to support value better than deferred maintenance does. Appraisers also lean on recent sales, and metro investor activity in neighboring areas helps.
Is a duplex or fourplex refinance realistic inside Ballwin?
Not really, since no reliable duplex, triplex, or fourplex inventory was found inside city limits. Investors seeking multi-unit coverage typically look at nearby southern and inner-ring submarkets. Ballwin works better for single-family and condo holds, with the refi proceeds pointed elsewhere.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage specializing in DSCR investor loans, arranging financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. Its model centers on rental income at the property level, reviewed by the lender instead of W-2 documentation and subject to lender guidelines, which suits entity-owned and multi-property investors. The firm was named a 2025 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Zip-codes.com (ACS data, Ballwin)
7. Zillow Home Values, Ballwin
8. Fenton, Affton, Lemay, and parts of Webster Groves and Crestwood
9. Point2Homes
11. West St. Louis County Chamber, Hospitals
12. maryville.edu — Maryville University Welcomes Largest Freshman Class in History Again
13. Colliers St. Louis Multifamily Report
14. Northmarq, St. Louis multifamily sales activity
15. a 2025 Scotsman Guide Top Mortgage Workplace
16. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Missouri
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.