
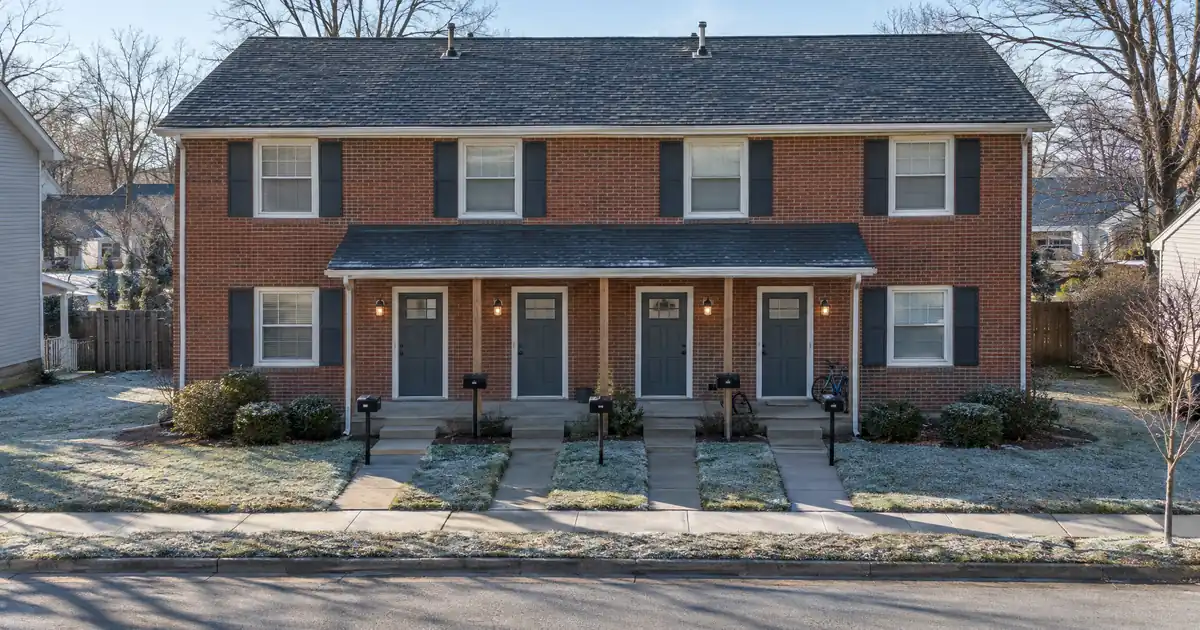
The Quick Read: You finance a duplex, triplex, or fourplex run as an Airbnb with a DSCR loan, which qualifies primarily on the property’s rental income covering the full monthly payment, subject to lender guidelines. No separate “Airbnb loan” product exists. The loan is a standard investor loan, and the lender decides which income source it will count.
- Short-term rental purchases typically reach up to 75% LTV (loan-to-value, the loan as a share of the property’s value) on the strongest files.
- Short-term rental refinances and cash-outs typically top out near 70% LTV.
- Expect a 640+ credit score and about 12 months of hosting history on most files.
- Coverage on both purchases and refinances is typically measured against a 1.00 floor.
- Local rules and the lender’s chosen income source can decide the deal before the math does.
Most of this article is about the income source. Pick the wrong one and a strong building looks weak on paper.
Short-Term Rental Calculator
Run the STR numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your nightly rate, occupancy, taxes, and insurance for a more accurate picture.
Short-term rental income is documented with a 12-month history or a market data report. Program parameters update from Lendmire’s centralized guideline source.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Nightly rate, occupancy, taxes, and insurance are editable estimates. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
What Is a Short-Term Rental Loan on a 2-4 Unit?
DSCR stands for debt service coverage ratio. It compares the property’s rent to its monthly obligation. Your W-2s and traditional personal-income documentation is not the test. The building is.
Duplexes, triplexes, and fourplexes count as residential property. LoopNet’s commercial real estate primer puts 2-4 units in the residential category and treats five or more units as commercial. That matters. A fourplex stays in the investor-loan channel that most DSCR programs serve. A five-unit building does not.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. If you plan to live in one unit, the usual answer is a different loan type. The DSCR path fits the investor who owns a primary home elsewhere.
Across the wholesale network Lendmire works with, standard programs cover loan sizes up to $3,000,000. Select lenders handle smaller balances. Qualification is always subject to lender guidelines, credit approval, and property review.
How Does Underwriting Treat a 2-4 Unit Airbnb, Step by Step?
Underwriting runs in five steps: choose the income source, document it, appraise the building, compute the ratio, then check eligibility. The ratio is monthly rental income divided by monthly PITIA. PITIA means principal, interest, taxes, insurance, and any HOA dues. On a multi-unit building, income from every unit is added together.
Step 1: Choose the income source. This is the biggest decision on the file. Three paths exist, and a given program accepts some of them, not all.
- Trailing history. Twelve months of Airbnb or Vrbo payout statements, a property manager’s report, or booking-system data. This is the strongest evidence, and it is why most programs want about 12 months of hosting experience.
- A third-party projection. Used for purchases and conversions with no history. The common tool is AirDNA’s Rentalizer.
- The appraiser’s long-term market rent. Some programs count only this, even if you run the building nightly.
Step 2: Understand what a projection actually is. AirDNA’s help center explains that Rentalizer searches for comparable listings within 10 miles. It matches them on bedroom, bathroom, and guest count, then builds a weighted-average estimate. That is a model of one listing. A building with several small units can be hard to match against single-listing data. One review of the tool calls it directional rather than exact, most reliable in data-rich markets.
The projected figure is also gross host revenue. IGMS’s explainer notes that Rentalizer estimates gross revenue, including cleaning fees. Gross is not net. Programs that accept a projection typically apply a haircut before using it.
Step 3: The appraisal. The appraisal sets value, which sets LTV. It also sets a rent schedule, which sets coverage. For 2-4 unit properties, appraisers use Form 1025, the small residential income property report. Fannie Mae’s Selling Guide lists that form for 2-4 unit properties. Single-family rentals use Form 1007 instead. This is a form-name reference only. Agency rules do not govern DSCR loans.
No dedicated short-term rental appraisal form exists. Nightly income usually enters through a supplemental income analysis or addendum, because the forms are built around monthly leases.
Step 4: Compute the ratio. Take the income the program accepts, after any haircut. Divide by PITIA. Coverage of 1.00 means the income exactly matches the payment. Above 1.00 means a cushion. Stronger ratios typically open better pricing and leverage.
Step 5: Check eligibility. Credit, reserves, seasoning, property type, and legal use all still apply. Rent covering the payment does not equal approval.
What Do the Numbers Look Like on a Duplex Versus a Fourplex?
Take two modeled buildings, with the inputs labeled as assumptions and not market data. Both are purchases at 75% LTV. Each unit is assumed to earn the same income as its neighbors. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Duplex, strong history. Twelve months of statements show steady bookings in both units. The lender counts documented income with its haircut. Coverage lands near 1.25x. That clears a 1.00 floor with room to spare.
Fourplex, no history. You are converting a long-term fourplex and have never hosted. The program accepts a projection, but the lender applies a larger haircut and wants the building’s appraisal rent schedule to agree with it. Coverage lands near 1.05x. It clears, but barely.
The same fourplex, long-term rent only. Run on the appraiser’s market rent alone, it comes in around 0.95x. That is below 1.00. A different path applies here. One option is a select-lender sub-1.00 program, with leverage and terms adjusted. Another is waiting until you have 12 months of hosting history. A third is interest-only structuring, which some select lenders offer. Whether any of these work depends on lender review.
Notice the lesson. The same building produced three ratios. The income source, not the building, moved the number.
A cautionary note on what coverage means. DSCR compares rent to PITIA only. Clearing 1.00 is not the same as positive cash flow. Repairs, vacancy, management fees, utilities, cleaning, and capital expenses all sit outside the calculation. A nightly fourplex has more of each than a long-term one. Stress-test your deal. If it clears 1.20 on paper, see whether it still works at 1.10.
How Do 2, 3, and 4 Units Differ?
More units means more income streams, more variables, and more for the appraiser and lender to reconcile. The loan structure stays the same. The scrutiny does not.
| Factor | Duplex | Triplex or Fourplex |
|---|---|---|
| Income roll-up | Two units summed | Three or four summed |
| Appraisal | Form 1025 | Form 1025 |
| Comp matching | Easier | Harder per-unit |
| Typical scrutiny | Moderate | Higher |
| Reserves | Per program | Per program, often more |
Reserves vary by lender, leverage, loan size, and transaction type. They commonly run around 6 months of PITIA. Some conservative refinances at modest leverage under $1,500,000 can see reserves waived. Loans above that size typically step up to about 9 months. Short-term rental files often lean toward the heavier end.
Multi-unit buildings carry operational trade-offs too. One roof, shared utilities, and a single cleaning crew help margins. Guests also hear neighbors through shared walls, and one unit’s problem can spill into the others.
Where Does the General Rule Break?
Four edge cases cause most surprises, and each can undo a deal that looked fine on paper.
Programs disagree on whether Airbnb income counts at all. Some count only long-term market rent. Others count documented booking income, adjusted down. Ask which applies before you fall in love with a building. Across the network, you will see both.
No operating history. Standard DSCR often leans on long-term market rents if you have never hosted. The appraiser’s rent and the AirDNA figure can sit far apart. A projection-based path exists, but it requires lender acceptance of the data.
Seasonality. Twelve consecutive months show the real pattern. Annualizing a peak-season snapshot overstates income, and lenders know it.
Mixed use and legal unit count. If you live in one unit, or only some units are nightly rentals, eligibility and occupancy treatment can change. Owner-occupied house-hacking generally points to other loan types. Also confirm the advertised unit count matches public records and the appraisal. An unpermitted unit can create a financing problem even if it earns money.
Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. Do this before going under contract. A legal problem is not something a loan can solve.
From the broker’s chair, the most common pattern on these files is a gap between the income the investor expects and the income the program counts. The files that go smoothly usually settle the income path first, then hunt for the building. The files that stall usually did it in reverse.
What Leverage, Credit, and Reserves Should You Expect?
For short-term rentals, the network typically offers up to 75% LTV on purchases, about 70% on refinances and cash-outs, and a 640 minimum credit score. Coverage is measured against a 1.00 floor on both purchases and refinances. About 12 months of hosting experience is usually expected.
Contrast that with standard long-term rentals. Most files there land at 75%-80% LTV on a purchase, and cash-out refinances top out around 75% LTV. Short-term rental collateral gets a lower ceiling, since nightly income is less predictable. A 70% cash-out ceiling applies to short-term rental collateral, while 75% applies to standard rentals.
A larger down payment lowers the monthly payment and can lift the ratio. It never erases leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear two tests: enough equity and enough rental coverage.
Not every property qualifies. Manufactured homes, log homes, and barndominiums are not offered in the network’s DSCR programs. If you hold title in an LLC, that is generally workable, subject to program terms.
Term structures start with the 30-year fixed. Extended terms and interest-only periods are available through select lenders, and ARM structures exist for investors who want them. For a fuller walkthrough of the product family, see Lendmire’s complete DSCR loans guide.
What Documents Will You Need?
Expect to gather the following, though each lender’s list differs.
- Platform earnings exports, property manager statements, or booking-system data
- Bank statements showing payouts
- A projection report for new purchases
- The appraisal, including any income addendum
- Proof the property is permitted for short-term use, plus HOA confirmation where one exists
- Entity documents if an LLC holds title
- Insurance that covers short-term rental use
Notice what is missing: personal income paperwork. The qualification runs on the property’s income. Property documentation goes up, though, so the file is not light.
Common Misconceptions
“The lender will count my Airbnb income.” Not always. Some programs use only long-term market rent.
“The projection is my qualifying income.” Programs typically haircut it, and it is gross revenue.
“A 2-4 unit is commercial.” At that size it is residential. Commercial treatment starts at five units.
“Rent covers the payment, so I’m approved.” Legal use, credit, reserves, and the appraisal all still apply.
“DSCR is cheaper than conventional.” It is a flexibility trade, not a bargain. Conventional is reviewed on your personal income, and it can be harder to use for nightly rentals because lenders often discount expected short-term income.
Want to go deeper on mechanics? Lendmire’s article Does a Short-Term Rental on a 2-4 Unit Qualify for a HELOC? covers a different product entirely.
Key Terms Defined
DSCR (debt service coverage ratio): Monthly rental income divided by the monthly PITIA, showing how well the property covers its own payment.
PITIA: Principal, interest, taxes, insurance, and HOA dues, the full monthly obligation on the property.
LTV (loan-to-value): The loan amount as a percentage of the property’s appraised value.
Seasoning: The waiting period a lender wants between two events, such as buying a property and refinancing it.
Haircut: The percentage a lender subtracts from projected or documented short-term income before using it.
Form 1025: The appraisal report for 2-4 unit income properties.
Reserves: Liquid funds, measured in months of PITIA, that a borrower holds after closing.
What Should You Do Next?
Work in this order: confirm local rules, pick the income path, estimate coverage, then shop buildings. Reverse that order and you risk finding the problem after you have paid for an appraisal.
Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Reach the team at 828-256-2183 or request a quote through the site. Lendmire is a broker arranging financing through select lenders in its wholesale network across 41 markets, including Washington, D.C., and nothing here is a commitment to lend.
Frequently Asked Questions
Can I finance a fourplex as an Airbnb?
Yes, subject to lender guidelines. A fourplex is residential, so it fits the investor-loan channel. Qualification rests primarily on whether the accepted rental income covers the payment, along with credit, reserves, and legal short-term use.
Do I need rental history?
Often, yes. Most short-term rental programs expect about 12 months of hosting experience. Without history, some programs accept a third-party projection with a haircut, while others fall back on the appraiser’s long-term market rent.
Can I live in one unit and rent the others nightly?
Usually not with a DSCR loan. These loans are built for non-owner-occupied investment property. Owner-occupied house-hacking generally points to other loan types, and your goals should drive that choice.
What if my coverage is below 1.00?
A path may exist. Sub-1.00 coverage is available through select lenders in the network, with leverage and terms adjusted. Other options include building hosting history first or restructuring the loan. Each depends on lender review.
Does clearing 1.00 mean the property cash flows?
No. The ratio compares rent to PITIA only. Repairs, vacancy, management, utilities, cleaning, and capital expenses sit outside it, so run your own operating budget too.
Investors focused on short-term rentals can review DSCR loans for Airbnb and short-term rentals.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. LoopNet’s commercial real estate primer
2. AirDNA Help Center: Rentalizer Revenue Calculator
3. RentalRecon: AirDNA Rentalizer Accuracy
4. IGMS: AirDNA Rentalizer Guide
This article is part of Lendmire’s short-term rental loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How a Short-Term Rental Loan Works on a 2-4 Unit Property · How Converting a Long-Term Rental to an Airbnb Affects Your Loan · How Much Cash Can You Pull From a Short-Term Rental?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.