
The Quick Read: A DSCR loan suits a fourplex investor whose file rests on the building’s rent, while a local bank suits an investor with strong personal financials and a real banker relationship. The two products use the same acronym but run different math, so the same building can produce two different ratios.
- A DSCR loan is reviewed primarily on property-level rental income covering the payment, subject to lender guidelines.
- A bank reviews the building’s net operating income and also the borrower and guarantor, under its own written policy.
- A fourplex is 1-4 unit residential. A bank may still choose to underwrite it as commercial.
- Typical DSCR purchase leverage runs 75%-80% LTV on an investment property, with a 1.00 coverage floor on select programs.
- Clearing 1.00 is not the same as positive cash flow.
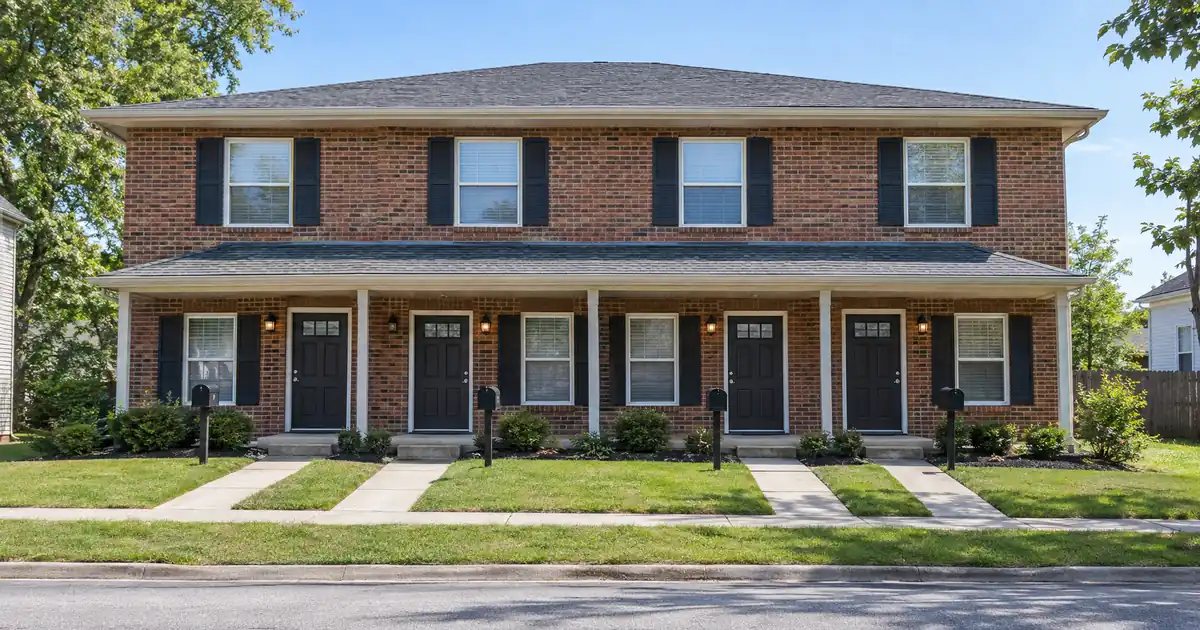
A fourplex sits on the line between residential and commercial lending. That is why this choice is harder than it looks. Neither option is wrong. They answer different questions about the same building.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Side-by-Side
The DSCR column reflects the parameters Lendmire’s wholesale network places. The bank column shows published industry norms, which vary by institution. Lendmire’s network can place either kind of file, so this is a comparison, not a pitch.
| Factor | DSCR Loan | Local Bank Commercial Loan |
|---|---|---|
| Review basis | Property rent vs. PITIA | Property NOI plus borrower and guarantor |
| Personal income docs | Generally not the basis | Typically requested |
| Property types | Non-owner-occupied 1-4 units | Policy-driven, residential or commercial |
| Entity vesting | Common, per program terms | Common, per bank policy |
| Term structure | 30-year fixed is the spine | Often shorter term, longer amortization |
| Maturity event | Fully amortizing structures available | Balloon is common in commercial structures |
| Reserves | Commonly about 6 months PITIA | Set by bank policy and guarantor liquidity |
| Credit | 620 floor in parts of the network; most want 660 | Bank-defined |
| Relationship | None needed | Often a factor |
| Timeline | Standardized review | Committee-driven, varies |
What Each Lender Actually Measures
The word “DSCR” hides the biggest difference. A residential DSCR loan divides monthly rent by PITIA: principal, interest, taxes, insurance, and any HOA dues. A ratio of 1.00 means rent equals the payment.
A bank divides net operating income by debt service. NOI is income after operating costs and before debt service. The OCC’s Comptroller’s Handbook on commercial real estate lending describes banks looking at property cash flow and also at borrower and guarantor cash flow. It lists assets, global cash flow, and contingent liabilities as items to review. It also expects each bank to set its own limits on LTV, loan tenor, and minimum coverage by program or property type.
So there is no single national bank product. A local bank’s guidelines are its own.
Here is the practical effect. DSCR counts gross rent against one payment and ignores vacancy, repairs, management, and capex. A bank’s NOI strips operating costs out first. Same four units, two different numbers.
How a Fourplex Gets Classified
A fourplex is residential by unit count. Commercial treatment usually starts at five units. A bank, though, can run a fourplex through a residential portfolio loan, a commercial real estate loan, or a relationship loan. The label depends on the bank, not only on the building.
Ask the banker one question early: which box does this loan go in? The answer drives documentation, covenants, term structure, and whether a balloon appears.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. That is also why an owner-occupied fourplex, where the investor lives in one unit, is a different track. House-hacking usually points to a bank or owner-occupied product, not DSCR.
When a DSCR Loan Is the Better Fit
A DSCR loan wins when the building carries the file and the borrower’s tax return does not.
Thin or complicated personal income. Self-employed investors with heavy write-offs often show low taxable income on paper. Property-rent-based lender review sidesteps that. Qualification still rests on credit, assets, entity documents, and an appraisal.
Portfolio builders. A DSCR loan reviews the one property. It is not tied to the borrower’s total debt load. A bank may evaluate coverage across every holding, which is the global cash flow idea in the OCC handbook. Local banks also tend to cross-collateralize. That is a pattern, not a published rule.
Long, steady holds. Across the network, the 30-year fixed is the spine of the product. Extended terms of 40 years and interest-only periods are available through select lenders, and ARM structures exist for investors who want them. A fully amortizing structure leaves no maturity event.
Buying inside an LLC. Entity vesting is common on DSCR files, subject to program terms.
Four rented units. Rent from all four units sits in the numerator against one payment. That bigger numerator often makes multi-unit coverage look stronger than on a single-family house. Rent is established through an appraisal. For context, the appraisal for a 2-4 unit property typically uses the form described in Fannie Mae’s Selling Guide. DSCR loans are not agency loans, so that guide is a reference point only and does not set the terms of a DSCR program.
Typical network parameters on investment fourplexes: purchases usually land at 75%-80% LTV, so 20%-25% down. Select high-leverage programs reach 85% LTV with roughly a 700+ score. Cash-out on a standard rental tops out around 75% LTV, with about 6 months of seasoning as the common expectation. Loans run up to $3,000,000 on standard programs (smaller balances available through select lenders). Reserves are commonly around 6 months of PITIA and step up to about 9 months above $1,500,000. Conservative rate-term files at modest leverage under $1,500,000 can see reserves waived. All of this is subject to lender guidelines, and none of it is a commitment to lend.
Coverage matters here. 1.00 is where select programs start. Stronger ratios open better leverage and terms. A separate select-lender path takes coverage below 1.00, with leverage and terms adjusted.
When a Local Bank Commercial Loan Is the Better Fit
A bank wins when the borrower is the strongest part of the file.
Strong financials and a banker who knows you. A real deposit relationship can influence how a loan officer frames the file, how policy exceptions get argued, and how the bank treats a package of loans. It cannot erase policy limits.
Mixed-use or atypical buildings. A fourplex with a ground-floor commercial space may fall outside a residential investor program. A bank can underwrite the whole building on its own terms. Property types such as manufactured homes, log homes, and barndominiums are not offered through the network’s DSCR programs, so those borrowers look to a bank or other lenders.
Owner-occupied fourplexes. If you will live in one unit, the occupancy rule decides the product, and a bank or owner-occupied loan is the more natural track.
Customized structure. A bank can write covenants, a guarantee, cross-collateral, and a term to fit a relationship. That flexibility cuts both ways.
Borrowers with strong income and few properties. If traditional personal-income documentation shows the income and the bank wants the full picture, the heavier file is less of a burden.
The tradeoff is paperwork. A bank file typically carries personal and business financials, operating statements, and guarantor documents. Portfolio loans, to speak generically, are loans a lender keeps in-house under its own criteria, usually backed by traditional personal-income documentation, bank statements, and asset verification.
The Balloon Question
Commercial structures often separate the loan term from the amortization period. Adventures in CRE defines a balloon as the balance still owed at maturity when the loan has not fully amortized, using a 10-year loan amortized over 30 years as its example. CommercialCafe notes the borrower then refinances, sells, or repays at maturity.
That is a planning problem. If values or lending conditions shift at maturity, the exit gets harder. A fully amortizing DSCR structure avoids that event, though it comes with its own limits on leverage and credit.
Some investors use both. A bank loan to buy and stabilize, then a DSCR refinance once the building is leased up. Others go the other way. Either works if the exit is planned before the first closing.
Coverage Is Not Cash Flow
Clearing 1.00 on a DSCR loan means rent covers PITIA. That’s all. Vacancy, repairs, management, utilities, and capex sit outside the calculation. A fourplex with four units leased at 1.20x can still lose money in a bad turnover year.
A bank’s NOI test is closer to a true operating picture because it subtracts expenses first. That is one reason bank math can look tighter on the same building. Stress your own numbers either way.
A larger down payment lowers the payment and can lift the ratio. It does not erase leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear both tests: enough equity and enough rental coverage.
Common Mistakes on Fourplex Files
- Assuming both products calculate the ratio the same way.
- Assuming “commercial” means better terms.
- Assuming an investment property is automatically a business-purpose loan. Purpose, occupancy, and unit count decide it, as the CFPB’s Regulation Z § 1026.3 lays out.
- Skipping the balloon exit plan.
- Treating a passing ratio as profit.
- Assuming a bank will lend on the whole portfolio once it lends on one building.
For a related tradeoff, see Lendmire’s piece Bank Statement Loan vs Portfolio Loan From a Local Bank. For larger buildings, Lendmire also compares DSCR multifamily terms against commercial bank terms on 5 to 10 unit properties.
Which Profile Fits Which Path
| Investor profile | Likely fit |
|---|---|
| Self-employed, heavy write-offs | DSCR |
| W-2 with strong banker relationship | Bank, worth a quote |
| Building a multi-property portfolio | DSCR |
| Buying in an LLC | DSCR, per program terms |
| House-hacker living in one unit | Bank or owner-occupied loan |
| Fourplex with commercial space | Bank |
Run both quotes if the profile straddles two rows. The comparison costs little, and the structural differences show up in the documents each side requests. Lendmire’s complete DSCR loans guide covers the full program mechanics.
Key Terms Defined
PITIA: Principal, interest, taxes, insurance, and any HOA dues on one property.
NOI: Net operating income, meaning income after operating costs and before debt service.
Balloon payment: The balance due at maturity when a loan has not fully amortized.
Recourse: A structure where the borrower or guarantor is personally liable beyond the collateral.
Global cash flow: A bank’s view of the borrower’s combined income and obligations across all holdings.
Amortization period: The schedule used to calculate payments, which can differ from the loan term.
Verdict
Pick DSCR when the building is stronger than your tax return and you want a long, fully amortizing structure with entity flexibility. Pick the bank when you are stronger than the building, own a mixed-use asset, or want a relationship that can flex around policy. Neither wins on every file.
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Tax treatment varies; consult a qualified professional.
Frequently Asked Questions
Is a fourplex considered commercial?
No, not by unit count. A fourplex is 1-4 unit residential, and commercial treatment usually starts at five units. A bank may still choose to underwrite it commercially, so ask which category it will use.
Do I need a deposit relationship for a DSCR loan?
No. DSCR files qualify primarily on property-level rental income covering the payment, subject to lender guidelines. A relationship can matter at a local bank, but a DSCR file still needs credit, assets, entity documents, and an appraisal.
What happens if coverage is below 1.00?
Select lenders in the network offer a path below 1.00, with leverage and terms adjusted. Many select programs start at 1.00, so a sub-1.00 file is a different path, not a moving floor.
Can I use an LLC with either option?
Generally yes on both sides. Entity vesting on DSCR files is common, subject to program terms. Banks also lend to entities, though they often add guarantees.
Does a passing ratio mean the fourplex makes money?
No. DSCR compares rent to PITIA only. Vacancy, repairs, management, utilities, and capex fall outside it.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender around the property’s rental income rather than personal income documentation, subject to lender guidelines. That works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. OCC Comptroller’s Handbook, Commercial Real Estate Lending
2. Fannie Mae Selling Guide B4-1.2-01
3. Adventures in CRE, Balloon Payment
4. CommercialCafe, Amortization in Commercial Real Estate
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Convert a Fourplex to Condos and Refinance Each on DSCR · 2-4 Unit Airbnb Building vs Five-Plus-Unit Building for a DSCR Loan · Can a Suburban Airbnb Qualify for a DSCR Loan Without Vacation Comps?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.