
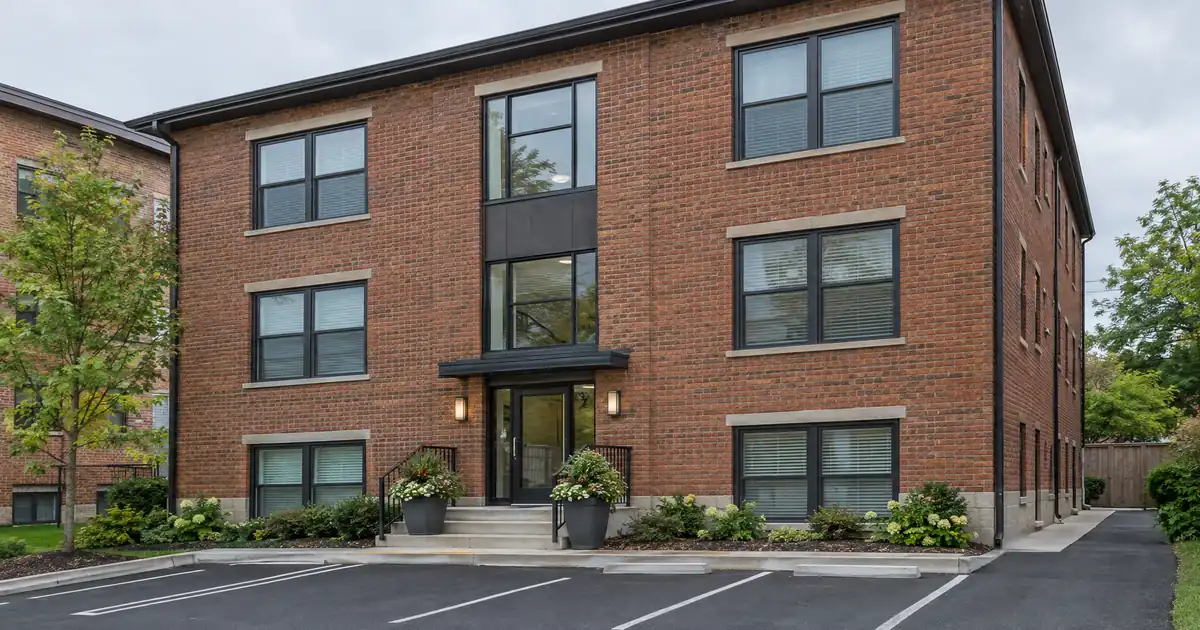
The Quick Read: A six-unit converted motel can be financed with a DSCR loan when the building is legally residential, leased, and past rehab, but it sits in the commercial multifamily category, so the standard one-to-four unit product usually does not apply and select programs with separate appraisal and documentation rules take over. The deal turns on three things: legal use, in-place rent, and how much equity the investor brings. Qualification runs primarily on property-level rental income covering the payment, subject to lender guidelines.
- Six units is one past the residential line, so expect commercial-style underwriting and a commercial-style appraisal.
- The paperwork that decides the file is a certificate of occupancy, permits, and proof of residential zoning, plus a rent roll and leases.
- DSCR money generally fits a stabilized, leased building. An unfinished conversion usually needs short-term money first.
- Typical purchase leverage across the network runs 75%-80% LTV, and reserves run about 6 months of PITIA, subject to lender guidelines.
Why Does a Six-Unit Building Change the Category?
Five units is the line between residential and commercial lending. Six units lands on the commercial side, and that changes the appraisal, the paperwork, and the pool of lenders.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Most DSCR lenders in the wholesale network built their core product around one-to-four unit rentals. Many stop there. A smaller group of select lenders reaches into five-plus units under separate guidelines. Those guidelines ask for more property documents, and they may use a different coverage formula.
The appraisal shows the split clearly. The standard form for two-to-four unit properties is Form 1025, listed in the Fannie Mae Selling Guide. That form is used here only as a marker of where the residential category ends. Appraisal-education material says buildings of five or more units move to commercial forms, and most states require a Certified General appraiser. The Certified General requirement is general practice, not a rule from one regulator, so confirm it for your property.
DSCR loans are not agency loans. They are business-purpose investor products placed with private lenders. The agency form name matters only because it shows why a six-unit building does not ride the same rails as a fourplex.
For the underwriting side of this decision, see Lendmire’s complete DSCR loans guide.
Key Terms Defined
DSCR (debt service coverage ratio): the property’s income divided by its debt payment, used to judge whether the building supports the loan.
PITIA: principal, interest, taxes, insurance, and any association dues, the monthly obligation that rent is measured against on smaller rentals.
NOI (net operating income): rent minus vacancy and operating expenses, used by some programs on five-plus unit buildings.
Certificate of occupancy: the local document that confirms a building may legally be used for a stated purpose, here residential housing.
Stabilized: leased up and past major rehab, with rent coming in under signed leases.
Seasoning: the time an owner has held a property before a cash-out refinance, commonly about 6 months across the network.
How Does Underwriting Treat a Converted Motel, Step by Step?
Underwriting follows a clear order. The lender classifies the building, confirms its legal use, checks the stage of conversion, collects documents, orders the appraisal, and then sizes the loan.
1. Classification. Six units means commercial multifamily underwriting. The first question is which coverage formula the program uses.
2. Legal use. The lender needs to know the building is legally six residential units. A motel that was converted without a change-of-use permit is a licensed lodging building in the eyes of the county, whatever the rooms look like.
3. Stage. DSCR financing fits buildings that are leased and operating. A building still under rehab or mostly vacant usually points to different money first.
4. Documents. Expect a rent roll, sample leases, and trailing operating statements. For a conversion, add the certificate of occupancy, permits, and zoning proof.
5. Appraisal. Expect a commercial-style report that leans on the income approach, as opposed to the residential form.
6. Sizing. Appraised value drives LTV. Coverage, credit, and reserves then set the terms.
On coverage, most programs we place files with measure rent against PITIA on one-to-four unit rentals. On five-plus unit buildings, some lenders switch to NOI over annual debt service. NOI-based underwriting counts vacancy and operating costs before the division, so the same building can show a different number under each formula. Ask which one applies before you model the deal.
For a closer look at how a lender reads a building like this, see Lendmire’s piece How a DSCR Lender Underwrites a Six-Unit Converted Motel.
Does a Converted Motel Qualify? A Status Table
Eligibility depends on where the building stands in its conversion. A fully converted, leased building is the natural fit. A building still operating nightly or mid-rehab is not.
| Building status | Income evidence | Likely route |
|---|---|---|
| Fully converted, leased | Rent roll, leases | DSCR purchase or refinance |
| Converted, newly leased | Leases, market rent support | DSCR, with closer review |
| Mid-conversion | Budget, plans, permits | Short-term money first |
| Still operating nightly | Occupancy history | Hospitality-style financing |
Any row is subject to lender guidelines, credit approval, and property review. The newly leased row is the gray one. Some lenders want to see leases in place, and some want a period of rent history. The honest answer is that it varies by program, so the file should be shopped before the contract goes hard.
What Do Lenders Look at on the Converted Units?
Lenders want proof that the units are real apartments. Layout alone does not do it.
The strongest files carry a residential certificate of occupancy, a permit trail for the change of use, and zoning confirmation. A conversion guide from a sponsor of these projects, Sage Investment, lists these same checks. It also warns that some jurisdictions allowed conversions on temporary or conditional approvals that may need renewal. If the approval expires, the income story can change overnight. Read the approval’s terms.
Physical features help the story. Units with kitchens, separate metering, and long-stay tenants look like apartments. A study from the National Association of Realtors on repurposing hotels and motels tracked exactly these traits: kitchens, extended stays, and whether a zoning application was needed. Extended-stay buildings with kitchens sit closer to apartments, which makes the legal-use question easier. The report is older, so treat it as context for how these conversions are structured, not as a current market read.
Code work can also surface. A change from commercial to residential use may trigger upgrades such as parking, occupancy limits, and fire and safety work. Those items belong in the budget before you commit.
What Does a Worked Six-Unit Example Look Like?
Run the numbers on a modeled six-unit building with every unit leased. The inputs below are modeled assumptions, not market data. They are shown as coverage ratios to keep the focus on how the result moves.
| Scenario | Coverage | Read | Typical fix |
|---|---|---|---|
| Pass | About 1.25x | Clears 1.00 with room | None needed |
| Borderline | About 1.02x | Clears barely | Add equity, review expenses |
| Fail | About 0.90x | Below 1.00 | Restructure or re-price |
Pass. At about 1.25x, rent covers the full monthly obligation with cushion. This file lets the lender focus on legal use and reserves. Stronger ratios generally open better pricing and leverage.
Borderline. At about 1.02x, the building clears 1.00 with almost no margin. Here a larger down payment helps. A bigger down payment lowers the monthly payment and lifts the ratio. It does not erase leverage caps, credit floors, or reserve rules. The strongest files clear both tests: enough equity and enough rental coverage.
Fail. At about 0.90x, the building does not clear 1.00. Coverage below 1.00 is available through select lenders in the network, with leverage and terms adjusted. That path usually means more cash down and tighter terms. Interest-only periods and extended terms such as a 40-year schedule are also available through select lenders and can lower the payment side of the ratio. Whether any of this works depends on lender guidelines, credit approval, and property review.
Before reaching for sub-1.00, ask why the number is low. If the rents sit well under what the area supports, a re-lease may fix it. If the price is simply too high for the income, the loan type is not the problem.
One caution on every scenario above. Clearing 1.00 is not the same as positive cash flow. DSCR compares rent to the payment only. Repairs, vacancy, management, utilities, and capital reserves sit outside the calculation. A converted motel with aging systems can clear the lender’s test and still run thin.
Bridge First, DSCR Second: The Sequence
When the conversion is unfinished, the usual path is short-term money to buy and finish the work, then a DSCR refinance once the building is leased. DSCR itself generally does not fund rehab.
The sequence runs in four stages:
1. Acquire the motel with short-term or construction financing.
2. Convert the rooms, complete permits, and obtain the residential certificate of occupancy.
3. Lease up the units under signed leases and build rent history.
4. Refinance into long-term DSCR financing once the building is stabilized.
Cash-out refinances across the network top out around 75% LTV on standard rentals, with about 6 months of seasoning as the common expectation. That seasoning can matter at stage four. If the lender wants to see ownership for a period before cash-out, the bridge term has to be long enough to reach it. Plan that overlap on day one. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What Equity, Credit, and Reserves Should You Plan For?
Plan for a down payment in the typical 75%-80% LTV range on a purchase, a credit score at or above the program floor, and reserves of about 6 months of PITIA. All of this is subject to lender guidelines.
- Leverage. Purchases across the network typically run 75%-80% LTV. A six-unit file in the commercial category may land toward the lower end, depending on the program and the appraisal.
- Credit. A 620 floor exists in parts of the network. Most programs want around 660, and 700 or higher opens the strongest leverage tiers.
- Reserves. About 6 months of PITIA is common. Loans above $1,500,000 typically step up to about 9 months.
- Loan size. Standard programs reach up to $3,000,000. Above $2,500,000 the network generally holds to 30-year fixed structures.
A six-unit conversion priced well under those loan limits fits comfortably. A larger building starts to push the top end of what standard programs cover.
Entity structure and recourse deserve a look before choosing a program. Loans on five-plus unit buildings can bring NOI-based underwriting, possible recourse, and balloon structures. Loans to LLC-titled borrowers are subject to lender program eligibility, so confirm the vesting before you sign. This is a place where a one-to-four unit DSCR habit can mislead you.
Insurance also deserves an early conversation. A reclassification from lodging to residential can change coverage, so get a quote that matches the new use before the file goes to a lender.
Where Does the General Rule Break?
Four cases bend the answer: partial conversions, nightly operation, expiring approvals, and a lender that stops at four units.
Partial conversion. A building that is half apartments and half licensed rooms is not six residential units. Most lenders will either decline or ask for the legal change to be finished first.
Nightly operation. A motel still renting rooms by the night is a hospitality business, not a residential rental. Short-term rental programs exist for individual rental properties, with purchase leverage up to 75% LTV, a 640 or higher credit score, about 12 months of hosting history, and a 1.00 coverage floor on purchases. A multi-room lodging operation is a different underwriting question, so ask the program before assuming it fits. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. Every figure here varies by lender and program.
For the short-term angle in more depth, see Lendmire’s article Can a Six-Unit Converted Motel Get a Short-Term Rental DSCR Loan?.
Expiring approvals. If the conversion rests on a temporary or conditional permit, the lender may see the income as at risk. Document the renewal path.
Lender reach. Many DSCR lenders stop at four units. A six-unit file only works with a lender whose guidelines reach it. That is the main reason to shop through a broker with many lenders’ guidelines in view, since the answer differs from one lender to the next.
When Is DSCR the Wrong Tool?
DSCR is the wrong tool when the building is vacant, mid-rehab, or still running as a motel. In those cases, other financing fits the stage better.
| Building condition | Better fit | Why |
|---|---|---|
| Heavy rehab remains | Short-term or construction loan | DSCR needs leased income |
| Mostly vacant | Short-term loan, then refinance | No rent to measure |
| Still nightly lodging | Hospitality or commercial bank loan | Income is not lease-based |
| Lease history is thin | Short-term loan, then refinance | Lenders want rent history |
A local bank may suit a borrower with deposit history and a long relationship. A bank loan can also carry full-documentation requirements that a rent-driven DSCR file does not. If your personal income documents are strong and the building is not yet leased, the bank route may cost less. If the building is leased and your income story is complicated, DSCR typically pencils better. Seller financing is another option when a motivated seller will tailor terms, though it sits outside the DSCR decision itself.
Frequently Asked Questions
Can a DSCR loan finance a motel that is only partly converted?
Usually not. DSCR programs generally fit stabilized, leased buildings with a legal residential use. A partly converted building often needs short-term money first, then a DSCR refinance once all six units are legal, leased, and past rehab.
Does a six-unit building use the same DSCR formula as a fourplex?
Not always. One-to-four unit programs typically measure rent against PITIA. Some five-plus unit programs use NOI over annual debt service instead, which counts vacancy and operating costs. Ask which formula applies before modeling the deal.
Can I get close to 100% financing on a converted motel?
Not through DSCR. Purchase leverage across the network typically runs 75%-80% LTV, and select high-leverage programs reach 85% only on stronger files. Investors who want to put in less cash generally use layered short-term financing during the conversion, then refinance.
Should I sell or hold after the building is stabilized?
It depends on the numbers. If coverage is strong and the building cash-flows after real expenses, holding through a DSCR refinance keeps the asset. If the conversion premium is already in the value, selling may make more sense. Test both against your reserves and goals.
Why use a broker for a six-unit file?
Lender reach varies a lot at this size. A broker placing files across many lenders can see which guidelines reach six units, which want leases in place, and which use the NOI formula. The result is a better match, not a different building.
Next Step
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges investor loans through select lenders in its wholesale network, across 41 markets including Washington, D.C. It is not a lender and does not make credit decisions. Program details change, and every file is underwritten individually by the lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Selling Guide B4-1.2-01
2. AppraiserPoint: Multi-Family Appraisal Guide
3. Sage Investment: Completed Hotel-to-Apartment Conversions
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Get a DSCR Loan on a Tiny-Home Rental · DSCR Loan vs Local Bank Commercial Loan on a Fourplex · Can You Add a HELOC Behind a DSCR Loan to Fund a Remodel?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.