
The Quick Read: 2-4 unit primary home conventional refinance loans are capped by a percentage of the appraised value, not by your equity. On a cash-out refinance of a duplex, triplex or fourplex you live in, that cap is typically 75% of value, versus 80% on a one-unit home. A refinance that only pays off the old loan and costs can reach about 95% of value at conforming loan amounts. The county loan limit and your income, debts and reserves can pull the number lower still, subject to lender guidelines and full file review.
The Short Version
- The new loan is the lowest of three ceilings: the leverage cap for your refinance type, the county loan limit for your unit count, and what your income and debts support.
- Cash-out and no-cash-out refinances use very different caps on a 2-4 unit home. The gap is about 20 percentage points.
- Cash in your hand is the maximum loan minus your payoff, closing costs and prepaids. It is never the whole cap.
- Rent from the other units can help you qualify, but the lender credits only part of it.
- Two clocks can delay a cash-out: how old your current loan is, and how long you have been on title.
What Counts as a 2-4 Unit Primary Home?
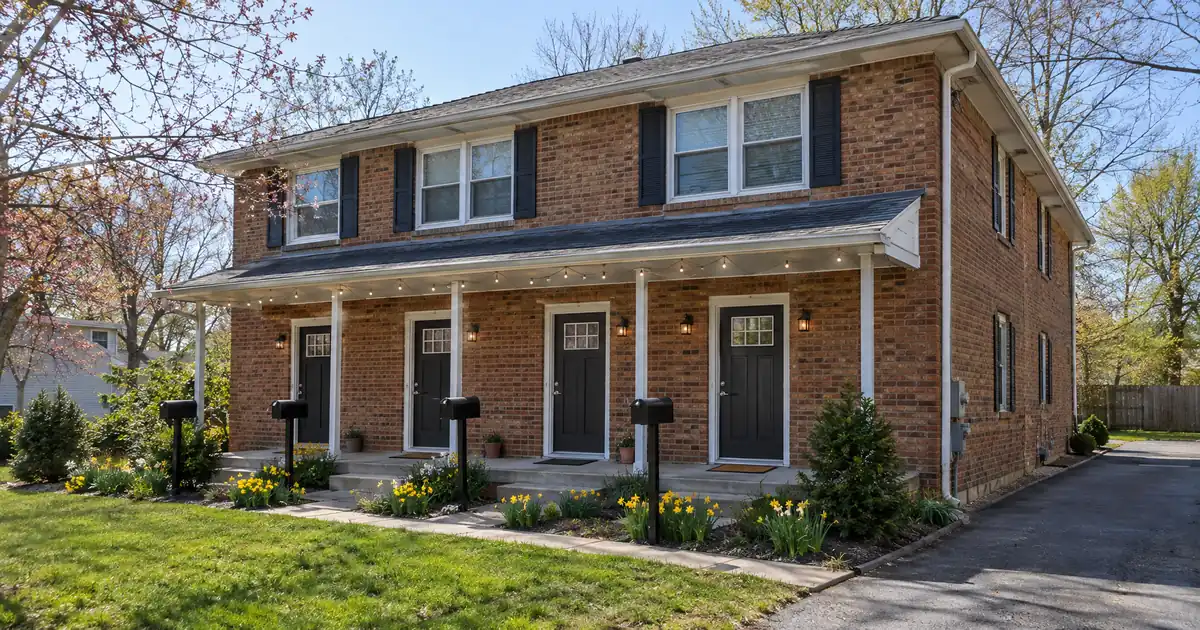
A 2-4 unit primary home is a duplex, triplex or fourplex where you live in one unit. You rent the rest. Because you occupy the building, the lender treats it as your principal residence, not as a rental property.
Refinance savings and break-even estimate
The starting figures are an example value with a balance in proportion and a placeholder for costs. Replace them with yours, and enter the current rate from your statement.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a refinance quote.
Illustrative starting assumptions: a $350,000 home value, a $245,000 current balance, a current rate you enter and a remaining term seeded at twenty-five years, closing costs seeded at $5,000 as an editable placeholder (not a fee quote) and rolled into the new loan, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The new rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a refinance quote; a refinance is priced by the lender at lock, and the current rate, the remaining term and the closing costs are figures you enter. The current payment is estimated from the balance, the current rate and the remaining term; the break-even divides the closing costs by the monthly saving and ignores the interest effect of a longer term. On the VA IRRRL the funding fee is added to the loan unless the veteran is exempt. Taxes and insurance are editable estimates. Licensed in sixteen states for consumer mortgages; Lendmire is a broker, never the lender.
That label matters more than anything else on the file. Occupancy sets which leverage table applies. The same building can fall under tighter caps if you move out and it becomes a non-owner-occupied property. One sentence covers the rest: second homes and non-owner-occupied properties carry their own caps, and this article stays with the home you live in.
Lenders offer these loans through conventional loan programs, meaning loans that follow the standards of the two agencies that buy conforming mortgages. Lendmire is a mortgage broker. It arranges these loans through wholesale lenders and does not lend directly.
How Much Can the New Loan Be?
The maximum loan is the lowest of three numbers. First comes the leverage cap for your transaction type. Second is the conforming loan limit for your county and unit count. Third is what your debts, income and reserves can carry. In practice, the leverage cap is usually the one that binds.
Fannie Mae's Eligibility Matrix lists these caps for principal residences. The matrix is revised often, and the current version controls. Lender overlays can also be stricter than the published agency caps.
| Property and purpose | Typical maximum LTV |
|---|---|
| 1 unit, cash-out | 80% |
| 2-4 units, cash-out | 75% |
| 2-4 units, no cash-out (conforming amounts) | 95% |
| 1 unit, no cash-out | 95% |
LTV, or loan-to-value, is the new loan divided by the appraised value. A 75% cap means the new loan cannot exceed three-quarters of what the appraiser says the building is worth.
The multi-unit penalty shows up only on the cash-out side. Multi-unit properties get 75% on a cash-out refinance, and the difference is a smaller cushion of cash for the same value.
The 95% no-cash-out figure is tied to conforming loan amounts. Larger balances have lower caps, and lender guidelines vary by file.
The Second Ceiling: The County Loan Limit
Conforming loans must fit under a dollar limit set each year by the federal regulator. The limit rises with unit count and differs by county. It applies to the original loan amount. Fannie Mae's loan limits guidance explains this. FHFA publishes the county-by-county table on its conforming loan limit data page.
On a modest building, the leverage cap binds first. On a high-value fourplex in an expensive county, the limit can bind first. That cuts the cash out below what the percentage math suggests. Above the limit, jumbo lanes take over with their own guidelines, starting at a 660 decision score on the wholesale lanes Lendmire places files with.
How Is the Loan Underwritten, Step by Step?
Underwriting a 2-4 unit refinance runs in a set order. Each step can lower the final number.
Step 1: Choose the refinance type. A no-cash-out refinance, also called rate-and-term, pays off the first mortgage, closing costs, prepaids and any purchase-money second lien. Only incidental cash comes back. A cash-out refinance pays off liens and returns equity. The type you pick decides which cap applies.
Step 2: The appraisal sets the value. LTV is loan divided by value, so the appraisal is the foundation. On a multi-unit home, the appraiser also reports market rents for the other units. Some refinances may qualify for a lender-accepted value estimate without a full appraisal. Do not count on that for a 2-4 unit building.
Step 3: Seasoning tests for cash-out. Fannie Mae's cash-out refinance rules set two clocks. The first mortgage being paid off must be at least 12 months old, measured note date to note date. At least one borrower must have been on title for six months. A home listed for sale must come off the market before the loan funds. Exceptions exist for delayed financing, inheritance and legal awards such as a divorce decree.
Step 4: Credit and ratios. The wholesale conventional programs Lendmire works with start at a 620 decision score. The automated underwriting finding governs most files, with a total debt-to-income ceiling of 50%. Manually underwritten loans run tighter, at 36% or 45%, depending on score and reserves. Cash-out files above 45% debt-to-income on automated casefiles need six months of reserves under the same guide.
Step 5: Apply the lowest ceiling. The underwriter takes the lowest of the leverage cap, the county limit and the ratio test. That figure is your maximum loan.
Step 6: Compare the paperwork. The lender issues a Loan Estimate. The CFPB's Loan Estimate explainer points to "Estimated Cash to Close" and the closing cost lines. Total closing costs and cash to close are not the same number, so read both.
Worked Example: From Value to Cash in Hand
These are modeled assumptions, not market data. Use percentages of value, because the dollars scale with your building.
Say you own a triplex and live in one unit. The appraisal comes in at 100% of value. Your current first mortgage balance is 60% of that value. Financed closing costs and prepaids come to a modeled 2%.
Cash-out path. The cap is 75%. Subtract the 60% payoff and the 2% costs, and about 13% of value is left as cash. That is the ceiling, before any ratio, reserve or county-limit adjustment.
No-cash-out path. The cap is 95%, but you only need the 62% to pay off and cover costs. The loan is 62% of value. Cash back is incidental. The big cap exists, but nothing is gained by using it.
Now change one input. Suppose the payoff were 78% of value because you bought recently with a small down payment. The cash-out cap of 75% sits below your payoff, so a cash-out is off the table. A no-cash-out refinance still works, because 78% fits under 95%. Mortgage insurance would apply, as covered below.
That last case is why many owners are surprised. They expect to "take out equity" and learn the cap is measured against the whole building, not against what they own of it.
Lendmire's piece How Much a Cash-Out Refinance Returns on a 2-4 Unit Primary Home runs the same arithmetic from the cash side.
How Does Rent From the Other Units Count?
Rent helps, but it does not erase the mortgage payment. A lender can add rent from the other units to your qualifying income. It does not credit 100% of it. Fannie Mae's automated underwriting job aid applies 75% of gross rent in its rental calculations. The 25% haircut stands in for vacancy and upkeep. The mortgage payment is treated as a liability and is not netted out of the rent.
The rent from the unit you live in does not count. Expect the lender to ask for current leases on the rented units, plus the appraiser's market rent schedule.
A missing lease or a unit that sits empty shrinks the income the lender can use. That can lower your qualifying ratios even when your credit is strong. If a unit has just turned over, get the new lease signed before the file goes in.
Fully leased buildings do not raise the leverage cap. The cap is set by transaction type and occupancy. Rent only affects the ratio test.
Where the General Rule Breaks
The numbers above describe the standard path. These cases move them.
Mortgage insurance changes the budget. Conventional loans above 80% LTV carry mortgage insurance. A 95% no-cash-out refinance on a 2-4 unit home normally carries it, and a 75% cash-out loan sits below that line. You can request cancellation at 80% of the original value with good payment history, no subordinate liens and no decline in value. The servicer must end it automatically at 78%, under the Homeowners Protection Act. Your Loan Estimate shows whether insurance applies.
A wholesale lane with no mortgage insurance. One lane Lendmire places with reaches 89.99% on a cash-out with no mortgage insurance. It requires a 680 score, a 50% ratio, a thirty-year fixed rate, a primary residence and a conforming balance. It carries its own six months of seasoning. Whether it fits a two- to four-unit building depends on that lender's guidelines, so ask before assuming. It is not written in Texas.
Existing second liens. A purchase-money second can be paid off inside a no-cash-out refinance. A second that was not used to buy the home generally turns the deal into a cash-out refinance, and the lower cap applies. A second lien that stays in place counts toward the combined leverage limits. The 12-month note-age rule does not apply to second liens being paid off.
Recent purchase. The six-month title clock and the 12-month loan-age clock can both block a quick equity pull on a home you just bought or refinanced. Delayed financing covers a recent all-cash purchase, and an inherited or court-awarded home can skip the title clock.
Moving out. A principal residence loan assumes you occupy the building. If you move out, the lender can treat the property as non-owner-occupied, where different caps apply.
Credit events. Agency waiting periods apply after serious credit problems: four years from a chapter 7 discharge, seven from a foreclosure, and four from a short sale or deed-in-lieu. These can be shorter with documented extenuating circumstances.
Different programs, different rows. Down-payment-assistance and income-limited programs such as HomeReady have their own rows in the matrix, with separate leverage and ratio tables. Do not assume the standard row applies.
Government loans. If your current loan is FHA or VA, streamline options exist. An FHA Streamline needs no appraisal and only a limited credit review, but it requires a net tangible benefit. A VA IRRRL carries a 0.5% funding fee unless exempt, with no VA appraisal. Those are separate from conventional.
Reserves. Reserves are the savings left after closing. Rules for 2-4 unit files can add reserve requirements beyond the 45% ratio trigger, so plan for the lender to ask. Final terms depend on the lender's guidelines, the property type, and the borrower's complete credit picture.
Texas. A cash-out on a Texas homestead is capped by the state constitution at the agency figure. That overlay is one reason state rules matter on cash-out.
What Does the Decision Look Like in Practice?
The choice comes down to what you need the money for.
You only want a different loan. Choose no-cash-out. You get the highest cap, and the cap rarely binds because you only need to cover the payoff and costs. Mortgage insurance applies above 80%. The question is whether your savings over time beat the closing costs. The CFPB notes that costs can be paid out of pocket, deducted from proceeds, or financed. The last two shrink your cash or raise your balance.
You need cash. Choose cash-out. Run the arithmetic first: 75% of value, minus your payoff, minus costs. If the number is small, the closing costs may eat most of it. Check your seasoning clocks before you apply. Lendmire's walkthrough of cash-out requirements on a 2-4 unit primary home covers the documents.
You are near the line. Sometimes the honest answer is a smaller cash-out request. Dropping the loan a few percentage points of value can clear a ratio or reserve test that a larger loan fails. A "no closing cost" refinance deserves the same skepticism. The cost is not gone. It is built into the rate or the balance.
Key Terms Defined
Principal residence. The home you live in as your main address. It qualifies for the highest leverage tables.
LTV (loan-to-value). The new loan divided by the appraised value, expressed as a percentage.
Limited cash-out (rate-and-term) refinance. A refinance that pays off the old loan, closing costs and a purchase-money second, with only incidental cash back.
Cash-out refinance. A refinance that pays off existing liens and returns extra equity to you in cash.
Seasoning. The waiting period a lender requires, such as how old your current loan is or how long you have been on title.
Reserves. Savings the lender wants to see left over after closing, measured in months of housing payments.
Conforming loan limit. The yearly dollar ceiling on loans that Fannie Mae and Freddie Mac can buy, set by unit count and county.
Running It on Your Own Home
If you are weighing a refinance and want the break-even run on your own numbers, Lendmire can help you compare the programs on the same home. Reach the team at 828-256-2183 or request a quote. Eligibility depends on lender guidelines and full file review. Nothing here is a commitment to lend.
Frequently Asked Questions
Can I take out all my equity on a duplex I live in?
No. A cash-out refinance caps the whole new loan at about 75% of appraised value on a 2-4 unit primary home. Your cash is that amount minus your payoff, closing costs and prepaids. A duplex with a recent purchase and a small down payment may have too little room under the cap for any cash at all.
Does a fully rented building raise my loan cap?
No. The cap depends on transaction type and occupancy. Rent can help your income and debt ratios, but the lender credits only part of it, and your mortgage payment stays in the debt count. Strong leases can keep you from failing the ratio test, but they do not lift the leverage cap.
Why is the no-cash-out cap so much higher than the cash-out cap?
Because the lender treats a loan that only replaces the old one as lower risk than a loan that pulls equity out. On Fannie Mae's matrix, the gap on a 2-4 unit home is roughly 95% versus 75%. The 95% figure is tied to conforming loan amounts, and lender overlays can be stricter.
How soon after buying can I do a cash-out refinance?
Usually not right away. The existing first mortgage must be at least 12 months old, and one borrower must have been on title for six months. Exceptions exist for delayed financing after an all-cash purchase, inherited property and legal awards. Lenders may add their own rules on top.
Does my county loan limit matter if I only want 75% of value?
Yes, it can. If 75% of value exceeds the limit for your unit count and county, the loan is jumbo and follows different guidelines. Check the county table on FHFA's data page. On a high-value fourplex, the limit can end up being the real ceiling.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage broker that arranges FHA, VA, conventional and jumbo home purchase and refinance financing in 16 states through wholesale lenders. Every option is subject to the lender's guidelines and full underwriting. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Eligibility Matrix
2. Fannie Mae Selling Guide, Loan Limits
3. FHFA conforming loan limit data
4. Fannie Mae Selling Guide, Cash-Out Refinance Transactions
5. CFPB Loan Estimate explainer
6. Fannie Mae Desktop Underwriter job aid, entering rental income
This article is part of Lendmire’s conventional loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Should a Conventional ARM Holder Refinance Before the Adjustment? · Is Minimum Down a Mistake on a 2-4 Unit Conventional Loan? · Can You Buy a 2-4 Unit Primary Home With a Conventional Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.