
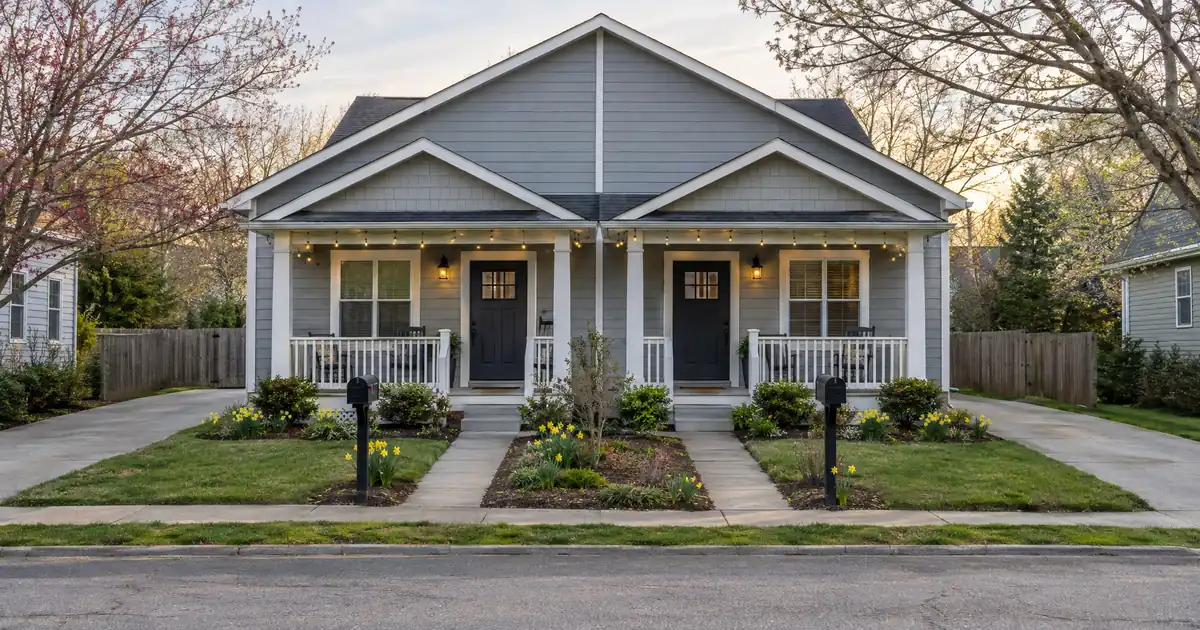
The Quick Read: Yes, if you live in one of the units. Fannie Mae and Freddie Mac both buy conventional loans on two- to four-unit homes that the borrower occupies as a principal residence. On a purchase, leverage can reach 95% of the price, subject to lender guidelines and a full file review. The loan must fit the conforming limit for its unit count, and the file carries reserve and rental-income rules that a one-unit purchase does not.
What counts as a 2-4 unit primary home?
A duplex, triplex or fourplex counts when it is residential, has four or fewer units, and you occupy one unit as your principal residence. Fannie Mae’s Selling Guide ties eligibility to residential property with four or fewer units. Five units or more moves into commercial territory and out of this lane.
Conventional payment estimate
The starting figures are an example price at the first-time buyer’s minimum down payment. Replace them with yours.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a conventional loan quote.
Estimate seeded at the low end of Fannie Mae’s published range (0.58%–1.86% a year); the insurer prices the actual premium on the score and the leverage. Applies only above 80% loan-to-value.
Illustrative starting assumptions: a $350,000 price, the first-time buyer’s minimum down payment, a thirty-year term at the current Freddie Mac benchmark, mortgage insurance at the low end of Fannie Mae’s published range, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a conventional loan quote; your rate is set by the lender at lock. The mortgage insurance figure is an editable estimate seeded from Fannie Mae’s published typical range, not a premium quote; the insurer prices the actual premium, and the cancellation month assumes scheduled payments with no extra principal and no change in value. Taxes, insurance and dues are editable estimates; closing costs are not included. Conforming loan limits apply by county. Licensed in sixteen states for consumer mortgages.
Occupancy is the line that decides everything else. Across the wholesale programs placed through conventional loan programs, the same building gets very different leverage depending on how it is used.
| Occupancy | Purchase leverage, conventional |
|---|---|
| Principal residence, 2-4 units | Up to 95% |
| Second home | Up to 90% |
| Investment property, 2-4 units | Up to 75% |
Those are program ceilings, not promises. Credit, ratios, reserves and the appraisal all still apply. If you plan to rent every unit and live elsewhere, this is not an owner-occupied loan, and the file should say so plainly.
How much down payment does a 2-4 unit purchase need?
Plan on 5% down at the low end. A two- to four-unit principal residence runs to 95% leverage on a purchase. The 97% first-time-buyer lane is written for one-unit homes, so a duplex does not get it. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
Fannie Mae’s Eligibility Matrix lists 2-4 unit principal residences at 95% for purchases and limited cash-out refinances run through automated underwriting. Cash-out is lower, at 75% on 2-4 units.
Manual underwriting is the catch. The same family of matrices shows lower caps on manually underwritten 2-4 unit files. Many older guides still print the old, tighter figures. If a file lands in manual review, expect the leverage to drop, so ask which underwriting path applies before you commit to an offer.
Above 80% leverage, mortgage insurance applies. You can request cancellation at 80% of the original value with good payment history, no second liens and no drop in value. The servicer must end it automatically at 78%. Published typical annual premiums run from 0.58% to 1.86% of the balance. That is a range, not a quote. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Do you have to live in the property, and for how long?
Yes. You must occupy it as your principal residence. Fannie Mae’s occupancy rules say that with multiple borrowers, only one must occupy and take title.
The security instrument sets a move-in window after closing. Describe your plan as moving in shortly after closing, and have your loan officer confirm the exact window on your file.
Some situations still count as owner-occupancy:
- A service member on active duty who is temporarily absent, verified with military orders.
- A parent housing a disabled adult child, or children housing a parent.
Misstating occupancy is the one mistake that cannot be fixed later. Fannie Mae has warned that the pricing gap between occupancy types tempts some borrowers to misstate it. Don’t. Occupancy is a signed representation on the loan.
What credit score and ratios do these loans need?
The wholesale conventional programs start at a 620 decision score. An adjustable rate under manual underwriting needs 640. Automated findings govern most files, with a total debt ratio ceiling of 50%. Manually underwritten loans use 36% or 45%, depending on the reserve and score factors in the Eligibility Matrix.
Credit events carry agency waiting periods:
- Four years from a chapter 7 discharge.
- Seven years from a foreclosure.
- Four years from a short sale or deed-in-lieu.
Shorter periods may apply with documented extenuating circumstances. These are agency rules, and the lender applies them to your file.
Are reserves higher on a 2-4 unit home?
Yes, and this is where many buyers get caught. A one-unit principal residence has no minimum reserve requirement in the Selling Guide. A two- to four-unit principal residence does. Fannie Mae’s reserve rule sets six months for these transactions, and automated underwriting may ask for more based on its overall risk assessment. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Reserves are months of your housing payment held in accessible assets after closing. They are separate from the down payment and closing costs. A buyer who budgets only for the 5% down and the closing costs can be short on the reserve line.
Because the exact month count can change with the automated finding on a given file, confirm the figure the system returns for yours before you write an offer.
Can rent from the other units help you qualify?
Yes, in part. Rent from the units you do not occupy can count toward qualifying. Rent from your own unit cannot. Fannie Mae’s rental income rules say rental income on the subject property must come from a two- to four-unit home where the borrower lives in one unit.
A few mechanics matter here:
- Only a portion of gross rent counts, after a vacancy allowance.
- The appraiser reports market rent for each unit on the appraisal.
- Leases for occupied units, and the appraisal rent schedule, are the usual documents.
- Borrower history changes how much counts. With a year or more as a landlord, the cap on counted rent generally falls away. With less, the counted rent for a principal residence is limited by the property’s own payment.
Many loan officers wrongly demand two years of landlord history. It is not a general requirement. A first-time landlord can still use rent, within the limits above.
Freddie Mac also treats income from units the borrower does not occupy as eligible on a 2-4 unit primary residence, provided it meets requirements, per its Seller/Servicer Guide.
One more point: on every 2-4 unit file, the lender reports each unit’s monthly rent to Fannie Mae, whether or not you use rent to qualify. A vacant unit at closing does not end the loan, but it changes what rent can be counted.
What loan limits apply to a duplex, triplex or fourplex?
Higher ones than for a single-family home. The Federal Housing Finance Agency publishes separate conforming limits by unit count, and county files show values for one to four units, per its loan limit FAQs. The agency’s annual announcement explains the baseline and the high-cost ceiling.
Look up your county on the FHFA data page. The limit for your unit count, in your county, is the number that matters. Higher multi-unit limits keep many larger purchases out of jumbo territory. Above the conforming limit, the jumbo lanes take over with a 660 decision score and different leverage.
What property and appraisal issues come up?
Expect a different appraisal. A traditional appraisal of a two- to four-unit property uses Form 1025, based on interior and exterior inspections, per the Selling Guide’s appraisal forms page. A two-unit property can use the single-family form in narrow cases, such as when the second unit’s value is insignificant.
Check these before you make an offer:
1. The legal unit count. An illegal or unpermitted unit does not count as a unit for the appraisal.
2. Condition of every unit, not only yours.
3. Whether the building is a condo or co-op. Some low-down-payment products exclude them for 2-4 units.
4. Manufactured housing. Leverage is lower there.
Property insurance requirements for 1-4 unit homes sit in a separate section of the Selling Guide. Get a full quote in early, since the insurance line can change the housing payment your lender must qualify.
Conventional, FHA or VA: which fits?
It depends on your profile. Conventional works well when you have solid credit, want mortgage insurance that cancels, and can meet the reserve line. Government loans have their own rules on leverage, premiums and reserves for 3-4 units. Each one asks different things of the file, so compare them on your own numbers rather than on a headline down payment.
If you already own a home and are weighing a later refinance, Lendmire has covered conventional cash-out limits on a 2-4 unit primary home and the requirements for that cash-out.
Where do these files stall?
A short list, drawn from how these files tend to go wrong:
- The reserve line was never budgeted.
- The file lands in manual underwriting and the leverage drops.
- Rent is counted in full when only a portion qualifies.
- A unit is not legal or is not in livable condition.
- The occupancy plan is vague.
- The buyer assumes the one-unit loan limit applies.
Document the plan to live in one unit up front. Keep leases and the appraisal rent schedule together. Confirm the reserve figure early.
Key Terms Defined
Principal residence: the home you occupy as your main residence.
Reserves: months of your housing payment held in accessible assets after closing.
LTV: loan-to-value, the loan amount as a percentage of the home’s value or price.
Conforming limit: the maximum loan size Fannie Mae and Freddie Mac will buy in a given county for a given unit count. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Form 1025: the appraisal report used for two- to four-unit properties.
Mortgage insurance: coverage the borrower pays above 80% LTV, which cancels at 80% on request and ends at 78%. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Frequently Asked Questions
Can I buy a fourplex with 5% down?
Yes, a two- to four-unit principal residence can reach 95% leverage on a purchase, subject to the automated underwriting finding and lender guidelines. Manual underwriting caps leverage lower. Reserves and mortgage insurance apply on top of the down payment. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Do I have to count rent to qualify?
No. Rent from the other units can help, but you can qualify without it. The lender still reports each unit’s rent on every 2-4 unit file. Rent from the unit you live in never counts.
How many months of reserves do I need?
The Selling Guide sets six months for a two- to four-unit principal residence, and automated underwriting can require more. A one-unit home has no minimum. Confirm the figure your file returns.
Does the first-time buyer 97% option apply to a duplex?
No. That lane is for one-unit principal residences with a fixed rate. A two- to four-unit home is capped at 95% on a purchase.
What if I move out later?
You must occupy as your principal residence when you close and shortly after. Circumstances change, but misstating your plan at application is a serious problem. Talk to your loan officer before you sign if your plans are uncertain.
If you are buying a home and want to see whether a conventional loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Program figures are subject to lender guidelines and full file review, and nothing here is a commitment to lend.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
As a mortgage broker (NMLS# 2371349), Lendmire helps homeowners and home buyers in 16 states with FHA, VA, conventional and jumbo purchase and refinance loans arranged through wholesale lenders. Lendmire is never the lender; program terms are set by the lender and the agency guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Fannie Mae Eligibility Matrix
3. Fannie Mae Selling Guide, B2-1.1-01 Occupancy Types
4. Fannie Mae Quality Insider, Oct 2025 occupancy
5. Fannie Mae Selling Guide, B3-4.1-01 Minimum Reserve Requirements
6. Fannie Mae Selling Guide, B3-3.1-08 Rental Income
9. FHFA conforming loan limit announcement
10. FHFA Conforming Loan Limit data page
11. Fannie Mae Selling Guide B4-1.2-01, Appraisal Forms
This article is part of Lendmire’s conventional loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Conventional Cash-Out Refinance Fees for a Primary Home · Can You Get Cash Out on a Refinance With a Conventional Loan? · How to Pull Cash Out of a Home With a Conventional Cash-Out Refinance
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.