Requirements For A Bank Statement HELOC
Title matters as much as income: these lines close to individuals or revocable living trusts, never LLCs.

 Lendmire Research
Title matters as much as income: these lines close to individuals or revocable living trusts, never LLCs.
Understanding both sides of the math — the traditional method and the DSCR alternative — is how you pick the right path for your next deal.
Key takeaways: – HELOC denial rates run far above closed-end mortgage denial rates nationally, and self-employed applicants sit at the center of that gap.
Credit minimums, reserve requirements, and available leverage all shift by lender, property type, and the investor’s track record.
A HELOC underwriter reviews your credit and your home’s value — not whether the dealership survives its first five years.
These are non-QM loans, which means the underwriting path is different from a conventional mortgage, not less regulated.
A home equity loan hands you a lump sum with a set repayment schedule from day one.
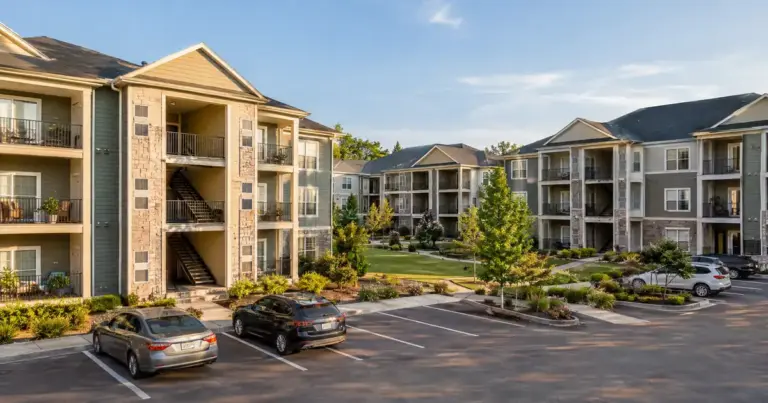
A one-to-four-unit rental refinances through DSCR and non-QM channels, qualifying primarily on rental income covering the payment.
Seasoning, the new appraisal, and the property’s coverage ratio decide how much of that equity actually shows up at closing — appraised value alone doesn’t.
Credit, equity, and title rules still apply in full — this only changes how income gets proven.
– Underwriters don’t count raw deposits as income.
No-ratio DSCR Loan How Long It Takes: what investors need to know about DSCR financing — eligibility, coverage, and loan structure, from Lendmire.
Credit Score Needed To Use A HELOC To Purchase Investment Property — The answer depends on which property secures the line.
Apartment Investment Property Refinance Lenders — The lender you end up with depends almost entirely on unit count.