Which Wichita Banks Or Credit Unions Give Home Equity Loans On Investment Property?
Which Wichita Banks Or Credit Unions Give Home Equity Loans On Investment Property?

 Lendmire Research
Which Wichita Banks Or Credit Unions Give Home Equity Loans On Investment Property?
Agency lenders still lean on two years of tax returns and a 25%-ownership test.
Home Equity On Investment Property — Yes, you can pull equity out of a rental, but underwriting treats it nothing like a primary home.
Apartment Investment Property Refinance Loan Finance — Unit count decides everything before a lender even looks at the numbers.
The mechanics look very different depending on where you’re bidding, though.
Non-QM lenders often replace that with bank deposits and an expense factor instead of a tax return.
Investors holding property in an entity typically need a different structure altogether.
Property titled inside an LLC compounds the problem, since a personal HELOC generally requires title in an individual’s name or a revocable living trust.
Lenders classify it as business-purpose credit, cap leverage lower, and want a stronger credit file before they’ll even open the underwriting review.
The real workaround is buying with cash first, then refinancing into hard money once the deed records.
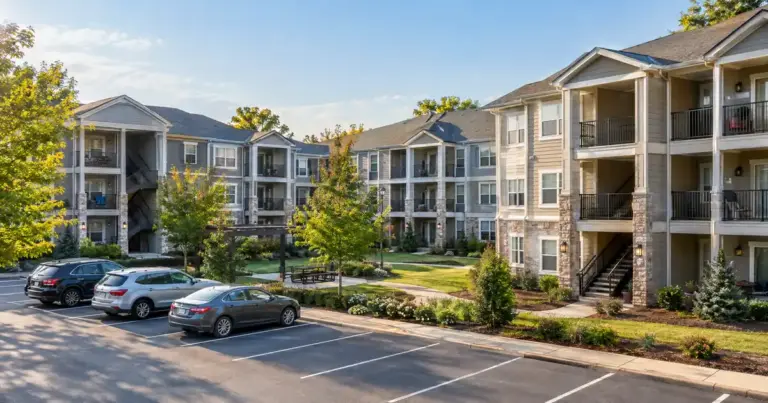
Getting the classification right up front determines the appraisal form, the documentation, and the leverage ceiling for everything downstream.
Title matters as much as income: these lines close to individuals or revocable living trusts, never LLCs.
Understanding both sides of the math — the traditional method and the DSCR alternative — is how you pick the right path for your next deal.
Key takeaways: – HELOC denial rates run far above closed-end mortgage denial rates nationally, and self-employed applicants sit at the center of that gap.
Credit minimums, reserve requirements, and available leverage all shift by lender, property type, and the investor’s track record.