What Is A Condotel Loan? How Lenders Underwrite Resort Units
Standard mortgage financing won’t touch these units, so the entire condotel market runs through non-QM and DSCR-style investor lending instead.

 Lendmire Research
Standard mortgage financing won’t touch these units, so the entire condotel market runs through non-QM and DSCR-style investor lending instead.
What Is A Blanket Mortgage On Rentals For Portfolio Investors: what investors need to know about large-balance DSCR financing, from Lendmire.
Underwriters pull 12 or 24 months of statements, subtract an expense ratio to estimate real income, and lend against that number.
Loan size can run from $150,000 up through multi-million-dollar purchases, with leverage stepping down as the balance grows.
Above roughly $3.5 million to $4 million, files move to case-by-case review before submission.
The new loan amount matches roughly what you still owe, not what the property is worth today.
Nightly-rate income looks great on paper, but lenders don’t use the raw number.
DSCR loans qualify the property, not the person, using rental income to cover the payment.
The difference between the new balance and the old payoff comes back to you in cash.
The lender divides eligible assets by a set number of months instead of counting Social Security or a pension alone.
The tricky part is the income itself — a ski cabin might earn most of its money in three winter months, and a lake house in three summer ones.
Instead of a studio, team, or client paying the entertainer, athlete, or consultant directly, the third party pays the entity.
The point is cash flow: a lower monthly obligation raises the coverage ratio on the same rent roll.
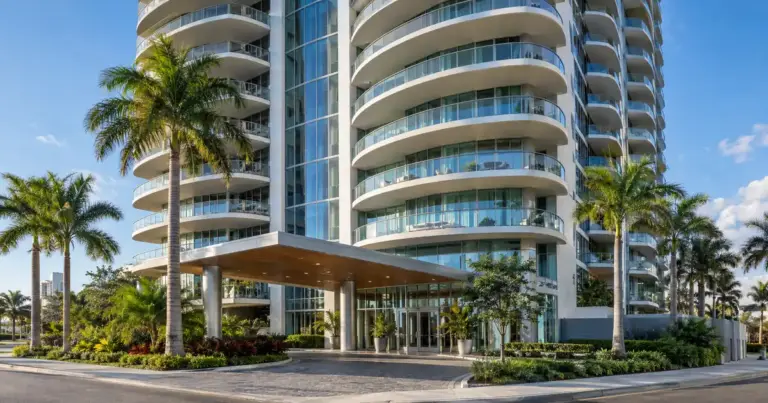
Fannie Mae and Freddie Mac won’t buy loans on buildings that operate like hotels, so those files never reach agency underwriting at all.
Buy a straight rental property and the loan can run on the property’s own income, sidestepping the client-concentration question almost entirely.